
Request a Conventional Loan Review
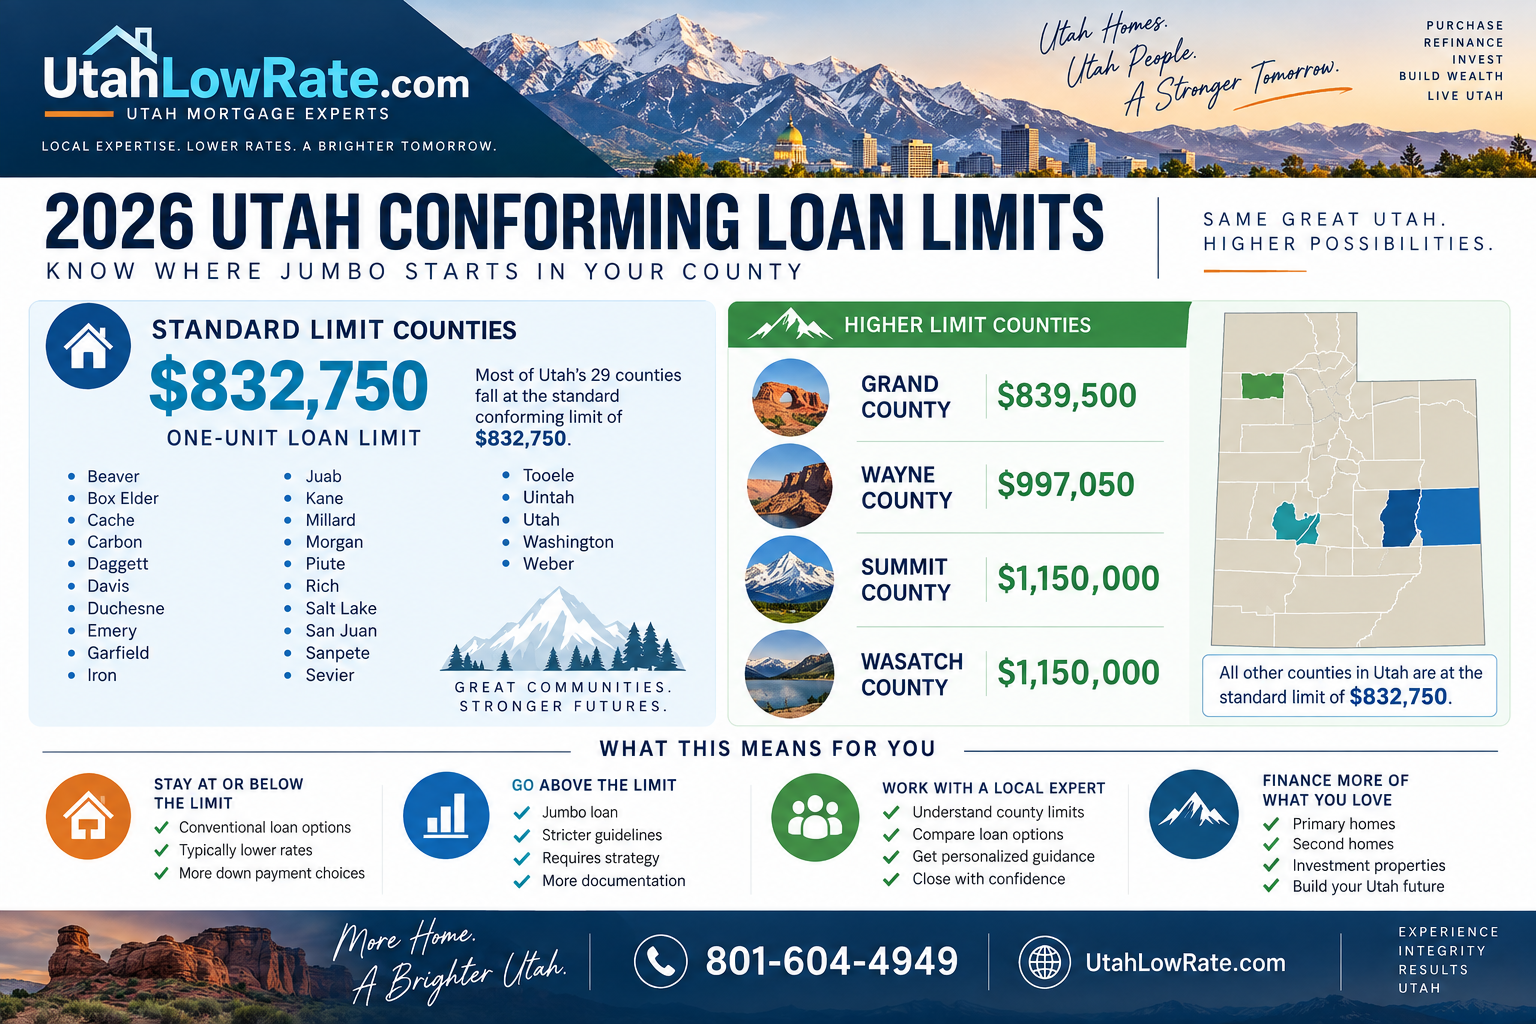
2026 Utah Conforming Loan Limits by County
Looking for the conventional loan limits for Utah in 2026? The Federal Housing Finance Agency (FHFA) establishes conforming loan limits each year for mortgages eligible for purchase by Fannie Mae and Freddie Mac.
For 2026, the baseline conventional conforming loan limit in most Utah counties is $832,750 for a one-unit property.
However, four Utah counties have higher one-unit conforming loan limits:
- Grand County: $839,500
- Wayne County: $997,050
- Summit County: $1,150,000
- Wasatch County: $1,150,000
The applicable limit depends on the county where the property is located and whether the property contains one, two, three or four residential units.
Quick Answer: What Is the Conventional Loan Limit in Utah for 2026?
For most Utah counties, the 2026 conventional conforming loan limit is $832,750 for a one-unit home.
The standard 2026 conforming loan limits are:
| Property Type | 2026 Baseline Loan Limit |
|---|---|
| 1 Unit | $832,750 |
| 2 Units | $1,066,250 |
| 3 Units | $1,288,800 |
| 4 Units | $1,601,750 |
Grand, Summit, Wasatch and Wayne counties have higher limits.
The loan limit applies to the mortgage amount, not the purchase price of the property.
2026 Utah Conventional Loan Limits at a Glance
- Most Utah counties, 1 unit: $832,750
- Most Utah counties, 2 units: $1,066,250
- Most Utah counties, 3 units: $1,288,800
- Most Utah counties, 4 units: $1,601,750
- Summit County, 1 unit: $1,150,000
- Wasatch County, 1 unit: $1,150,000
- Wayne County, 1 unit: $997,050
- Grand County, 1 unit: $839,500
- National 2026 high-cost ceiling, 1 unit: $1,249,125
- Federal agency establishing conforming limits: FHFA
- Mortgage enterprises: Fannie Mae and Freddie Mac
2026 Conventional Loan Limits for Utah by County
Use the table below to find the 2026 conforming loan limit for every Utah county.
| Utah County | 1 Unit | 2 Units | 3 Units | 4 Units |
|---|---|---|---|---|
| Beaver | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Box Elder | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Cache | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Carbon | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Daggett | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Davis | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Duchesne | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Emery | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Garfield | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Grand | $839,500 | $1,074,700 | $1,299,100 | $1,614,450 |
| Iron | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Juab | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Kane | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Millard | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Morgan | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Piute | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Rich | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Salt Lake | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| San Juan | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Sanpete | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Sevier | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Summit | $1,150,000 | $1,472,250 | $1,779,600 | $2,211,600 |
| Tooele | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Uintah | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Utah | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Wasatch | $1,150,000 | $1,472,250 | $1,779,600 | $2,211,600 |
| Washington | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
| Wayne | $997,050 | $1,276,400 | $1,542,900 | $1,917,450 |
| Weber | $832,750 | $1,066,250 | $1,288,800 | $1,601,750 |
Source: Federal Housing Finance Agency 2026 conforming loan-limit data.
Mortgage limits and underwriting requirements can change. Always verify the applicable county and current mortgage requirements before making a financing decision.
Which Utah Counties Have Higher Conventional Loan Limits in 2026?
Four Utah counties have one-unit conventional conforming loan limits above the standard $832,750 baseline.
Summit County — $1,150,000
The 2026 one-unit conforming loan limit for Summit County is $1,150,000.
This higher limit can be particularly important for buyers in:
- Park City
- Snyder Ville Basin
- Kamas
- Coalville
- Hideout-area properties located in Summit County
- Other Summit County communities
A qualifying mortgage does not automatically become a jumbo loan simply because it exceeds $832,750 when the property is located in Summit County.
Wasatch County — $1,150,000
The 2026 one-unit conforming loan limit for Wasatch County is $1,150,000.
Wasatch County includes communities such as:
- Heber City
- Midway
- Charleston
- Daniel
- Walls burg
- Wasatch County portions of the Jordanelle area
The higher county limit can allow qualifying borrowers to finance higher loan amounts while remaining within the applicable conforming limit.
Wayne County — $997,050
The 2026 one-unit conforming loan limit for Wayne County is $997,050.
This is substantially higher than the $832,750 baseline used throughout most Utah counties.
Grand County — $839,500
The 2026 one-unit conforming loan limit for Grand County is $839,500.
Grand County includes Moab and surrounding communities.
Although the increase above the standard limit is modest, borrowers purchasing in Grand County should use the county-specific $839,500 limit rather than the statewide baseline.
Conventional Loan Limits in Major Utah Housing Markets
Salt Lake County Conventional Loan Limit 2026
The 2026 one-unit conventional loan limit in Salt Lake County is $832,750.
This limit applies throughout communities such as:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale, Midvale, Taylorsville and South Salt Lake.
The corresponding limits for qualifying two-, three- and four-unit properties are higher.
Utah County Conventional Loan Limit 2026
The 2026 one-unit conforming loan limit in Utah County is $832,750.
This includes:
Provo, Orem, Lehi, Alpine, Highland, American Fork, Pleasant Grove, Saratoga Springs, Eagle Mountain, Spanish Fork and surrounding Utah County communities.
A purchase price above $832,750 does not automatically require jumbo financing because the conforming threshold applies to the loan amount, not the home's price.
Park City Conventional Loan Limit 2026
There is no single conventional loan limit based solely on the name Park City.
Conforming limits are based on the county where the property is located.
For a qualifying one-unit property located in Summit County, the 2026 limit is:
$1,150,000
This makes county verification particularly important when financing homes throughout the greater Park City market.
Heber City Conventional Loan Limit 2026
Heber City is located in Wasatch County.
The 2026 one-unit conventional conforming loan limit for Wasatch County is $1,150,000.
The higher limit can also be relevant for buyers financing properties in Midway and surrounding Wasatch Back communities.
St. George Conventional Loan Limit 2026
St. George is located in Washington County.
The 2026 one-unit conventional loan limit in Washington County is $832,750.
The same baseline applies to communities such as:
- St. George
- Washington
- Ivins
- Santa Clara
- Hurricane
- La Verkin
- Other Washington County communities
Borrowers needing a mortgage above the applicable limit may need to compare jumbo or another non-conforming mortgage option.
What Is a Conventional Conforming Loan Limit?
A conforming loan limit is the maximum mortgage balance permitted under the applicable loan-size requirements for a mortgage to remain eligible for acquisition by Fannie Mae or Freddie Mac.
The Federal Housing Finance Agency establishes conforming loan limits annually.
The 2026 baseline limit for a one-unit property increased to:
$832,750
Certain higher-cost housing markets receive larger county-specific loan limits.
Why Did Conventional Loan Limits Increase for 2026?
FHFA adjusts conforming loan limits based on changes in average U.S. home values under federal law.
The baseline one-unit limit increased from:
2025: $806,500
to
2026: $832,750
That is a $26,250 increase, or approximately 3.26%.
Higher conforming limits allow the loan-size framework used by Fannie Mae and Freddie Mac to adjust as national housing values change.
What Is the 2026 High-Cost Conforming Loan Ceiling?
The maximum 2026 high-cost conforming loan ceiling for a one-unit property in the contiguous United States is:
$1,249,125
That equals 150% of the $832,750 national baseline.
However, the national ceiling does not mean every designated higher-cost county receives a $1,249,125 limit.
For example:
- Summit County: $1,150,000
- Wasatch County: $1,150,000
- Wayne County: $997,050
- Grand County: $839,500
Each county's applicable conforming limit must be checked individually.
Is the Conventional Loan Limit Based on Purchase Price or Loan Amount?
The conforming loan limit applies to the mortgage amount—not the home's purchase price.
This is one of the most important distinctions for Utah homebuyers to understand.
For example:
Purchase price: $1,000,000
County: Salt Lake County
Down payment: $167,250
Loan amount: $832,750
The purchase price is higher than Salt Lake County's one-unit conforming limit, but the mortgage amount is $832,750.
Therefore, the loan amount itself remains within the applicable 2026 conforming limit, subject to all other program and underwriting requirements.
Conventional vs. Conforming vs. Jumbo Loans
The terms conventional, conforming and jumbo are related, but they are not interchangeable.
Conventional Loan
A conventional mortgage is generally a home loan that is not insured or guaranteed by a federal government agency such as FHA, VA or USDA.
Conforming Loan
A conforming loan is a conventional mortgage that meets applicable Fannie Mae or Freddie Mac requirements, including the property's applicable conforming loan limit.
Jumbo Loan
A mortgage that exceeds the applicable conforming limit for the county and number of property units is generally considered a jumbo loan for loan-limit purposes.
Simple Answer
Every conforming mortgage is conventional, but not every conventional mortgage is conforming.
When Does a Utah Mortgage Become a Jumbo Loan?
For a one-unit property in most Utah counties, a mortgage above:
$832,750
exceeds the 2026 baseline conforming loan limit.
However, Utah has higher thresholds in four counties:
| Utah County | 2026 1-Unit Limit |
|---|---|
| Grand | $839,500 |
| Wayne | $997,050 |
| Summit | $1,150,000 |
| Wasatch | $1,150,000 |
Example
A $900,000 mortgage in Salt Lake County exceeds the $832,750 one-unit conforming limit.
A $900,000 mortgage in Summit County, however, is below Summit County's $1,150,000 one-unit conforming limit.
The property's county therefore matters when determining whether a mortgage exceeds conforming loan limits.
What If My Loan Is Above Utah's Conventional Loan Limit?
Exceeding a conforming loan limit does not mean you cannot finance the property.
You may need to consider a mortgage designed for higher loan amounts.
Potential options can include:
- Jumbo mortgages
- Super jumbo mortgages
- Bank statement jumbo loans
- Asset-based mortgage programs
- Non-QM loans
- Portfolio mortgage programs
- Other non-conforming financing
These options can be particularly important in higher-priced Utah markets such as Park City, Deer Valley, Heber City, Midway and luxury communities throughout the Wasatch Front and Wasatch Back.
1-Unit, 2-Unit, 3-Unit and 4-Unit Conventional Loan Limits
Conforming limits generally increase when an eligible residential property contains multiple units.
For most Utah counties in 2026:
| Units | Loan Limit |
|---|---|
| 1 Unit | $832,750 |
| 2 Units | $1,066,250 |
| 3 Units | $1,288,800 |
| 4 Units | $1,601,750 |
The increased limit does not automatically mean a borrower qualifies for that mortgage amount.
Qualification can still depend on income, debts, credit, assets, occupancy, reserves, loan-to-value ratio, property eligibility and other underwriting requirements.
Does the 2026 Loan Limit Determine How Much I Can Borrow?
No.
A conforming loan limit establishes a maximum mortgage size for purposes of conforming classification. It does not establish the amount for which an individual borrower qualifies.
Mortgage qualification can depend on:
- Income
- Employment
- Credit history
- Credit score
- Monthly debt
- Debt-to-income ratio
- Down payment
- Assets
- Cash reserves
- Property value
- Property type
- Occupancy
- Loan-to-value ratio
- Automated underwriting
- Fannie Mae or Freddie Mac requirements
A county conforming limit should never be interpreted as an automatic mortgage approval.
Are FHA Loan Limits the Same as Conventional Loan Limits?
No.
FHA loans and conventional conforming mortgages use different loan-limit systems.
FHA mortgages are insured by the Federal Housing Administration and use applicable HUD/FHA mortgage limits.
Conforming conventional mortgages use FHFA conforming loan limits associated with Fannie Mae and Freddie Mac.
Homebuyers comparing an FHA loan with a conventional loan should verify the applicable limit for each program.
Are VA Loan Limits the Same as Conventional Loan Limits?
No.
VA mortgages operate under Department of Veterans Affairs rules governing eligibility, entitlement and the VA home-loan guaranty.
The FHFA conforming loan limit should not be assumed to establish the maximum amount an eligible veteran can finance with a VA mortgage.
Utah Conventional Loan Limit Examples for 2026
Example 1: Salt Lake City
Purchase price: $900,000
Mortgage: $800,000
County: Salt Lake County
2026 one-unit limit: $832,750
Because the $800,000 mortgage is below the county's $832,750 conforming limit, the home's $900,000 purchase price by itself does not require jumbo financing.
Example 2: Park City
Purchase price: $1,400,000
Mortgage: $1,100,000
County: Summit County
2026 one-unit limit: $1,150,000
The $1,100,000 mortgage is below Summit County's $1,150,000 conforming limit.
Example 3: Heber City
Purchase price: $1,300,000
Mortgage: $1,000,000
County: Wasatch County
2026 one-unit limit: $1,150,000
The $1,000,000 loan is within the applicable Wasatch County one-unit conforming limit.
Example 4: St. George
Purchase price: $1,000,000
Mortgage: $850,000
County: Washington County
2026 one-unit limit: $832,750
The $850,000 mortgage exceeds Washington County's $832,750 conforming limit, which means the borrower may need to compare jumbo or other non-conforming financing.
These examples illustrate loan-limit classification only. They are not mortgage approvals or guarantees of program eligibility.
Frequently Asked Questions About Conventional Loan Limits for Utah 2026
What is the 2026 conventional loan limit in Utah?
The standard 2026 conventional conforming loan limit is $832,750 for a one-unit property in most Utah counties. Grand, Summit, Wasatch and Wayne counties have higher one-unit limits.
What is the conventional loan limit in Salt Lake County for 2026?
The 2026 one-unit conforming loan limit in Salt Lake County is $832,750.
What is the conventional loan limit in Utah County for 2026?
The 2026 one-unit conforming loan limit in Utah County is $832,750.
What is the Summit County conventional loan limit for 2026?
The 2026 one-unit conventional conforming loan limit in Summit County is $1,150,000.
What is the Wasatch County conventional loan limit for 2026?
The 2026 one-unit conventional conforming loan limit in Wasatch County is $1,150,000.
What is the Grand County conventional loan limit for 2026?
The 2026 one-unit conforming loan limit in Grand County is $839,500.
What is the Wayne County conventional loan limit for 2026?
The 2026 one-unit conforming loan limit in Wayne County is $997,050.
What is the Washington County conventional loan limit for 2026?
The 2026 one-unit conventional conforming loan limit in Washington County is $832,750.
What is the Park City conventional loan limit for 2026?
The limit depends on the county where the property is located. For a one-unit Park City property located in Summit County, the 2026 conforming loan limit is $1,150,000.
Does a home over $832,750 automatically require a jumbo loan?
No. The conforming limit applies to the mortgage amount, not simply the home's purchase price. A more expensive home can potentially be financed with a conforming mortgage when the loan amount remains within the applicable county limit and all other requirements are satisfied.
When does a conventional mortgage become a jumbo mortgage?
A mortgage generally exceeds conforming loan-limit parameters when the loan amount is above the applicable FHFA limit for the property's county and unit count.
Do conventional loans require 20% down?
No. A 20% down payment is not universally required for conventional mortgages. Eligible borrowers may have conventional options with smaller down payments, although mortgage insurance and other requirements may apply.
Do conventional loan limits change every year?
FHFA evaluates conforming loan limits annually. Limits can increase, remain unchanged or otherwise vary based on the formula required by federal law and applicable high-cost-area calculations.
Conventional or Jumbo Mortgage? Compare Your Utah Options
Understanding the conventional loan limits for Utah in 2026 helps determine whether a desired mortgage falls within conforming loan-limit parameters or may require jumbo financing.
The best mortgage option can depend on:
- Property location
- Purchase price
- Desired loan amount
- Down payment
- Credit
- Income
- Assets
- Reserves
- Occupancy
- Property type
Daniel Paris at UtahLowRate.com helps Utah homebuyers and homeowners compare conventional, conforming, jumbo, super jumbo and alternative mortgage options.
Daniel Paris | UtahLowRate.com
Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
801-604-4949
If your desired loan amount falls within the applicable conforming limit, review our Conventional Mortgage Loans Utah page to learn more about conventional mortgage qualification and financing options.
If the mortgage exceeds the applicable county limit, review our Jumbo Mortgage Utah options for higher-balance financing.
Get a Utah Mortgage Quote
Buying or refinancing a home in Utah?
Contact Daniel Paris at UtahLowRate.com to compare mortgage programs based on your property location, loan amount and financial profile.
Call 801-604-4949
UtahLowRate.com
About This 2026 Utah Conventional Loan Limit Guide
This resource is provided by UtahLowRate.com to help Utah homebuyers, homeowners and real estate professionals understand 2026 conventional and conforming loan limits in Utah.
The loan-limit figures are based on Federal Housing Finance Agency data for mortgages acquired by Fannie Mae and Freddie Mac during calendar year 2026.
Loan limits, mortgage guidelines and underwriting requirements can change. Verify the applicable county limit and current program requirements before relying on this information for a mortgage transaction.
Daniel Paris
UtahLowRate.com
Utah Mortgage Broker
801-604-4949

