
Luxury Home Financing for Draper, Utah Buyers and Homeowners
Buying or refinancing a higher-priced home in Draper, Utah may require a mortgage amount above the applicable conforming loan limit. Jumbo loans in Draper, UT can provide financing for qualified borrowers purchasing luxury homes, custom residences and other high-value properties that require larger mortgage amounts.
Daniel Paris of UtahLowRate.com helps qualified Draper homebuyers and homeowners compare jumbo mortgage options based on the property, requested loan amount, income, assets, credit profile and overall financial situation.
Whether you are purchasing near Sun Crest, Corner Canyon, Traverse Ridge or another Draper neighborhood, the financing strategy should be built around the individual property and borrower—not simply the home's purchase price.
Daniel Paris | Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Mortgage programs, rates, loan amounts, LTVs and underwriting requirements are subject to change and borrower/property qualification.
Quick Answer: What Is a Jumbo Loan in Draper, Utah?
A jumbo loan in Draper, Utah is generally a mortgage with a loan amount above the conforming loan limit applicable to the property. Jumbo financing can be useful for qualified buyers purchasing or refinancing higher-value Draper homes, including luxury residences and custom properties.
For complete statewide information about conforming limits, jumbo requirements, rates and Utah financing options, see our Jumbo Mortgage Utah guide.
Jumbo Financing for Draper's Higher-Value Housing Market
Draper is positioned along the southern end of the Salt Lake Valley near the Wasatch Mountains and includes a wide range of residential properties.
Some transactions involve larger custom homes, mountain-view residences, executive homes and properties requiring mortgage amounts above standard conforming limits.
Areas where buyers may encounter higher-value properties include:
- Suncrest
- Corner Canyon
- Traverse Ridge
- South Mountain
- East Draper
- Wasatch foothill neighborhoods
- Custom-home communities throughout Draper
The purchase price alone does not determine whether a mortgage is jumbo.
The requested loan amount, applicable conforming limit and selected mortgage program are important factors.
Who May Need a Jumbo Loan in Draper?
Draper jumbo financing may be appropriate for qualified borrowers who are:
- Purchasing a higher-priced Draper home
- Buying a custom or luxury residence
- Moving into a larger home
- Relocating to Draper for employment
- Purchasing a property requiring financing above conforming limits
- Refinancing an existing high-balance mortgage
- Seeking financing with a more complex income or asset profile
Draper's professional and business community can also create financing situations where income is not limited to a straightforward W-2 salary.
Borrowers may include executives, physicians, attorneys, technology professionals, entrepreneurs, business owners and other self-employed professionals.
The appropriate mortgage structure depends on the borrower's actual financial profile and the property being financed.
Buying a Luxury or Custom Home in Draper
Financing a high-value home can involve considerations that are less common with a typical conforming mortgage.
A lender may need to evaluate the property's characteristics, comparable sales, appraisal, borrower liquidity and overall financial strength.
This can be especially important with:
- Custom-built homes
- Larger residences
- Unique architectural properties
- Mountain or valley-view homes
- Properties with substantial upgrades
- Homes where comparable sales are limited
- Properties with acreage or unusual features
A custom home's purchase price does not automatically establish its appraised value.
For that reason, buyers should consider their mortgage strategy early in the purchase process.
Draper Jumbo Mortgage Pre-Approval
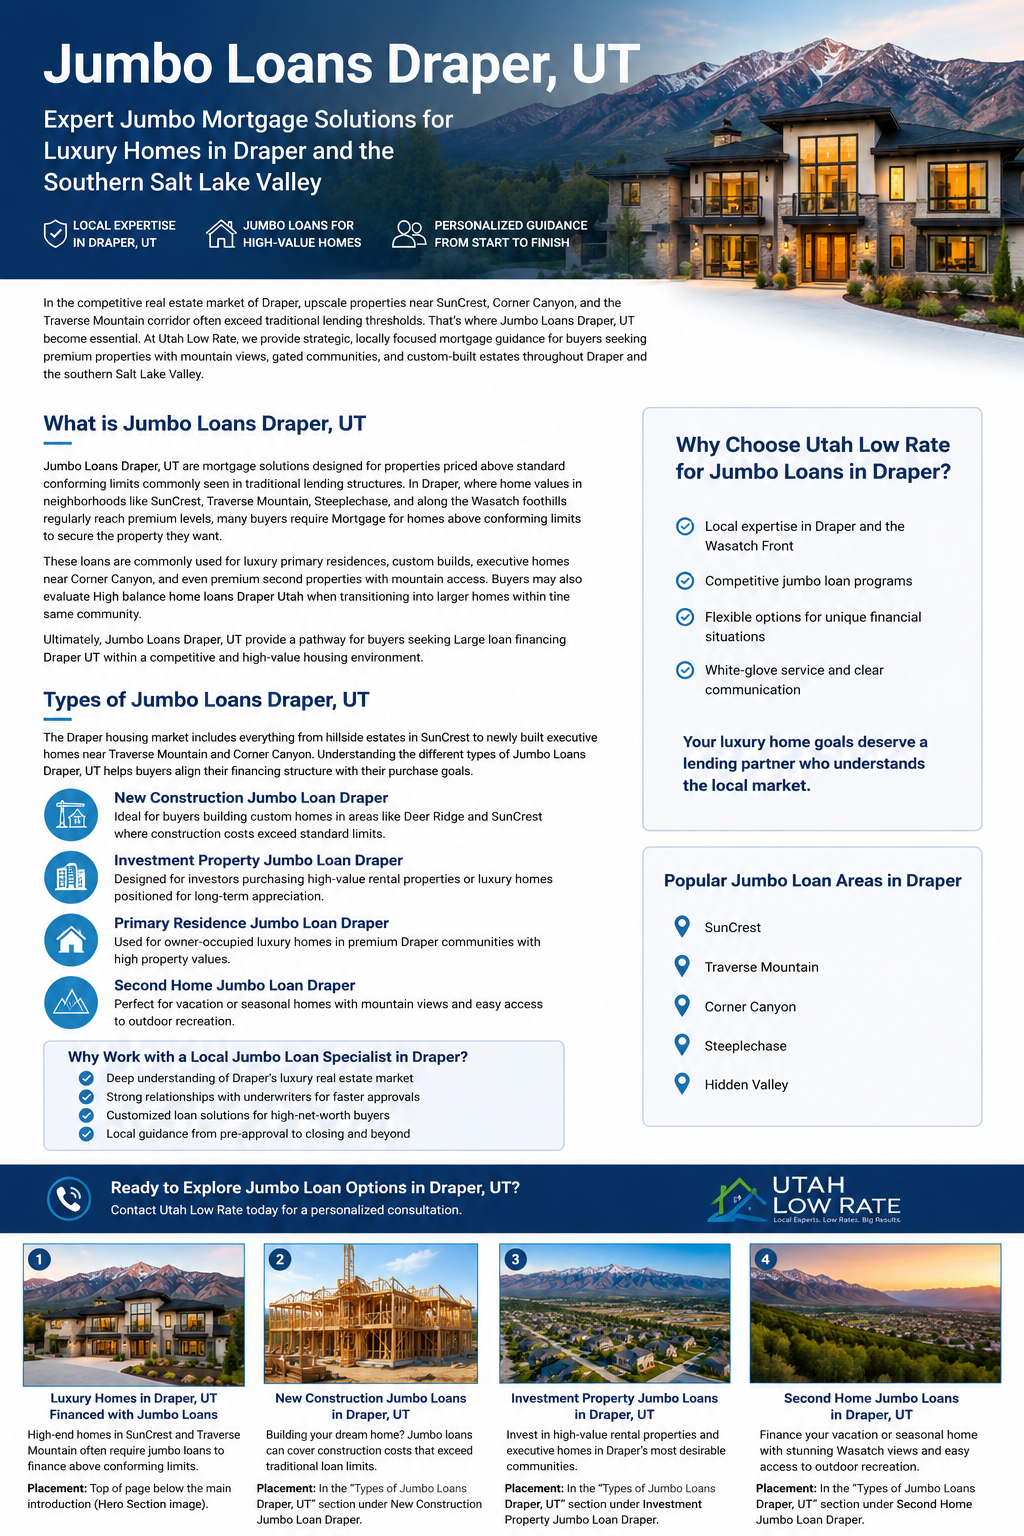
Obtaining a preliminary jumbo mortgage review before making an offer can be particularly helpful when shopping for higher-priced Draper real estate.
Jumbo underwriting can involve more documentation and analysis than a standard conforming mortgage.
Depending on the program and borrower, the lender may evaluate:
- Income
- Employment
- Credit
- Assets
- Available funds for closing
- Post-closing liquidity
- Proposed down payment
- Property type
- Occupancy
- Requested loan amount
Starting early can help identify potential documentation or financing issues before the buyer is under contract.
Buying a High-Value Home in Draper?
Speak with Daniel Paris before submitting an offer to discuss potential jumbo financing options for the property.
Call 801-604-4949
Jumbo Loans for Draper Move-Up Buyers
Some Draper buyers are not entering the market for the first time.
They may already own a home in Salt Lake County or elsewhere along the Wasatch Front and are moving into a larger or higher-value property.
These transactions can create questions involving:
- Equity from the existing residence
- Timing the current home's sale
- Down-payment strategy
- Available liquid assets
- Mortgage reserves
- Existing housing obligations
- Debt-to-income calculations
The financing should be evaluated in the context of the complete transaction rather than looking only at the new home's purchase price.
Jumbo Mortgages for Professionals Relocating to Draper
Draper's location between Salt Lake County and northern Utah County makes it a potential home base for professionals working throughout the Wasatch Front.
A relocating borrower may have additional mortgage considerations involving:
- New employment
- Employment contracts
- Bonuses
- Commission income
- Restricted stock or other compensation
- Sale of an existing residence
- Assets being transferred between institutions
- Timing of relocation
The documentation required depends on the mortgage program and lender guidelines.
Reviewing these issues before entering a purchase contract can make the financing process easier to plan.
Self-Employed Jumbo Borrowers in Draper
Draper has many business owners, entrepreneurs and independent professionals whose income may be more complex than traditional salaried employment.
Traditional jumbo financing generally evaluates qualifying income according to the lender's documentation requirements.
However, qualified self-employed borrowers may also have access to alternative mortgage programs when traditional tax-return calculations do not accurately reflect their financial situation.
Depending on current program availability, alternatives may include bank-statement or other non-QM documentation methods.
Rather than duplicating those guidelines here, borrowers who need alternative income documentation should review our dedicated Bank Statement Loans Utah and Jumbo Bank Statement Loans Utah resources.
Refinancing a Jumbo Mortgage on a Draper Home
Draper homeowners with larger existing mortgages may also consider jumbo refinancing.
Potential objectives can include:
- Changing the mortgage term
- Restructuring existing financing
- Evaluating a different mortgage product
- Accessing eligible home equity
- Adjusting financing after a significant change in assets or income
Whether refinancing makes financial sense depends on the homeowner's current mortgage, available rate and terms, closing costs, equity, intended ownership period and financial objectives.
Current pricing should be evaluated when the borrower is actually considering a refinance rather than relying on a static rate published on a local landing page.
Draper Jumbo Mortgage Rates
Jumbo mortgage rates in Draper can change frequently and are not determined simply by the city where the property is located.
Pricing can depend on factors such as:
- Loan amount
- Credit profile
- Loan-to-value ratio
- Property type
- Occupancy
- Mortgage term
- Income documentation
- Assets and reserves
- Points or lender credits
- Current financial-market conditions
Two borrowers purchasing similarly priced Draper homes may therefore receive different mortgage pricing.
For broader information about Utah jumbo mortgage rates and qualification requirements, visit our statewide Jumbo Mortgage Utah resource.
For an individual Draper jumbo mortgage scenario, request a personalized quote.
Call Daniel Paris at 801-604-4949.
Draper Jumbo Loan Requirements
There is no single qualification standard that applies to every Draper jumbo mortgage.
Requirements vary by lender, loan amount and program.
Underwriting may consider the borrowers:
- Credit profile
- Income
- Employment
- Debt obligations
- Assets
- Liquidity
- Down payment or equity
- Reserves
- Property
- Occupancy
- Loan amount
Because this page is specifically about Draper jumbo financing, complete statewide qualification information is maintained on our Jumbo Mortgage Utah page rather than duplicated here.
That resource explains Utah jumbo mortgage requirements in greater detail.
Draper Jumbo Loans vs. Standard Conforming Financing
The most important distinction is generally the loan amount.
When the requested mortgage fits within applicable conforming limits and otherwise meets conforming requirements, conventional financing may be available.
When the required loan amount exceeds the applicable conforming limit, the borrower may need jumbo or another eligible non-conforming financing structure.
You do not need to determine this yourself.
Daniel Paris can review the Draper property's price, propose down payment and requested mortgage amount to help identify which category may apply.
Why Property Valuation Matters for Draper Luxury Homes
Appraisals can be particularly important with custom and higher-value properties.
A highly customized Draper home may include features that are difficult to compare directly with nearby sales.
Examples could include:
- Extensive renovations
- Premium lots
- Mountain views
- Larger lot sizes
- High-end finishes
- Custom architecture
- Outdoor living improvements
- Oversized garages
- Specialty rooms or amenities
Jumbo lenders may have specific appraisal requirements depending on the transaction and loan amount.
Borrowers purchasing distinctive properties should therefore avoid assuming that purchase price and appraised value will necessarily be identical.
Working With a Mortgage Broker for a Draper Jumbo Loan
Jumbo mortgage programs can vary substantially between lenders.
One lender may be more suitable for a particular property type, while another may be more appropriate for a borrower's income, assets, loan amount or financial profile.
Working with a mortgage broker can provide access to multiple potential lending sources rather than limiting the transaction to one institution's product menu.
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified borrowers seeking mortgage financing throughout Utah.
Through UtahLowRate.com, Daniel can help evaluate available jumbo financing based on the specific Draper transaction.
Local Draper Knowledge + Statewide Jumbo Resources
This page is intentionally focused on Draper, Utah.
For broader information covering Utah jumbo financing—including statewide requirements, conforming loan limits, general jumbo mortgage education and other Utah markets—visit our:
Jumbo Mortgage Utah | Utah Jumbo Home Loans guide.
Borrowers with substantially larger financing needs can also review our dedicated Super Jumbo Mortgage Loans Utah & California resource.
Self-employed borrowers using alternative income documentation can review our dedicated Jumbo Bank Statement Loans Utah resource.
Keeping these subjects on dedicated pages makes it easier to find detailed information without repeating the same jumbo mortgage content across every Utah city page.
Frequently Asked Questions About Jumbo Loans in Draper, UT
What is a jumbo loan in Draper, Utah?
A jumbo loan is generally a mortgage with a loan amount above the applicable conforming loan limit for the property. Qualified Draper buyers may use jumbo financing when purchasing higher-value homes requiring larger mortgage amounts.
Are jumbo loans only for luxury homes in Draper?
No. A mortgage is generally classified according to the loan amount and applicable loan limit rather than whether the property is marketed as a luxury home.
Can I get pre-approved for a Draper jumbo mortgage before finding a home?
Qualified borrowers can seek jumbo mortgage pre-approval before making an offer. Starting early can be useful because jumbo financing may require a more detailed review of income, assets, credit and reserves.
Can self-employed borrowers qualify for jumbo loans in Draper?
Potentially. Qualification depends on the lender and program. Traditional income documentation may work for some self-employed borrowers, while eligible borrowers may have alternative-documentation options through certain non-QM programs.
Are jumbo mortgage rates higher in Draper?
The property's Draper location alone does not determine the rate. Jumbo pricing can depend on the loan amount, credit, LTV, occupancy, property, mortgage structure, market conditions and other borrower-specific factors.
Can I refinance a jumbo mortgage on a Draper property?
Qualified homeowners may have jumbo refinancing options. Available programs depend on the existing mortgage, equity, property, borrower qualifications and current lender guidelines.
Where can I find complete Utah jumbo loan requirements?
Visit UtahLowRate.com Jumbo Mortgage Utah guide for broader statewide information about Utah jumbo loans, qualification considerations, loan limits and financing options.
Talk With Daniel Paris About a Draper Jumbo Mortgage
If you are purchasing or refinancing a higher-value property in Draper, Utah, your financing should be evaluated around the actual property and your financial profile.
Daniel Paris can help qualified borrowers compare potential jumbo mortgage options for Draper luxury homes, custom residences and other higher-value properties.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
801-604-4949
Buying or Refinancing in Draper?
Call 801-604-4949 to discuss your Draper jumbo mortgage scenario.
All mortgage programs are subject to lender/investor guidelines, borrower qualification, property eligibility, appraisal, credit, income and asset verification, underwriting approval and current program availability. Rates and terms are subject to change.

