
VA Funding Fee Utah 2026: Rates, Exemptions & Examples
The VA funding fee Utah 2026 borrowers may pay depends on the VA loan type, down payment, prior use of the VA home-loan benefit and whether the borrower qualifies for an exemption. For a first-use VA purchase loan with less than 5% down, the current funding fee is 2.15%. Some eligible Veterans, service members and surviving spouses do not have to pay the fee.
If you are buying or refinancing a home in Utah, understanding the VA funding fee can help you estimate your final loan amount and cash needed at closing.
New to VA financing? Start with our VA Mortgage Loans in Utah guide.
[Check My Utah VA Loan Options]
Daniel Paris
Utah Mortgage Broker
NMLS #243976
801-604-4949
UtahLowRate.com
Quick Answer: What Is the VA Funding Fee in Utah for 2026?
The VA funding fee in Utah is a one-time fee charged on many VA-backed home loans. Current VA purchase funding fees range from 1.25% to 3.30%, depending on the down payment and whether it is the borrower's first or subsequent use. The VA IRRRL funding fee is 0.50%. Qualified borrowers may be exempt.
VA Funding Fee Utah 2026: Key Facts
| VA Loan Scenario | Current Funding Fee |
|---|---|
| Purchase — first use, less than 5% down | 2.15% |
| Purchase — subsequent use, less than 5% down | 3.30% |
| Purchase — 5% or more down | 1.50% |
| Purchase — 10% or more down | 1.25% |
| Cash-out refinance — first use | 2.15% |
| Cash-out refinance — subsequent use | 3.30% |
| VA IRRRL | 0.50% |
| VA loan assumption | 0.50% |
| Manufactured home not permanently affixed | 1.00% |
These are the currently published VA funding-fee percentages. The funding fee applies to the applicable loan amount, not simply the home's purchase price.
For federal program details, see the U.S. Department of Veterans Affairs VA Funding Fee and Loan Closing Costs.
What Is the VA Funding Fee?
The VA funding fee is a one-time charge associated with many VA-backed and VA direct home loans.
The fee helps support the VA home-loan program.
Unlike many low-down-payment conventional mortgages, VA-backed home loans do not require monthly private mortgage insurance.
Not every VA borrower has to pay the funding fee. Certain eligible borrowers qualify for an exemption.
If you are still determining whether you qualify for VA financing, review VA Loan Requirements Utah before estimating your funding fee.
Who Pays the VA Funding Fee?
A funding fee may apply when an eligible borrower uses VA financing to:
- Purchase a home
- Build an eligible home
- Complete a VA cash-out refinance
- Refinance an existing VA mortgage with an IRRRL
- Assume certain VA loans
The percentage depends on the transaction.
For VA purchase loans, it can also depend on your down payment and whether you have previously used the VA home-loan benefit.
VA Funding Fee Utah 2026 Purchase Rates
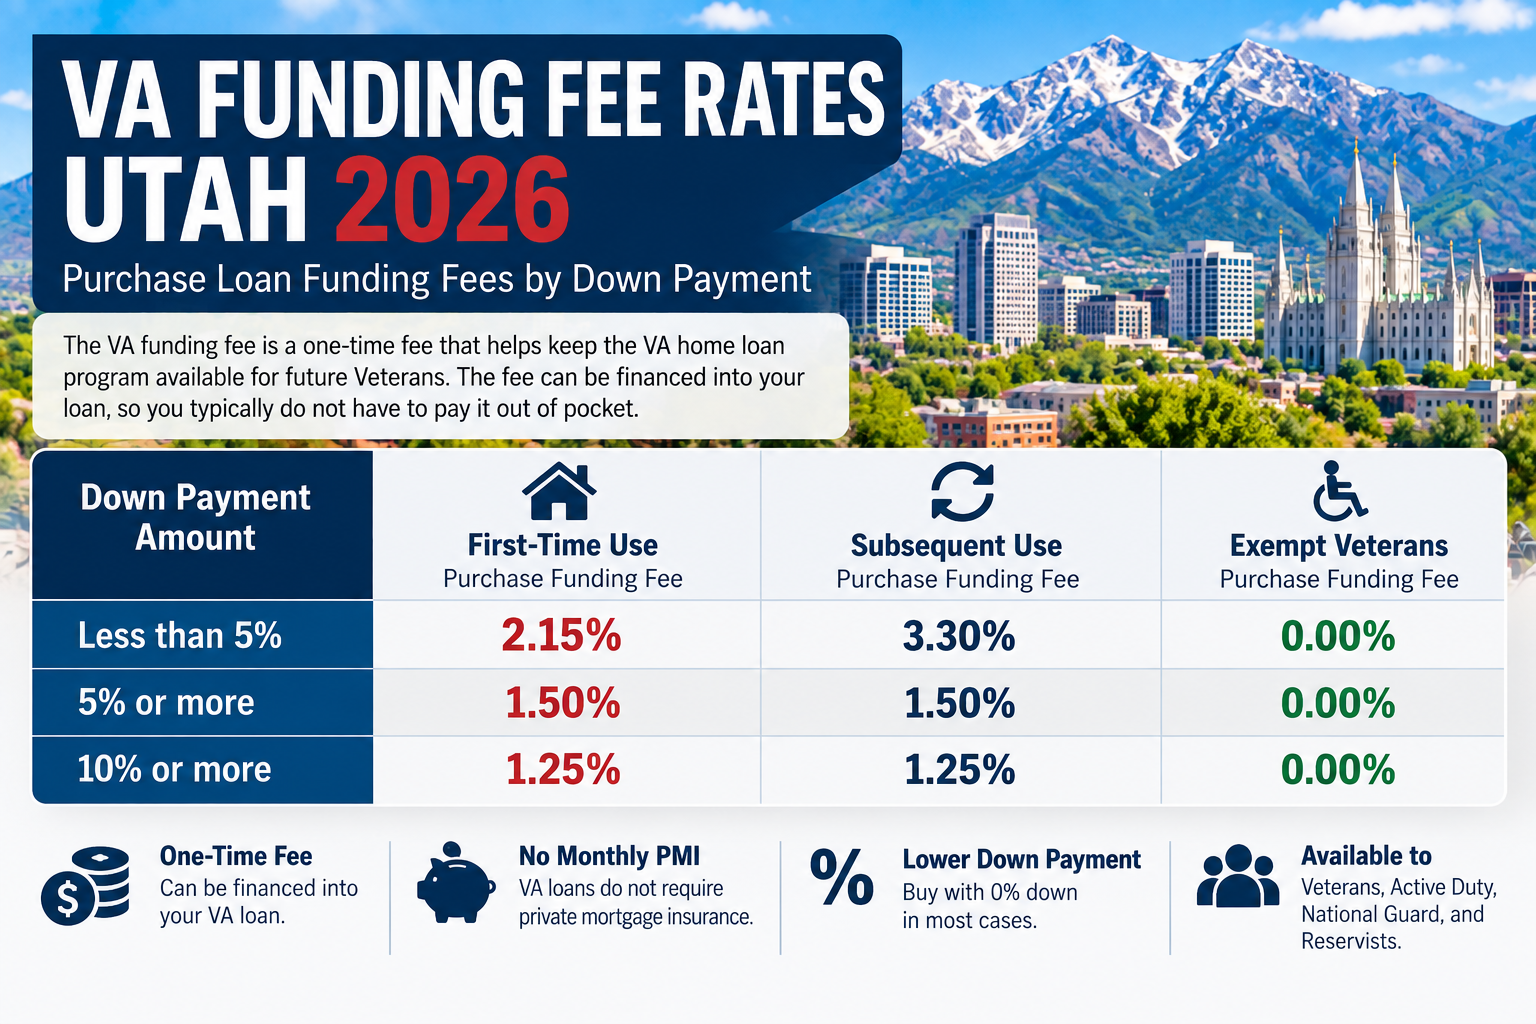
The current funding-fee schedule for VA purchase and construction loans is:
| Down Payment | First Use | Subsequent Use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% or more | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
Less Than 5% Down
A first-use VA borrower putting less than 5% down generally has a 2.15% funding fee.
For subsequent use with less than 5% down, the fee is generally 3.30%.
5% or More Down
With a qualifying down payment of at least 5%, the purchase funding fee falls to 1.50%.
10% or More Down
With a qualifying down payment of at least 10%, the purchase funding fee falls to 1.25%.
A larger down payment can therefore reduce both the base mortgage and the funding fee.
However, using more cash is not automatically the right choice. Compare the mortgage amount, payment, available reserves and total cash required before deciding.
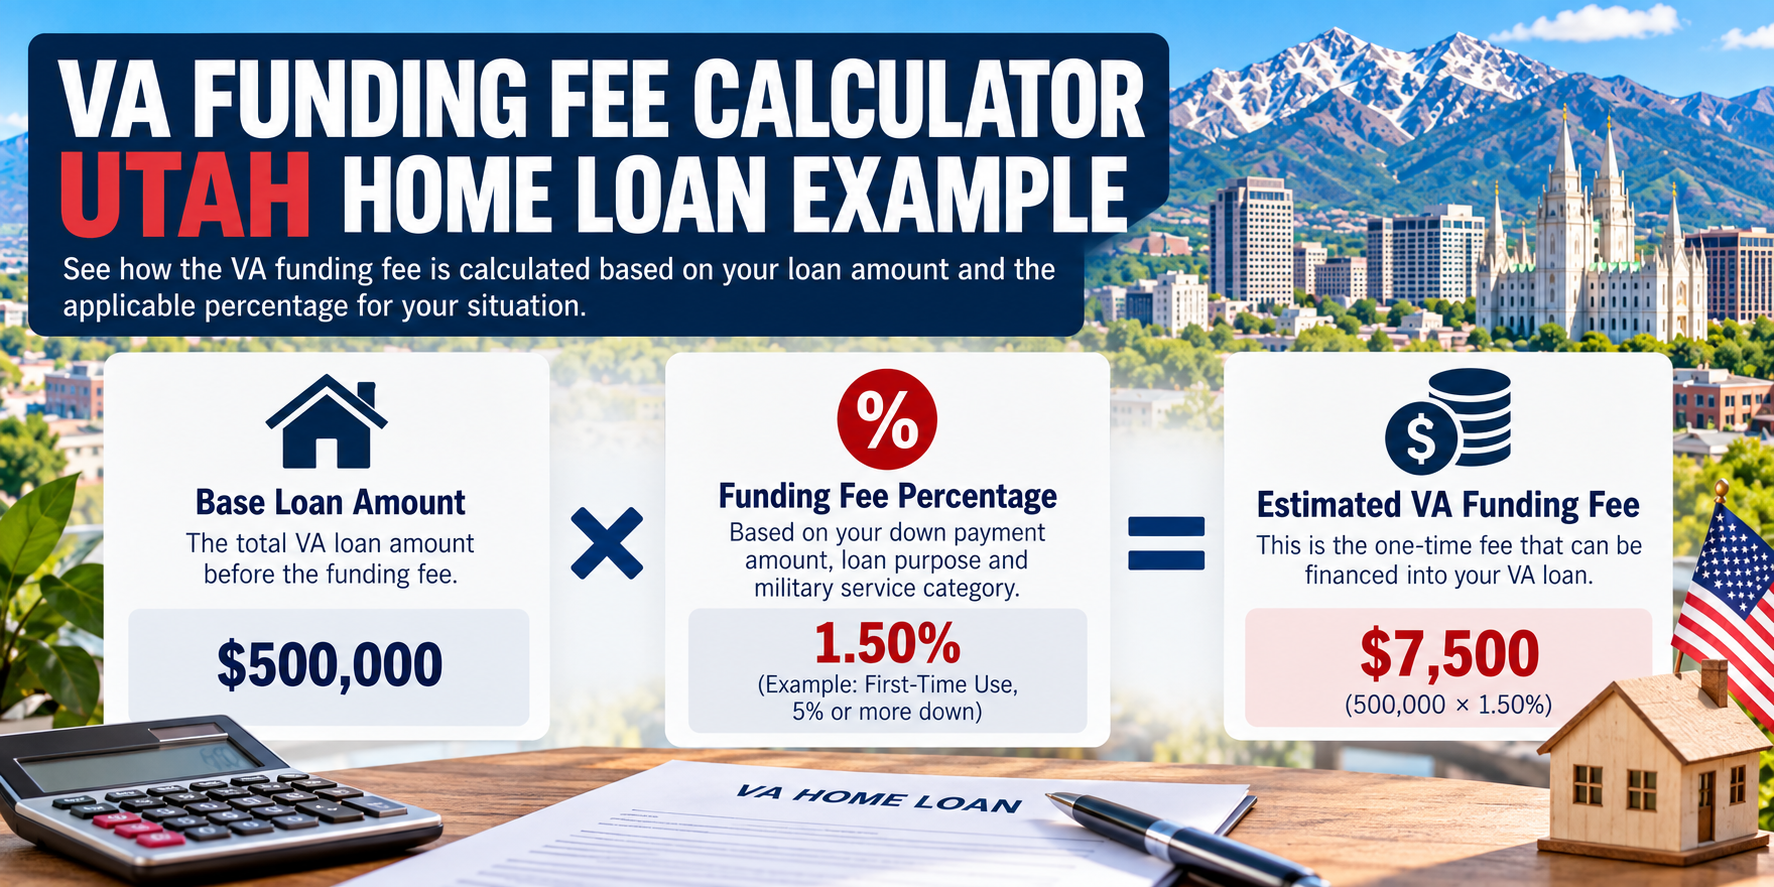
VA Funding Fee Calculator Utah: $500,000 Example
Suppose an eligible borrower buys a Utah home for $500,000 with no down payment and uses the VA home-loan benefit for the first time.
Purchase price: $500,000
Base VA loan: $500,000
Funding fee: 2.15%
$500,000 × 2.15% = $10,750
Estimated VA funding fee:
$10,750
If the entire fee is financed:
$500,000 + $10,750 = $510,750
Estimated starting loan amount:
$510,750
This example does not include interest, property taxes, homeowners insurance, HOA dues or other applicable closing costs.
For a more complete payment estimate, use the VA Loan Calculator Utah.
Subsequent-Use VA Funding Fee Example
Now assume the same $500,000 base loan, but the transaction qualifies as subsequent use and the borrower puts less than 5% down.
Base VA loan: $500,000
Funding fee: 3.30%
$500,000 × 3.30% = $16,500
Estimated funding fee:
$16,500
If financed:
$500,000 + $16,500 = $516,500
That difference makes it important to determine whether the transaction qualifies as first or subsequent use.
VA Funding Fee With 5% Down
Now consider a $500,000 Utah purchase with 5% down.
Purchase price: $500,000
Down payment: $25,000
Base VA loan: $475,000
Funding fee: 1.50%
$475,000 × 1.50% = $7,125
Estimated funding fee:
$7,125
If financed:
$475,000 + $7,125 = $482,125
The down payment reduces both the base mortgage and the funding-fee percentage.
VA Funding Fee With 10% Down
Using the same $500,000 purchase:
Purchase price: $500,000
Down payment: $50,000
Base VA loan: $450,000
Funding fee: 1.25%
$450,000 × 1.25% = $5,625
Estimated funding fee:
$5,625
If financed:
$450,000 + $5,625 = $455,625
Before making a larger down payment solely to reduce the funding fee, compare how much cash you would have left after closing.
VA Funding Fee Utah 2026 for Cash-Out Refinancing
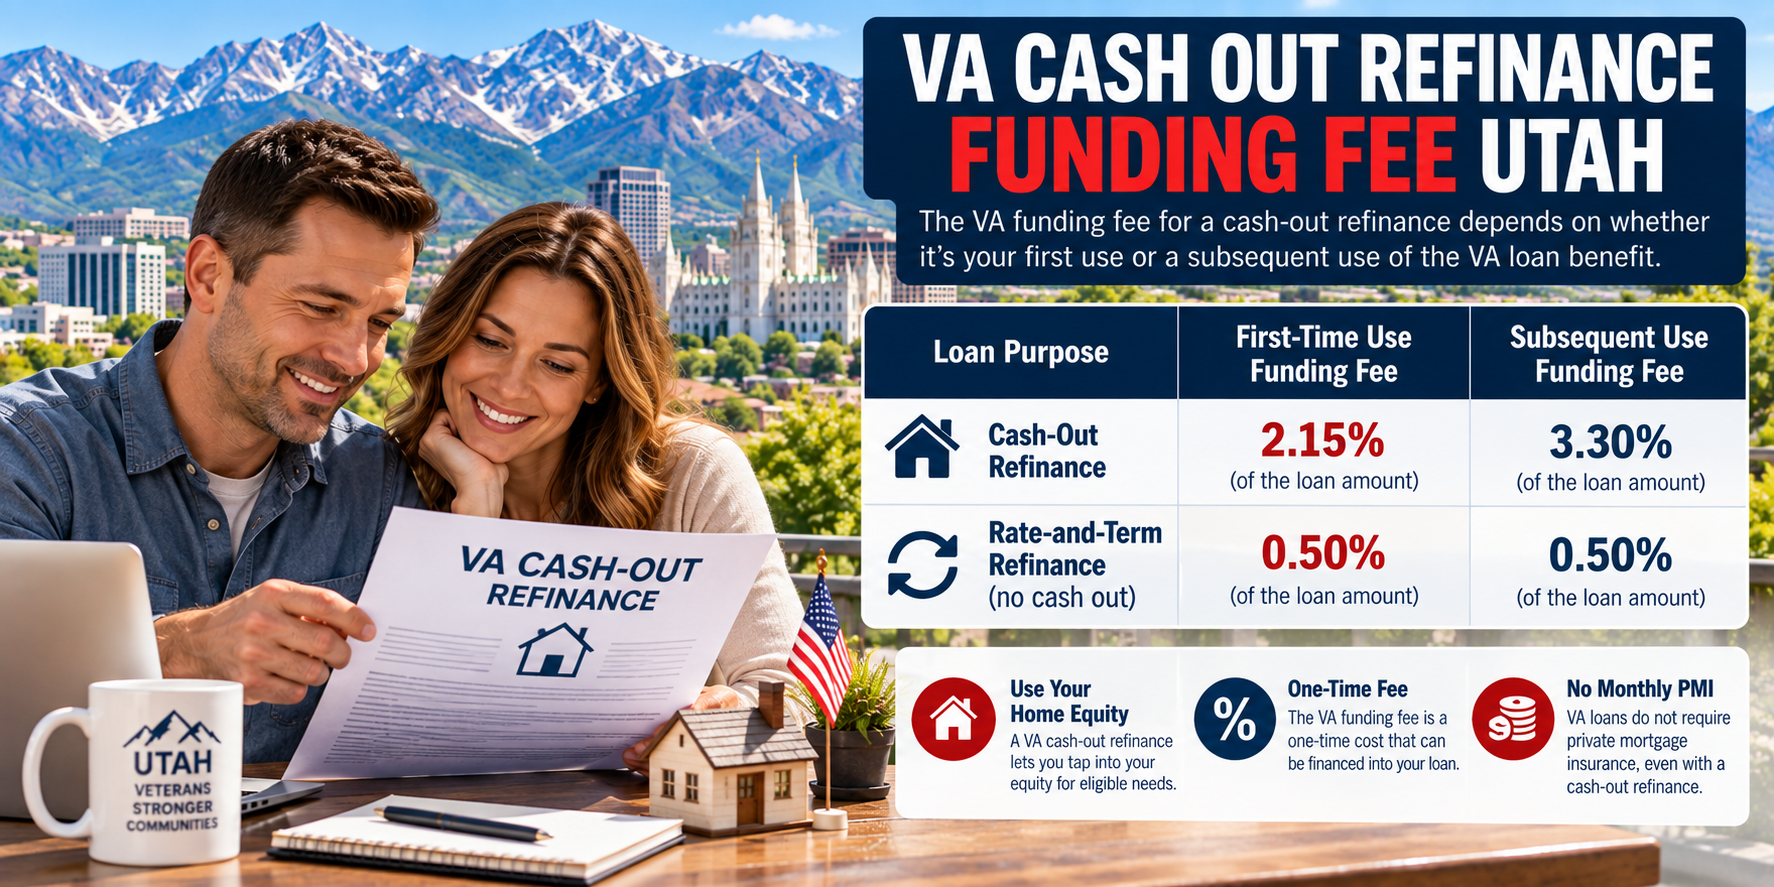
VA cash-out refinancing uses a different funding-fee structure.
| VA Cash-Out Refinance | Funding Fee |
|---|---|
| First use | 2.15% |
| Subsequent use | 3.30% |
The cash-out refinance funding-fee percentage does not decrease because the homeowner has more equity or makes a larger equity contribution.
A VA cash-out refinance may allow an eligible borrower to refinance an existing VA mortgage or certain non-VA mortgages, subject to VA and lender requirements.
See VA Refinance Utah for a complete explanation of VA refinance options.
VA IRRRL Funding Fee in Utah
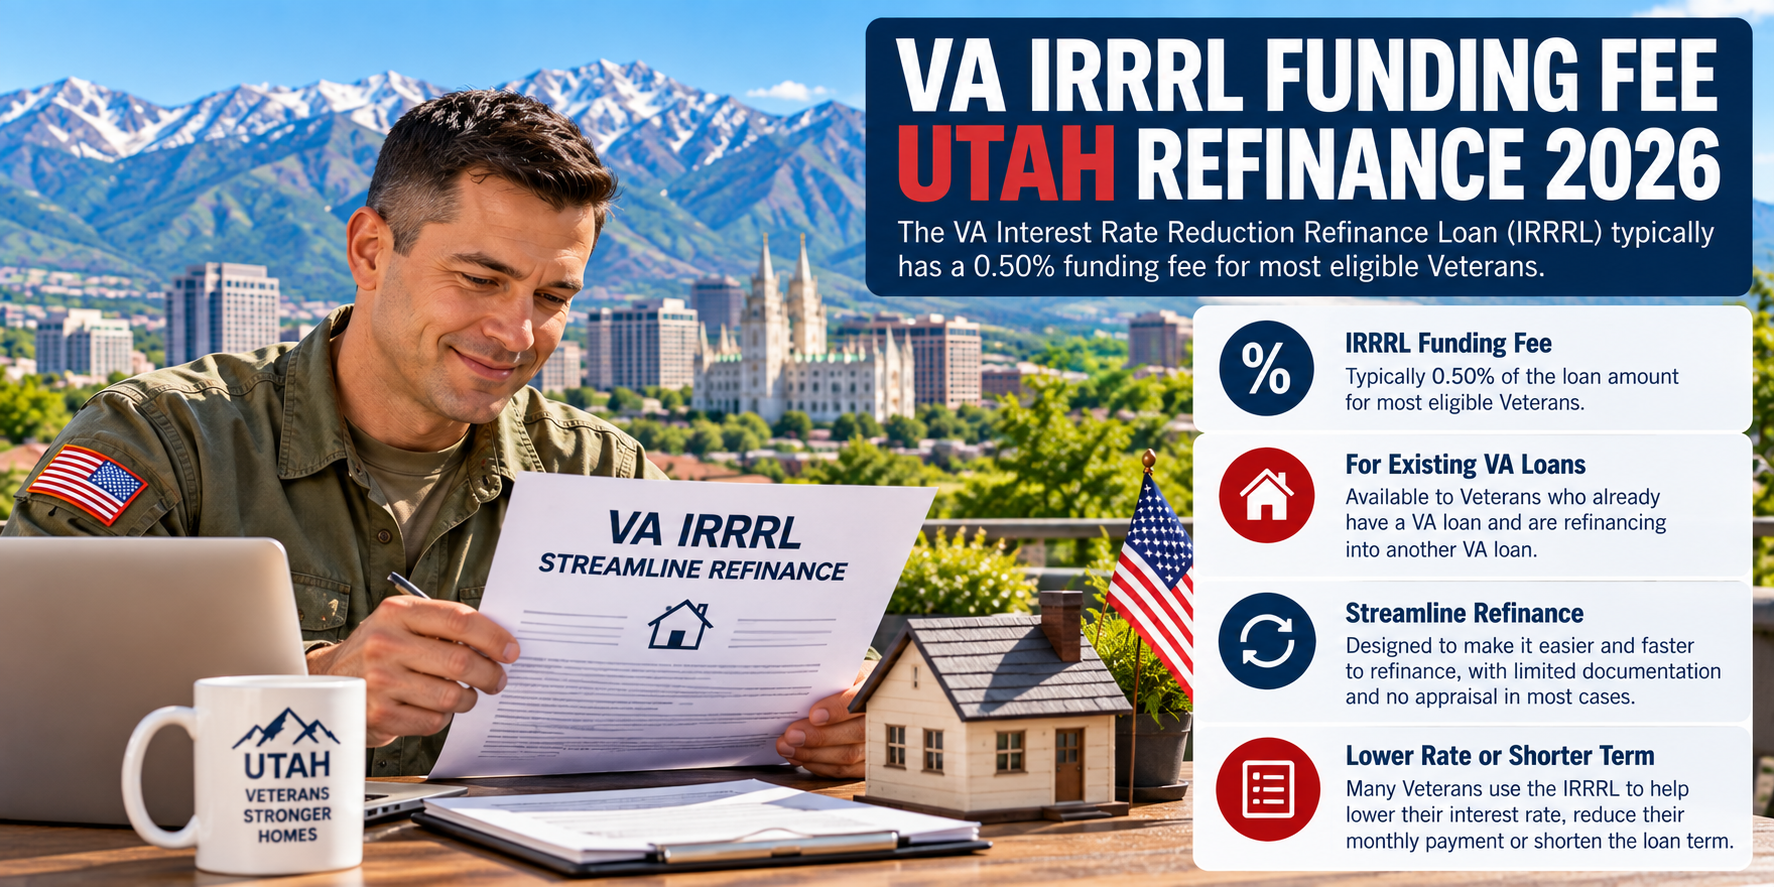
An Interest Rate Reduction Refinance Loan, commonly called a VA IRRRL or VA streamline refinance, currently carries a:
0.50% VA funding fee
For example, on a $400,000 applicable loan amount:
$400,000 × 0.50% = $2,000
Estimated funding fee:
$2,000
A borrower who qualifies for a funding-fee exemption may not owe the fee.
Learn more about streamline refinancing in VA IRRRL Utah.
If you are comparing refinance pricing, also review VA Mortgage Rates Utah.
VA Funding Fee Utah 2026 Exemptions
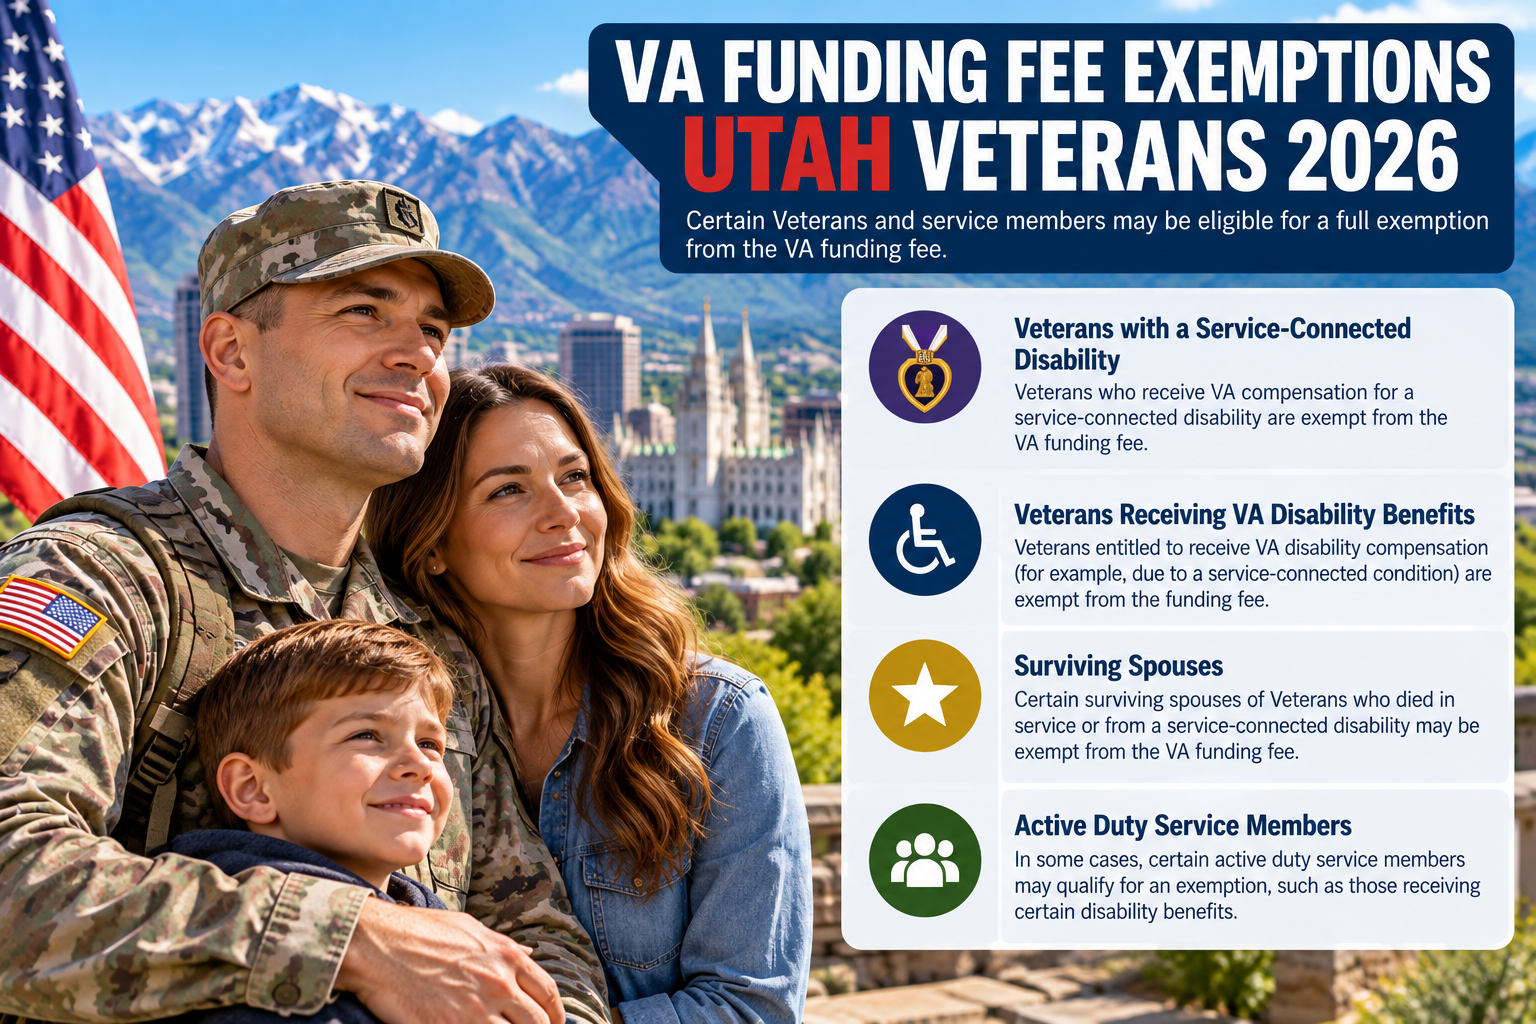
Not every eligible VA borrower pays the funding fee.
According to the Department of Veterans Affairs, an exemption may apply in certain situations, including qualifying borrowers who are:
- Receiving VA compensation for a service-connected disability
- Eligible to receive VA compensation for a service-connected disability but receiving retirement or active-duty pay instead
- Qualifying surviving spouses receiving Dependency and Indemnity Compensation
- Service members with a qualifying proposed or memorandum disability rating before closing based on a pre-discharge claim
- Active-duty members of the Armed Forces who provide qualifying evidence, on or before closing, of receiving a Purple Heart
Exemption status should be verified for the individual borrower.
Military service by itself does not automatically create a funding-fee exemption.
See the official VA funding-fee exemption requirements for current federal guidance.
How Do I Know Whether I Am Exempt?
Your VA loan documentation can be used to verify your funding-fee status.
Your mortgage professional or lender should determine whether the applicable VA records show you as:
Exempt
or
Non-exempt
If you believe your status is incorrect, address it before closing whenever possible.
For a broader explanation of eligibility, entitlement, the Certificate of Eligibility, credit, income and property qualification, see VA Loan Requirements Utah.
Can I Get a VA Funding Fee Refund?
Potentially.
A borrower may qualify for a funding-fee refund when VA later awards qualifying compensation for a service-connected disability and the effective date is retroactive to before the mortgage closing.
For example, a Veteran may close a VA mortgage while a qualifying disability claim is pending.
If VA later approves qualifying compensation with an effective date before the mortgage closing, the borrower may be eligible for a refund.
The actual determination is made under VA requirements.
Can the VA Funding Fee Be Financed?
Generally, yes.
An applicable funding fee can usually be:
- Paid in full at closing, or
- Financed into the VA mortgage.
Financing the fee reduces the upfront cash required for the fee.
However, it increases the mortgage balance.
When the fee is financed, the borrower generally pays interest on that additional balance while it remains outstanding.
Can Other VA Closing Costs Be Financed?
Do not confuse the funding fee with ordinary closing costs.
On a VA purchase or construction/permanent loan, the VA allows the funding fee to be financed into the mortgage.
Other purchase closing costs generally cannot simply be added to the VA loan amount in the same way.
Other costs can include:
- VA appraisal
- Title and settlement charges
- Recording charges
- Prepaid interest
- Property-tax escrows
- Homeowners insurance
- Discount points
- Permitted lender charges
Review your Loan Estimate carefully before closing.
Can the Seller Pay the VA Funding Fee?
VA rules permit sellers and builders to provide credits toward certain buyer costs.
The VA also treats some seller-paid items as seller concessions. Seller concessions are subject to separate limits and requirements.
The VA currently states that seller concessions can include payment of the buyer's VA funding fee.
Do not assume every proposed seller credit will automatically be permitted. The purchase contract and final loan structure should be reviewed for compliance.
VA Funding Fee vs. PMI
The VA funding fee and private mortgage insurance are different.
| Feature | VA Funding Fee | Conventional PMI |
|---|---|---|
| Typical structure | One-time charge | Often monthly |
| Applies to every borrower | No | No |
| VA exemptions | Available to qualifying borrowers | Not applicable |
| Can generally be financed | Yes | Depends on structure |
| Monthly PMI required on VA loan | No | Not applicable |
VA-backed mortgages do not require monthly private mortgage insurance.
That can make the funding fee an important part of a broader VA-versus-conventional comparison rather than something that should be considered by itself.
For the complete VA program overview, visit VA Mortgage Loans in Utah.
Should I Put Money Down to Reduce My VA Funding Fee?
There is no one answer for every borrower.
Compare:
- Funding-fee savings
- Down payment required
- Final loan amount
- Monthly payment
- Available cash after closing
- Emergency reserves
- Interest rate
- Other debts
- Expected time in the home
For one borrower, preserving $25,000 or $50,000 in reserves may be important.
Another borrower may prefer a smaller mortgage and lower funding fee.
Ask for zero-down, 5%-down and 10%-down comparisons before choosing a structure.
VA Funding Fee for Higher-Balance Utah Homes
The funding-fee percentage becomes a larger dollar amount as the mortgage increases.
For example:
$1,000,000 × 2.15% = $21,500
For applicable subsequent use below 5% down:
$1,000,000 × 3.30% = $33,000
For qualified VA borrowers considering higher-value homes in areas such as Park City, Deer Valley, Salt Lake City or Draper, it can be especially useful to determine exemption status before comparing loan structures.
Review your overall eligibility and entitlement through VA Mortgage Loans in Utah.
Is the VA Funding Fee Different Across Utah?
No.
The applicable funding-fee percentage is established under the federal VA home-loan program. The percentage does not change merely because a qualifying property is located in Salt Lake City instead of St. George.
VA financing may be available for eligible properties and borrowers throughout Utah, including:
- Salt Lake City
- Murray
- Sandy
- Draper
- South Jordan
- West Jordan
- Herriman
- Layton
- Ogden
- Provo
- Orem
- Lehi
- Park City
- Heber City
- St. George
Other expenses can vary by property and location, including property taxes, homeowners insurance, title charges and HOA dues.
For Salt Lake-area borrowers, see VA Loans Salt Lake City Utah.
How to Calculate Your VA Funding Fee
Use this basic formula:
Base VA Loan Amount × Funding-Fee Percentage = VA Funding Fee
Example:
$600,000 × 2.15% = $12,900
If the fee is financed:
$600,000 + $12,900 = $612,900
The funding fee is only one part of the total mortgage calculation.
Use the VA Loan Calculator Utah to estimate your mortgage payment and compare scenarios.
VA Funding Fee Utah 2026: Common Mistakes
Assuming Every Veteran Is Exempt
Military service alone does not automatically eliminate the funding fee. Verify your exemption status.
Using the First-Use Rate for Subsequent Use
For a purchase with less than 5% down, the difference between 2.15% and 3.30% can be significant.
Calculating the Fee From the Purchase Price
The funding fee applies to the applicable loan amount.
Forgetting the Fee When Estimating Your Mortgage
Financing the funding fee increases your final mortgage balance.
Confusing the Funding Fee With PMI
VA-backed mortgages do not require monthly PMI.
Ignoring a Potential Refund
A qualifying retroactive VA disability-compensation determination may make some borrowers eligible for a refund.
VA Funding Fee Utah 2026 FAQ
What is the VA funding fee in Utah for 2026?
For an applicable VA purchase loan with less than 5% down, the current funding fee is 2.15% for first use and 3.30% for subsequent use. At least 5% down reduces the purchase funding fee to 1.50%. At least 10% down reduces it to 1.25%.
What is the VA funding fee with zero down?
For a VA purchase transaction with less than 5% down, including zero down, the current applicable rate is 2.15% for first use and 3.30% for subsequent use.
What is the VA funding fee with 5% down?
The current purchase funding fee is 1.50% when the qualifying down payment is at least 5% but less than 10%.
What is the VA funding fee with 10% down?
The current purchase funding fee is 1.25% when the qualifying down payment is at least 10%.
What is the VA IRRRL funding fee?
The current VA IRRRL funding fee is 0.50%, unless the borrower qualifies for an exemption.
What is the VA cash-out refinance funding fee?
The current VA cash-out funding fee is 2.15% for first use and 3.30% for subsequent use.
Who is exempt from the VA funding fee?
Certain borrowers may qualify for an exemption, including certain Veterans receiving or entitled to receive qualifying VA disability compensation, certain eligible surviving spouses and other borrowers who meet specific VA exemption requirements.
Can I finance the VA funding fee?
Generally, yes. An applicable funding fee can usually be financed into the VA mortgage or paid in full at closing.
Do VA loans have monthly PMI?
No. VA-backed home loans do not require monthly private mortgage insurance.
Can I receive a VA funding fee refund?
Potentially. A refund may be available when VA later awards qualifying service-connected disability compensation with an effective date that predates the mortgage closing.
Is the VA funding fee different in Salt Lake City, Park City or St. George?
No. The applicable funding-fee percentage is established under the federal VA program rather than by Utah city or county.
Explore the Utah VA Loan Resource Center
This funding-fee guide is part of the UtahLowRate.com VA mortgage resource cluster.
VA Mortgage Loans in Utah
Start with the VA Mortgage Loans in Utah pillar guide for eligibility, entitlement, purchases, refinancing, funding fees and VA loan options.
VA Loan Requirements Utah
Review eligibility, COE, credit, income, residual income, occupancy and property requirements in VA Loan Requirements Utah.
VA Loan Calculator Utah
Estimate the payment and effect of financing your funding fee with the VA Loan Calculator Utah.
VA Mortgage Rates Utah
Compare rate, APR, points and other pricing considerations on VA Mortgage Rates Utah.
VA Loan FAQ Utah
Find answers about entitlement, eligibility, funding fees, refinancing and VA property requirements in VA Loan FAQ Utah.
VA Loans Salt Lake City Utah
Buying in Salt Lake City or Salt Lake County? Visit VA Loans Salt Lake City Utah.
Get Your Utah VA Funding Fee and Loan Estimate
The published funding-fee percentage is only one part of a VA mortgage.
Your actual financing should be reviewed using your:
- Purchase price
- Property value
- Proposed loan amount
- Down payment
- First or subsequent use
- VA eligibility
- Certificate of Eligibility
- Funding-fee exemption status
- Credit and income
- Current mortgage when refinancing
Discuss Your Utah VA Mortgage Options
Daniel Paris
Utah Mortgage Broker
NMLS #243976
801-604-4949
UtahLowRate.com
[Check My VA Loan Options]
All mortgage programs are subject to borrower eligibility, VA requirements, lender underwriting, property eligibility, appraisal requirements and current program availability. Examples are educational and do not constitute an approval, commitment to lend or rate quote.

