
2026–2027 Expanded Conventional Loan Limits Utah
Last Updated: September 24, 2026
By Daniel Paris | Utah Mortgage Broker | UtahLowRate.com | NMLS #243976-3138 | More than 27 years of mortgage lending experience
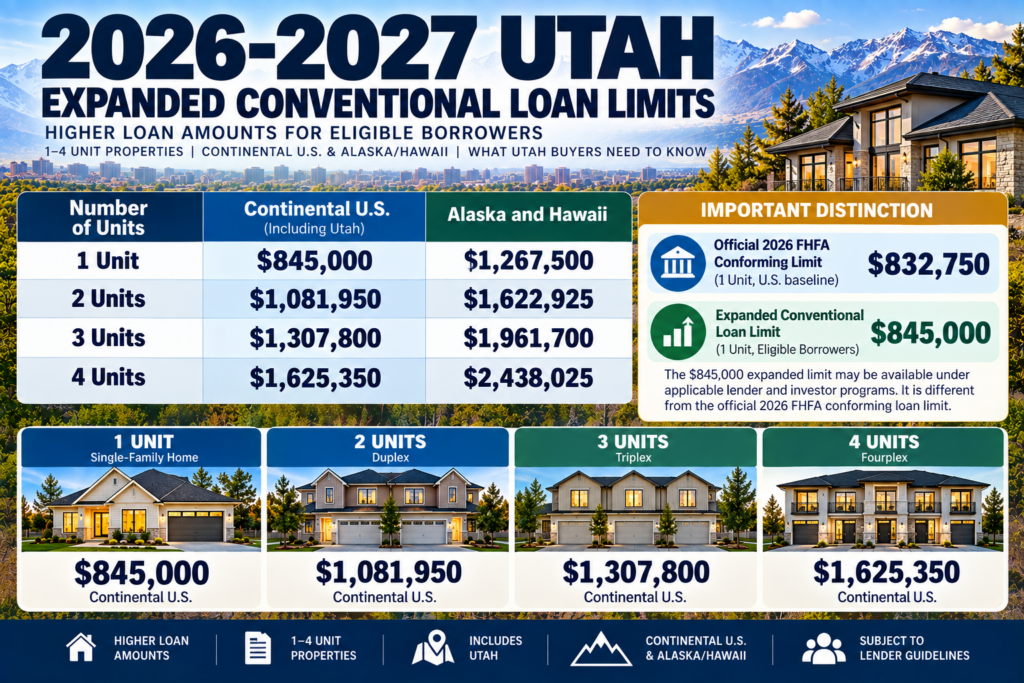
Utah homebuyers may have access to 2026–2027 expanded conventional loan limits, including an expanded loan amount of up to $845,000 for an eligible one-unit property under applicable lender and investor programs.
These expanded amounts should not be confused with the official FHFA conforming loan limits. For calendar year 2026, the official baseline FHFA conforming loan limit for a one-unit property in most of the United States is $832,750.
That distinction matters. An expanded lender or investor limit may allow an eligible borrower to obtain conventional financing above the standard conforming threshold, but availability depends on the specific program, underwriting guidelines and applicable effective dates.
2026–2027 Expanded Conventional Loan Limits at a Glance
The following expanded conventional loan amounts may be available under applicable lender or investor guidelines:
| Number of Units | Continental U.S. | Alaska & Hawaii |
|---|---|---|
| 1 Unit | $845,000 | $1,267,500 |
| 2 Units | $1,081,950 | $1,622,925 |
| 3 Units | $1,307,800 | $1,961,700 |
| 4 Units | $1,625,350 | $2,438,025 |
For Utah borrowers, the figure likely to receive the most attention is the $845,000 expanded limit for an eligible one-unit property.
The expanded amount represents the maximum potential loan amount under an applicable program—not the purchase price of the property and not a guarantee that every borrower will qualify.
Is $845,000 the Official 2026 FHFA Conforming Loan Limit?
No. The official 2026 FHFA baseline conforming loan limit for a one-unit property in most of the United States is $832,750.
FHFA announced the 2026 limit on November 25, 2025. Fannie Mae and Freddie Mac subsequently incorporated the $832,750 baseline limit into their 2026 guidelines.
That means borrowers should distinguish between two different numbers:
Official 2026 FHFA baseline limit: $832,750 for a one-unit property in most U.S. counties.
Expanded lender/investor amount: up to $845,000 for a one-unit property under the applicable expanded program.
This distinction is particularly important when comparing conventional and jumbo financing because a mortgage above the applicable conforming limit would ordinarily fall outside standard agency conforming limits.
How Can a $845,000 Conventional Loan Work in Utah?
An $845,000 expanded conventional loan in Utah may be possible when the selected lender or investor permits the higher amount and the loan satisfies that program’s requirements.
For example, consider a Utah homebuyer who needs an $840,000 mortgage.
Under the official 2026 baseline FHFA limit of $832,750, that loan amount exceeds the standard baseline by $7,250. Depending on the property’s county and applicable loan limit, the borrower might ordinarily need a high-balance or jumbo solution.
An expanded program accepting conventional loan amounts up to $845,000 could potentially provide another financing option.
This can be relevant in higher-priced Utah housing markets such as Salt Lake City, Murray, Holladay, Cottonwood Heights, Draper, Alpine, Park City, Heber City and other Wasatch Front communities.
What Are the Requirements for Expanded Conventional Loan Limits?
Access to an expanded conventional loan limit is not automatic. Borrower, property, transaction and lender requirements still determine eligibility.
Important underwriting factors may include:
- Credit score and credit history
- Desktop Underwriter or Loan Product Advisor findings
- Debt-to-income ratio
- Loan-to-value ratio
- Down payment or available equity
- Employment and qualifying income
- Assets and required reserves
- Primary residence, second-home or investment-property occupancy
- Single-family versus 2–4 unit property type
- Appraised property value
- Fannie Mae or Freddie Mac eligibility
- Lender and investor overlays
- Applicable origination, closing, settlement or delivery dates
A higher maximum loan amount does not relax the underlying underwriting requirements. Borrowers still have to qualify for the requested mortgage.
Official FHFA Limits vs. Expanded Conventional Limits
The FHFA conforming loan limit determines the statutory maximum size of mortgages Fannie Mae and Freddie Mac can acquire, subject to applicable county and high-cost-area rules.
For 2026, the official baseline amounts are:
| Units | Official 2026 Baseline Limit |
|---|---|
| 1 | $832,750 |
| 2 | $1,066,250 |
| 3 | $1,288,800 |
| 4 | $1,601,750 |
The expanded amounts supplied for applicable programs are:
| Units | Expanded Amount |
|---|---|
| 1 | $845,000 |
| 2 | $1,081,950 |
| 3 | $1,307,800 |
| 4 | $1,625,350 |
The difference for a one-unit property is $12,250.
That relatively small gap can still matter to a borrower purchasing a home near the standard conforming threshold.
Conventional vs. Jumbo Loan in Utah
A Utah mortgage does not automatically become a jumbo loan based solely on the home’s purchase price. The relevant consideration is the mortgage amount compared with the conforming loan limit applicable to the property’s location and number of units.
A $1 million Utah home, for example, does not necessarily require a $1 million mortgage. A borrower making a sufficiently large down payment could still have a loan balance within the applicable conventional limit.
When the required mortgage exceeds the applicable conforming or expanded program limit, a Utah jumbo mortgage may provide another option.
UtahLowRate.com works with conventional as well as jumbo and super-jumbo lending sources, allowing qualified borrowers to compare financing structures rather than assuming one program is automatically the best fit.
Why Loan Limits Matter in Utah
Loan limits can have a meaningful impact in Utah markets where home prices make larger mortgages common.
Salt Lake County communities such as Salt Lake City, Murray, Holladay, Sandy and Draper can produce transactions close to or above standard conforming thresholds. Higher-value homes are also common in Park City, Deer Valley, Summit County and Wasatch County.
The applicable county loan limit matters as well. FHFA provides higher limits in designated high-cost areas, so borrowers should not assume that the nationwide baseline is the maximum available for every Utah property.
The property address, county, number of units and applicable year’s limits should therefore be checked before determining whether conventional, high-balance or jumbo financing applies.
When Should Utah Buyers Compare Expanded Conventional and Jumbo Loans?
Borrowers whose desired loan amount falls close to the conforming threshold should compare available structures before selecting a program.
An expanded conventional option could potentially keep a qualifying mortgage within a conventional program. A jumbo mortgage, however, may have different pricing, reserve requirements, credit guidelines, debt-to-income limits and underwriting options.
The right comparison should consider more than the maximum loan amount. Interest rate, APR, points, lender fees, mortgage insurance, down payment, reserves and total borrowing cost all matter.
Daniel Paris at UtahLowRate.com helps Utah homebuyers and homeowners compare conventional, expanded conventional, jumbo and other mortgage options based on the actual property and borrower scenario.
Frequently Asked Questions About 2026–2027 Expanded Conventional Loan Limits
What is the expanded conventional loan limit for a one-unit property?
The expanded amount provided for an eligible one-unit property in the Continental U.S. is $845,000, subject to applicable lender and investor requirements.
Is $845,000 the official FHFA conforming loan limit for 2026?
No. FHFA’s official 2026 baseline conforming loan limit for a one-unit property in most of the United States is $832,750. The $845,000 figure should be treated separately as an expanded lender or investor amount unless official agency guidance establishes otherwise.
Can I get an $845,000 conventional mortgage in Utah?
Potentially. An eligible Utah borrower may be able to obtain an $845,000 conventional mortgage when a participating lender or investor accepts the expanded amount and the borrower, property and transaction satisfy all applicable underwriting requirements.
Does a loan over $832,750 automatically require a jumbo mortgage in Utah?
Not necessarily. Utah has county-specific conforming limits, including higher limits in certain high-cost areas, and some lenders or investors may offer expanded programs. The property location and applicable program should be checked before classifying the mortgage.
Do expanded loan limits mean I automatically qualify for a larger mortgage?
No. A higher loan limit establishes a potential maximum loan size but does not determine borrower qualification. Credit, income, debts, assets, LTV, occupancy, property eligibility and underwriting requirements still apply.
Should I compare conventional and jumbo loans if I am near the loan limit?
Yes. Comparing both structures can show differences in rates, APR, down payment, reserves, mortgage insurance, fees and underwriting requirements before you choose a financing strategy.
Talk With a Utah Mortgage Broker
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976-3138
More than 27 years of mortgage lending experience
Phone: 801-604-4949
Serving borrowers throughout Utah
If your mortgage amount is close to the conventional loan limit, UtahLowRate.com can help you compare standard conventional, expanded conventional and Utah jumbo mortgage options.
You can also explore Utah mortgage loan programs to compare financing options based on your credit, income, property, down payment and loan amount.
Important: Mortgage programs, loan limits, eligibility requirements and investor guidelines can change. Expanded loan limits described above are subject to the specific lender or investor program and should not be represented as official FHFA limits unless confirmed by the applicable agency.

