
Buy & Renovate With One Mortgage
If you are buying or refinancing a home in Murray, Utah that needs repairs or improvements, an FHA 203k loan in Murray, Utah may let you combine the mortgage and eligible renovation costs into one FHA-insured loan.
Instead of purchasing a property first and finding separate financing for repairs later, qualified borrowers can use FHA 203(k) financing to address eligible improvements as part of the mortgage transaction.
At Utah Low Rate, Daniel Paris helps Utah homebuyers and homeowners compare FHA financing, renovation loans and other mortgage options based on the property, renovation plans and borrower qualifications.
Have a Murray property that needs work? Call 801-604-4949 or request a mortgage quote to discuss the property and proposed renovations.
Quick Answer: What Is an FHA 203k Loan?
An FHA 203k loan is an FHA-insured renovation mortgage that can finance the purchase or refinance of an eligible property along with qualifying repair and improvement costs.
There are two primary versions: Limited 203(k) for eligible nonstructural projects and Standard 203(k) for larger renovations, including structural work.
For a Murray property, the applicable FHA mortgage limit is based on Salt Lake County and the number of residential units.
FHA 203k Loan Key Facts
- Available for eligible home purchases and refinances.
- Combines the mortgage and eligible renovation expenses.
- FHA offers Limited and Standard 203(k) options.
- Limited 203(k) rehabilitation costs can currently be as high as $75,000, subject to FHA requirements.
- Standard 203(k) is intended for major rehabilitation and structural projects.
- Standard 203(k) requires at least $5,000 of rehabilitation work.
- A 203(k) consultant is required for Standard 203(k).
- The home generally must be owner-occupied under FHA occupancy requirements.
- FHA mortgage insurance applies.
- FHA county loan limits still apply.
- Contractor documentation, bids and renovation plans can be important parts of the approval process.
How Does an FHA 203k Loan Work in Murray, Utah?
An FHA 203k mortgage is different from a standard FHA purchase loan because the lender evaluates both the mortgage borrower and the proposed rehabilitation project.
A typical transaction may involve:
- Finding an eligible Murray-area property.
- Reviewing your FHA mortgage qualifications.
- Identifying the repairs or improvements needed.
- Obtaining appropriate contractor estimates and project documentation.
- Completing the FHA-required appraisal and renovation review.
- Underwriting the mortgage and rehabilitation portion of the transaction.
- Closing the mortgage.
- Holding applicable rehabilitation funds in an escrow account.
- Completing approved work and releasing funds according to program requirements.
Because renovation financing involves additional documentation, discussing the project with an experienced mortgage professional early can help identify potential financing issues before you are deep into the purchase.
Limited vs. Standard FHA 203k Loans
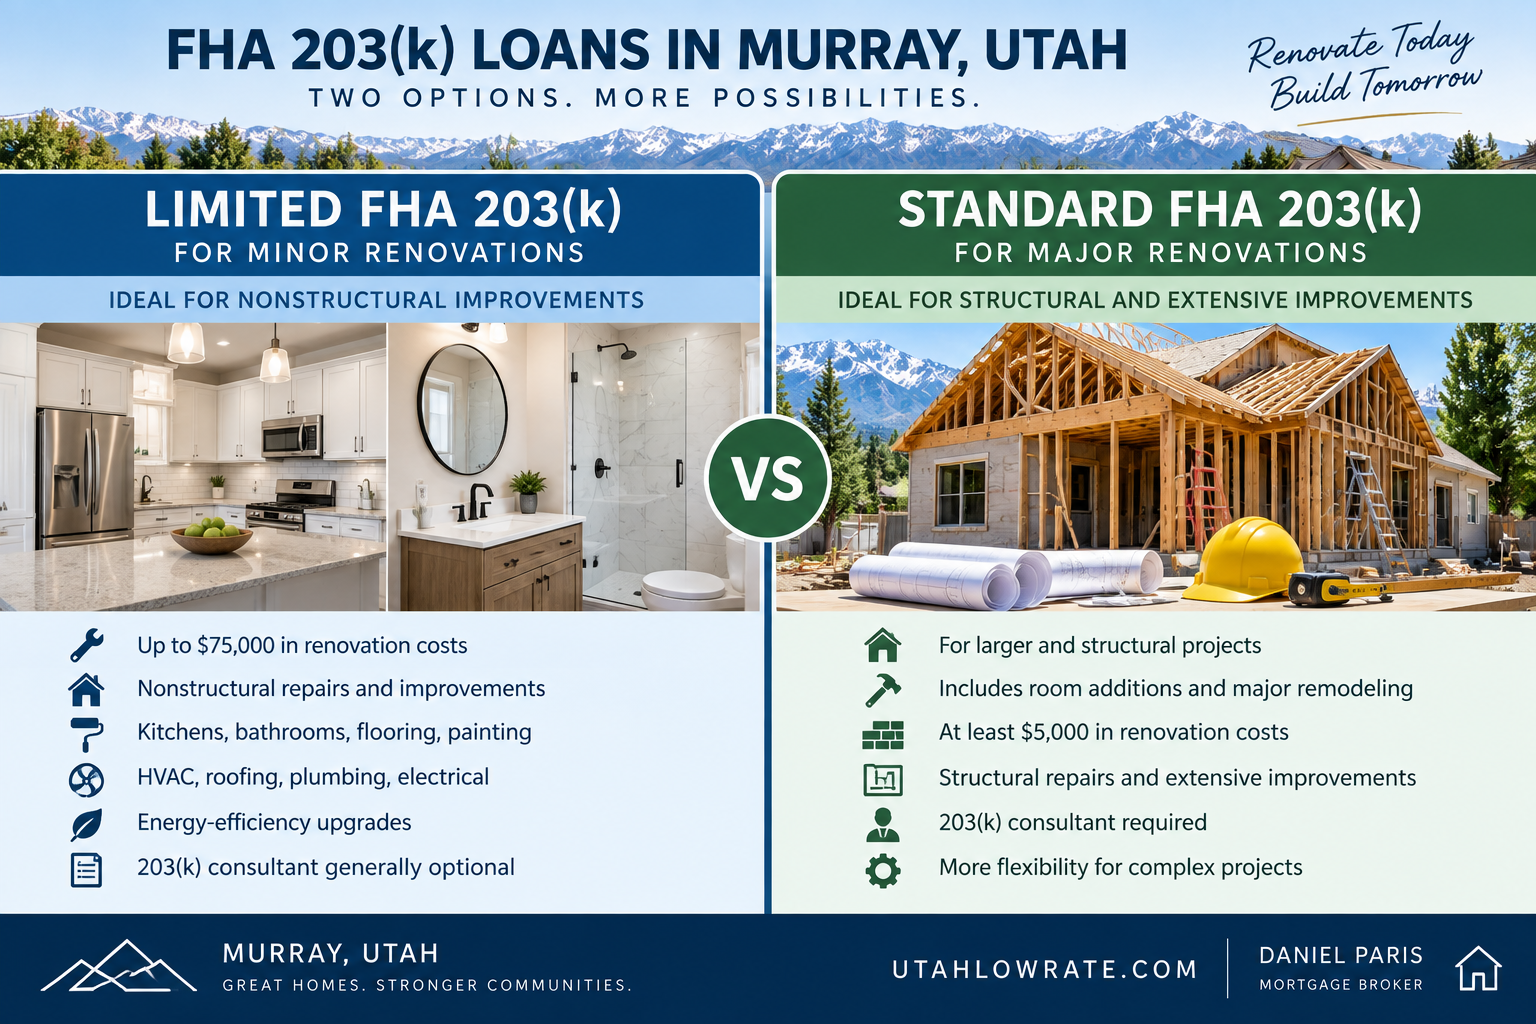
Limited FHA 203k
A Limited FHA 203k loan is designed primarily for eligible minor remodeling and nonstructural improvements.
Current FHA guidelines permit up to $75,000 in total rehabilitation costs under the Limited 203(k), subject to program requirements.
Possible projects may include:
- Interior painting
- Flooring
- Kitchen updates
- Bathroom improvements
- Certain roofing work
- HVAC improvements
- Plumbing or electrical repairs
- Energy-efficiency improvements
- Other eligible nonstructural repairs
A 203(k) consultant is generally optional for a Limited 203(k).
Standard FHA 203k
A Standard FHA 203k loan is intended for more extensive rehabilitation and can accommodate structural improvements that are not permitted under the Limited program.
Standard 203(k) rehabilitation costs must generally total at least $5,000.
Potential projects may include:
- Structural alterations
- Major remodeling
- Room additions
- Significant rehabilitation
- Major systems replacement
- Extensive property repairs
- Eligible improvements requiring architectural or engineering work
The Standard program generally requires an FHA-approved 203(k) consultant.
Which program makes sense depends on the scope and cost of your proposed improvements.
What Repairs Can an FHA 203k Loan Cover?
Eligible work depends on whether you use a Limited or Standard 203(k).
Depending on FHA requirements and the individual project, financing may potentially be used for improvements such as:
- Roof repairs or replacement
- Heating and cooling systems
- Plumbing
- Electrical systems
- Kitchen remodeling
- Bathroom remodeling
- Flooring
- Painting
- Accessibility improvements
- Energy-efficiency improvements
- Structural repairs under Standard 203(k)
- Eligible additions or alterations under Standard 203(k)
Not every renovation qualifies. Have the proposed scope of work reviewed before assuming a particular improvement can be financed.
For official program information, review the HUD 203(k) Rehabilitation Mortgage Insurance Program.
FHA 203k Loan Requirements in Murray, Utah
Borrowers must satisfy FHA underwriting requirements as well as 203(k)-specific requirements.
Important factors can include:
Credit
FHA guidelines may permit financing with credit scores lower than those commonly required for many conventional mortgage programs. However, lender requirements can be more restrictive than FHA's minimum standards.
Your credit profile can also affect your rate and available financing options.
Income and Employment
Borrowers must document sufficient qualifying income and demonstrate the ability to repay the mortgage.
Documentation varies based on how you earn income.
W-2 employees, self-employed borrowers, commission earners and other borrowers can have different documentation requirements.
Debt-to-Income Ratio
Your existing monthly obligations and proposed housing payment are considered when determining qualification.
There is not one debt-to-income ratio that guarantees approval. Automated underwriting, credit history, reserves and other factors may affect the result.
Owner Occupancy
FHA financing is generally intended for a borrower's principal residence rather than a traditional investment property.
FHA Mortgage Insurance
FHA 203(k) loans generally include FHA mortgage insurance. Compare the complete payment and financing costs rather than evaluating a loan only by its interest rate.
Learn more about FHA loans in Utah.
2026 FHA Loan Limit for Murray and Salt Lake County
Murray is located in Salt Lake County, so Salt Lake County FHA mortgage limits apply.
For 2026, the FHA limits for Salt Lake County are:
| Property | 2026 FHA Limit |
|---|---|
| 1 unit | $637,100 |
| 2 units | $815,600 |
| 3 units | $985,900 |
| 4 units | $1,225,200 |
The applicable FHA mortgage limit is not necessarily the same as the property's purchase price or total project budget.
Because FHA limits change, verify the current county limit before structuring a transaction.
See the complete 2026 FHA loan limits for Utah.
Can I Buy a Fixer-Upper in Murray with an FHA 203k Loan?
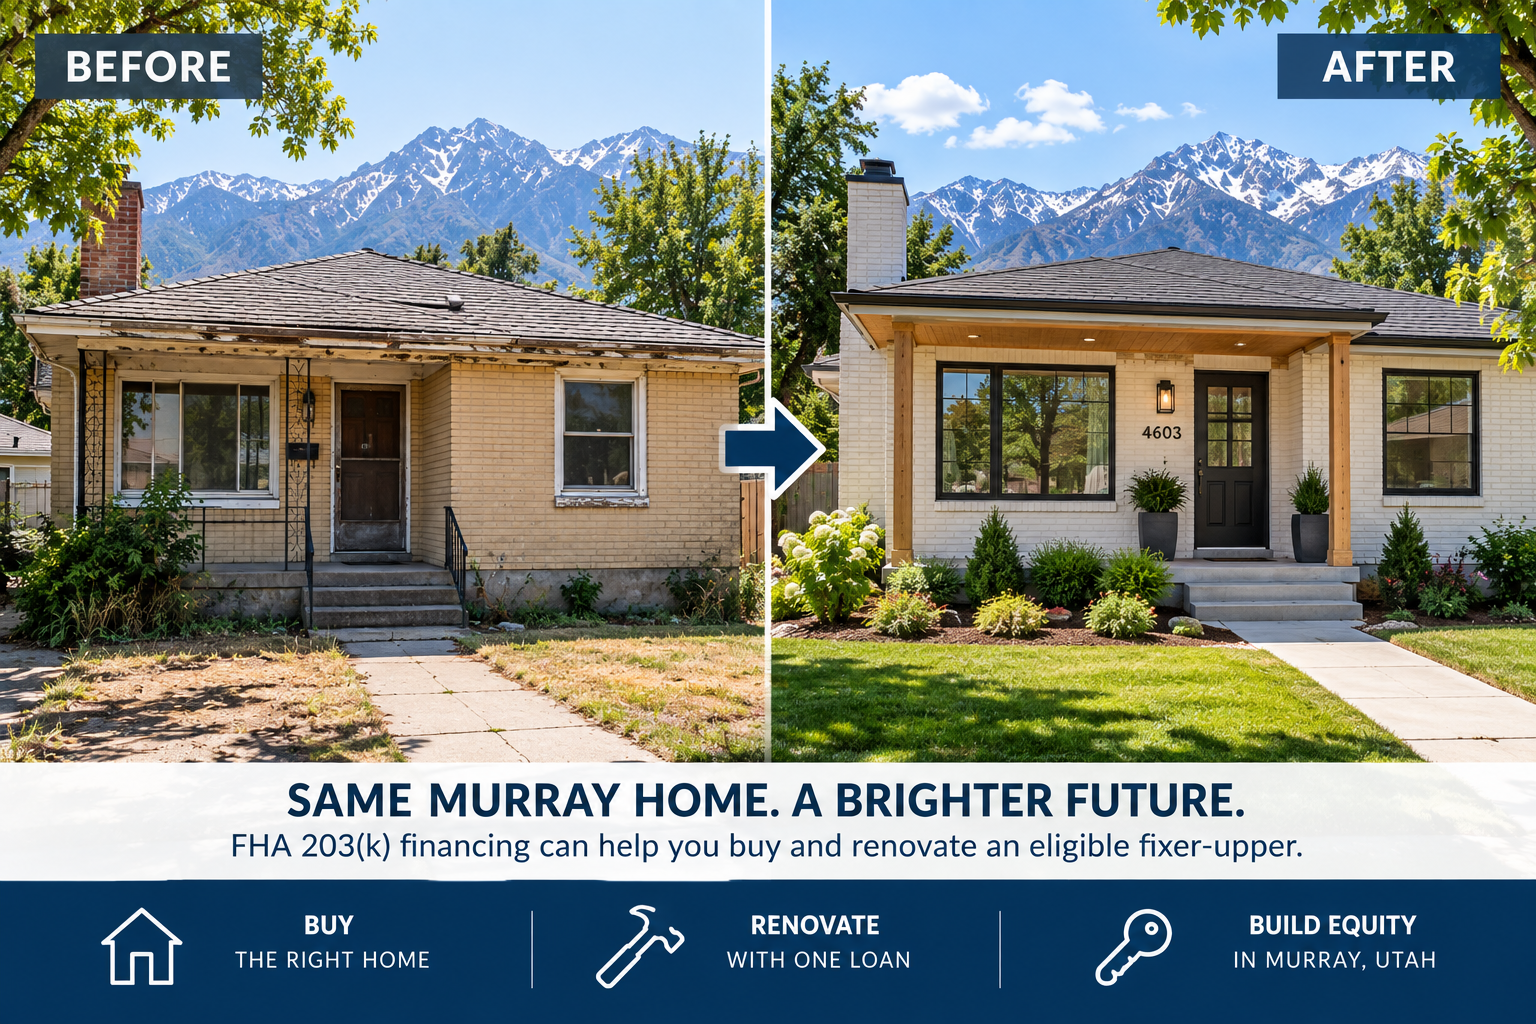
Potentially, yes.
That is one of the primary purposes of FHA's 203(k) program.
For example, suppose you find a Murray home that fits your location and housing goals but needs a new kitchen, flooring, electrical repairs or other eligible improvements.
A standard mortgage may require certain property-condition issues to be corrected before closing. A properly structured FHA 203(k) transaction can allow eligible rehabilitation work to become part of the financing.
The property, borrower and proposed renovations must all satisfy applicable FHA and lender requirements.
FHA 203k Loans for Older Murray Homes
Murray includes established neighborhoods with homes built across many different periods.
An older property may have features buyers like—such as an established neighborhood, mature landscaping or convenient access to Salt Lake County employment and transportation—but it may also need modernization.
Potential projects could involve:
- Electrical updates
- Plumbing improvements
- Roofing
- Heating and cooling
- Kitchen remodeling
- Bathroom remodeling
- Windows
- Flooring
- Energy-efficiency upgrades
An FHA 203(k) mortgage can be particularly useful when a buyer likes the location and basic structure of a property but wants to finance eligible improvements after acquisition.
Can I Use an FHA 203k Loan on a Duplex, Triplex or Fourplex?
Eligible two-, three- and four-unit properties can potentially qualify for FHA 203(k) financing when program requirements are satisfied.
The borrower must meet applicable FHA occupancy requirements.
This can make renovation financing worth investigating when purchasing an eligible small multifamily property that requires repairs.
Different FHA mortgage limits apply according to the number of units.
FHA 203k Purchase vs. Refinance
Purchase
A purchase transaction can combine eligible costs associated with buying the property and completing approved renovations.
This can be useful for buyers who find a home in Murray that needs work before it fully meets their needs.
Refinance
Eligible homeowners may also be able to refinance an existing property and finance approved rehabilitation costs through a 203(k) mortgage.
If your home does not require renovation financing, compare a regular FHA refinance or other refinance options instead.
FHA 203k vs. Regular FHA Loan
A regular FHA mortgage primarily finances the property.
An FHA 203(k) mortgage adds a rehabilitation component.
A regular FHA loan may be appropriate when the home is already in acceptable condition and no substantial financed improvements are necessary.
A 203(k) may be worth considering when the home needs eligible repairs or improvements and you want to incorporate those expenses into the mortgage.
Compare the options on our main Utah FHA loan page.
FHA 203k vs. Conventional Renovation Financing
FHA 203(k) is not the only way to finance a home that needs improvements.
Depending on credit, down payment, property type and renovation scope, a conventional mortgage or other financing strategy may be worth comparing.
Start with:
The appropriate program depends on your individual qualifications and the property.
Documents You May Need
FHA 203(k) documentation varies by transaction, but borrowers should be prepared for both ordinary mortgage documents and renovation-related paperwork.
Examples may include:
- Income documentation
- Asset statements
- Identification
- Purchase contract
- Contractor bids
- Detailed scope of work
- Renovation cost estimates
- Appraisal
- Consultant documentation when required
- Additional property or project documents requested during underwriting
Getting the renovation documentation organized early can help prevent unnecessary delays.
Common FHA 203k Mistakes to Avoid
Waiting Too Long to Discuss the Renovations
Tell your mortgage professional that the property needs renovation financing before making assumptions about how the transaction will work.
Assuming Every Improvement Is Eligible
FHA establishes requirements for eligible improvements. Confirm the proposed work before relying on 203(k) financing.
Using Incomplete Contractor Estimates
Detailed, accurate bids can be important. Vague estimates can create problems during underwriting.
Confusing Limited and Standard 203k
A Limited 203(k) is intended for smaller, nonstructural work. Major or structural rehabilitation generally requires the Standard program.
Ignoring FHA Loan Limits
The mortgage still needs to satisfy the applicable FHA county limit.
Comparing Only the Interest Rate
Consider the complete financing structure, including mortgage insurance, renovation costs, closing costs and monthly payment.
Why Work With Utah Low Rate?
Utah Low Rate helps borrowers compare mortgage programs rather than assuming one loan fits every situation.
Daniel Paris has more than 27 years of mortgage-industry experience and works with homebuyers and homeowners throughout Utah.
For a Murray renovation purchase, we can help you evaluate questions such as:
- Does the property appear suitable for FHA 203(k) financing?
- Is Limited or Standard 203(k) more appropriate?
- How do the proposed repairs affect the transaction?
- What documentation may be required?
- How does FHA compare with conventional financing?
- What FHA loan limit applies?
- What might the estimated mortgage payment look like?
The objective is to understand the financing before you commit to a renovation property.
FHA 203k Loan Murray Utah FAQ
What is an FHA 203k loan?
An FHA 203(k) is an FHA-insured mortgage that allows qualified borrowers to combine eligible property acquisition or refinance financing with rehabilitation expenses in one mortgage.
What is the maximum renovation amount for a Limited FHA 203k loan?
Under current FHA rules, a Limited 203(k) can finance up to $75,000 in total rehabilitation costs, subject to applicable requirements.
Does a Standard FHA 203k have a renovation limit?
The Standard 203(k) does not use the same $75,000 rehabilitation cap as the Limited program. However, FHA mortgage limits and other program requirements still constrain the overall financing.
What is the minimum renovation amount for a Standard 203k?
Standard 203(k) rehabilitation costs must generally be at least $5,000.
Can an FHA 203k loan pay for structural repairs?
A Standard 203(k) can be used for eligible structural repairs and major rehabilitation. Limited 203(k) is designed for minor remodeling and nonstructural repairs.
Do I need a 203k consultant?
A 203(k) consultant is required for Standard 203(k). A consultant is generally optional for Limited 203(k).
Can I use an FHA 203k loan to buy a fixer-upper in Murray?
Potentially. The property, borrower, renovations and mortgage must satisfy applicable FHA and lender requirements.
Can I use FHA 203k financing for a duplex?
Eligible one- to four-unit properties may qualify, subject to FHA requirements and owner-occupancy rules.
Can a first-time buyer use an FHA 203k loan?
Yes. FHA 203(k) is not limited to first-time buyers, but an eligible first-time buyer can use the program when all applicable requirements are met.
Can I use a 203k loan for an investment property?
FHA financing generally requires the borrower to occupy the property as a principal residence. It is not designed as standard financing for a non-owner-occupied investment property.
Are renovation funds given directly to me at closing?
Generally, applicable rehabilitation funds are held in a rehabilitation escrow account and released according to FHA and lender requirements as approved work progresses.
What FHA loan limit applies in Murray, Utah?
Murray is in Salt Lake County. For 2026, the FHA one-unit mortgage limit for Salt Lake County is $637,100, with higher limits for eligible two-, three- and four-unit properties.
Talk With a Murray FHA 203k Mortgage Professional
Buying a property that needs repairs creates different financing questions than buying a move-in-ready home.
Before deciding that a fixer-upper will—or will not—work, have the property, estimated renovation budget and your mortgage qualifications reviewed together.
Daniel Paris
Utah Low Rate / UtahLowRate.com
Phone: 801-604-4949
NMLS #243976
Explore Utah mortgage loan programs or request a personalized mortgage quote to discuss an FHA 203(k) property in Murray or elsewhere in Utah.
Loan approval, rates, terms, renovation eligibility and available programs are subject to borrower qualification, property eligibility, underwriting requirements and applicable FHA/lender guidelines.

