
Quick answer: Utah mortgage rates depend on your loan program, credit, down payment or equity, property, occupancy, points and lock period. The national averages below provide dated market context. Daniel Paris helps Utah buyers and homeowners compare personalized interest rates, APRs, fees and payments before choosing a loan.
Get Today’s Rate
Explore today’s mortgage rate options for your Utah home purchase or refinance.
Compare Utah Home Loan Rates
Mortgage rates in Utah can change daily—and sometimes during the same day. Your actual mortgage rate depends on the loan program, credit profile, down payment or equity, loan amount, property type, occupancy, points, lock period and current financial markets.
Daniel Paris at UtahLowRate.com helps Utah homebuyers, homeowners, veterans, investors and self-employed borrowers compare mortgage rates, APRs, points, closing costs and loan programs based on their specific financing needs.
Whether you are buying a home, refinancing, purchasing an investment property or financing a higher-priced Utah property, comparing the complete loan—not just the advertised interest rate—can help you make a more informed decision.
Get Today’s Utah Rate | Compare mortgage programs
Quick Answer: What Are Mortgage Rates in Utah Today?
There is no single mortgage rate that applies to every Utah borrower. Rates vary based on credit, loan type, loan amount, down payment or equity, property type, occupancy, points and lock period. National mortgage averages can show overall market direction, but your actual Utah mortgage rate requires a personalized quote based on your specific scenario.
Today’s Utah Mortgage Rate Market
National Mortgage Rate Benchmark
As of October 1, 2026, Freddie Mac’s Primary Mortgage Market Survey reported these national weekly averages:
| Mortgage Type | National Weekly Average |
|---|---|
| 30-Year Fixed Mortgage | 7.28% |
| 15-Year Fixed Mortgage | 6.60% |
Source and publication date: Freddie Mac PMMS, October 1, 2026. These are national conventional conforming purchase benchmarks. They do not include a personalized APR, points, fees or rate-lock offer.
Important: These are national Freddie Mac survey averages, not advertised rates or loan offers from UtahLowRate.com.
Freddie Mac's survey is useful for understanding the direction of the broader mortgage market. Your actual Utah mortgage pricing may be higher or lower depending on your borrower profile, property and loan program.
FHA, VA, jumbo, super-jumbo, DSCR, bank statement and other non-QM mortgage programs should be priced separately rather than estimated from a conventional conforming national average.
Compare Utah Mortgage Rates by Loan Program
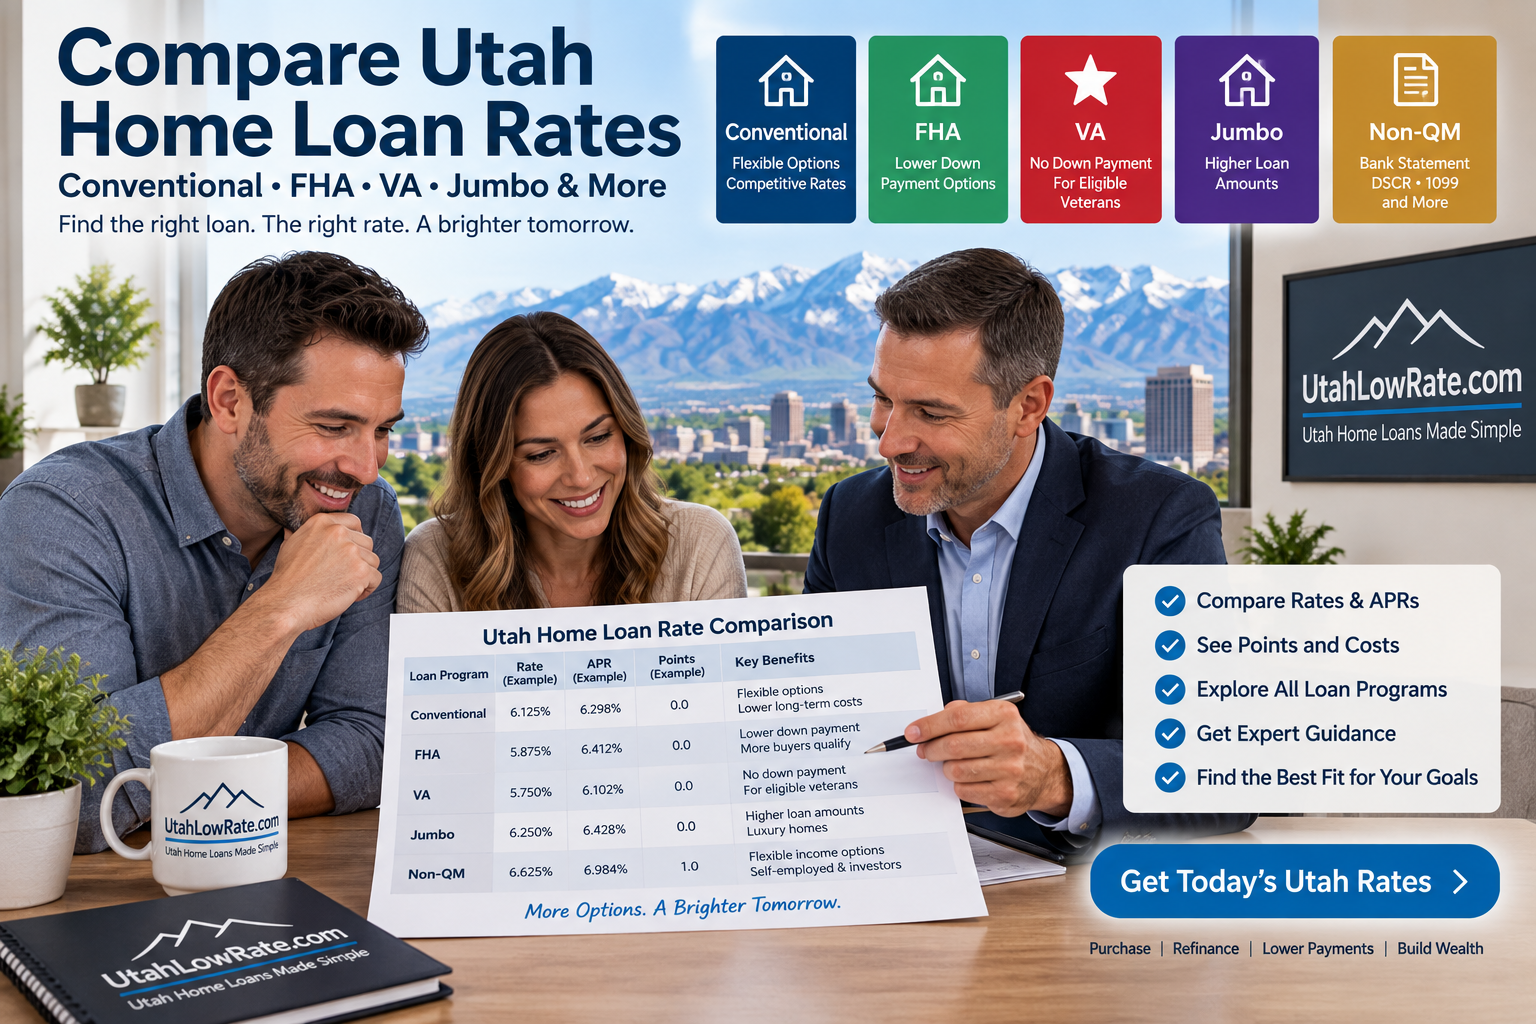
Different mortgage programs are priced differently. The lowest advertised interest rate is not necessarily the best mortgage for your situation.
| Loan Program | Common Use | Important Pricing Factors |
|---|---|---|
| Conventional | Primary, second and investment homes | Credit, LTV, loan amount, occupancy |
| FHA | Eligible primary residences | Credit, LTV, mortgage insurance, loan amount |
| VA | Eligible veterans and service members | Credit, entitlement, funding fee, loan purpose |
| Jumbo | Higher-priced properties | Loan amount, LTV, reserves, credit, assets |
| Super Jumbo | High-value properties and large loans | Loan amount, liquidity, assets, reserves, LTV |
| Bank Statement | Self-employed borrowers | Deposits, income calculation, credit, LTV, reserves |
| DSCR | Investment properties | Property cash flow, DSCR, LTV, credit, loan amount |
| Stated Income / Alternative Documentation | Qualified borrowers needing alternative documentation | Program, assets, credit, LTV and property |
Explore additional financing options through our Utah Mortgage Loans guide or Utah Home Loans page.
30-Year Fixed Mortgage Rates in Utah
A 30-year fixed-rate mortgage is one of the most commonly used home financing options in Utah.
The interest rate remains fixed for the life of the loan, which means the scheduled principal-and-interest payment does not change because of interest-rate movements.
A 30-year term generally provides a lower required monthly principal-and-interest payment than a comparable 15-year mortgage because repayment is spread over a longer period.
It may appeal to buyers who want to preserve monthly cash flow while purchasing homes in Salt Lake County, Utah County, Davis County, Weber County, Washington County or other Utah markets.
The tradeoff is that a borrower generally pays more total interest over 30 years than with a shorter loan term.
When comparing 30-year mortgages, look at:
- Interest rate
- APR
- Discount points
- Lender credits
- Closing costs
- Mortgage insurance, when applicable
- Monthly payment
- Cash required at closing
- Rate-lock period
For traditional financing options, see conventional mortgage loans in Utah.
15-Year Fixed Mortgage Rates in Utah
A 15-year fixed mortgage repays the principal over a shorter period.
The interest rate may be lower than a comparable 30-year fixed mortgage, but the required monthly payment is generally higher because the loan balance is repaid faster.
A 15-year mortgage may be worth comparing if you:
- Are refinancing a smaller remaining mortgage balance
- Have strong monthly cash flow
- Want to build equity faster
- Want to reduce total interest over the life of the loan
- Can comfortably handle the higher required payment
Rather than choosing solely based on the lower rate, compare the 15-year and 30-year payments, closing costs, breakeven period and projected total interest.
Conventional Mortgage Rates in Utah
Conventional mortgages are commonly used for primary residences, eligible second homes and investment properties.
Pricing may be influenced by:
- Credit score
- Loan-to-value ratio
- Down payment
- Loan amount
- Property type
- Occupancy
- Number of units
- Purchase versus refinance
- Cash-out versus rate-and-term refinance
- Loan term
- Points and lender credits
Conventional financing is not one single rate. Two borrowers requesting the same loan amount can receive different pricing because their credit, equity, property and transaction details are different.
Learn more about conventional mortgage loans in Utah.
FHA Mortgage Rates in Utah
FHA loans can provide flexible home financing for eligible borrowers purchasing or refinancing a primary residence.
FHA mortgage rates may appear competitive compared with some conventional options, but borrowers should consider the entire financing structure.
That includes:
- Interest rate
- APR
- Upfront mortgage insurance premium
- Annual mortgage insurance
- Down payment
- Closing costs
- Loan term
- FHA loan limits
- Length of time you expect to own the property
Credit score, loan amount, LTV, property eligibility and current market conditions can also affect FHA pricing and qualification.
Learn more about FHA Loans Utah.
VA Mortgage Rates in Utah
VA home loans are available to eligible veterans, active-duty service members and certain qualifying surviving spouses.
Potential VA loan benefits can include no monthly private mortgage insurance and financing with little or no down payment for eligible borrowers, subject to VA requirements, entitlement, property value and underwriting.
VA mortgage pricing can depend on:
- Credit profile
- Loan amount
- VA entitlement
- Funding-fee status
- Down payment, if any
- Purchase or refinance
- Property type
- Occupancy
- Market conditions
Eligible borrowers should compare the interest rate, APR, funding fee, closing costs and total payment—not simply the advertised note rate.
Jumbo Mortgage Rates in Utah
Jumbo loans are commonly used when the requested mortgage amount exceeds the applicable conforming loan limit.
They can be especially relevant for higher-priced properties in markets such as:
Park City, Deer Valley, Salt Lake City, Holladay, Cottonwood Heights, Draper, Alpine, Highland, Heber City and other Utah luxury-home markets.
Jumbo mortgage rates can be particularly sensitive to:
- Loan amount
- Credit score
- LTV
- Property type
- Primary, second-home or investment occupancy
- Income documentation
- Liquid reserves
- Assets
- Debt-to-income ratio
- Fixed versus adjustable rate
- Loan structure
Because jumbo programs vary substantially among investors, comparing multiple available programs may uncover meaningful differences in rate, documentation requirements and reserves.
Super Jumbo Mortgage Rates in Utah
Large mortgage transactions may require specialized super-jumbo financing.
UtahLowRate.com works with eligible super-jumbo scenarios, including larger loan amounts for qualified borrowers and properties.
Super-jumbo pricing may depend heavily on:
- Loan size
- LTV
- Borrower liquidity
- Post-closing reserves
- Credit
- Income and assets
- Property characteristics
- Occupancy
- Fixed versus ARM structure
- Pledged-asset or other eligible structures
For large financing scenarios, see super jumbo financing in Utah and California.
Bank Statement Mortgage Rates in Utah
Self-employed borrowers may have difficulty qualifying using tax returns alone even when their businesses produce substantial cash flow.
A bank statement mortgage may allow an eligible borrower to qualify using deposits from personal or business bank statements rather than relying exclusively on traditional tax-return income.
Common programs may review 12 or 24 months of statements, depending on the investor and borrower scenario.
Pricing can be affected by:
- Personal versus business bank statements
- Eligible monthly deposits
- Business expense calculation
- Length of self-employment
- Credit score
- LTV
- Loan amount
- Property type
- Occupancy
- Reserves
- Fixed or adjustable term
- Interest-only features, when available
- Prepayment provisions where permitted
Bank statement loans are generally non-QM mortgages and should not be expected to have identical pricing to agency conventional loans.
The better comparison is whether the program provides usable qualifying income while offering an acceptable combination of rate, payment, points, fees and cash required.
Estimate My Bank Statement Income
DSCR Mortgage Rates in Utah
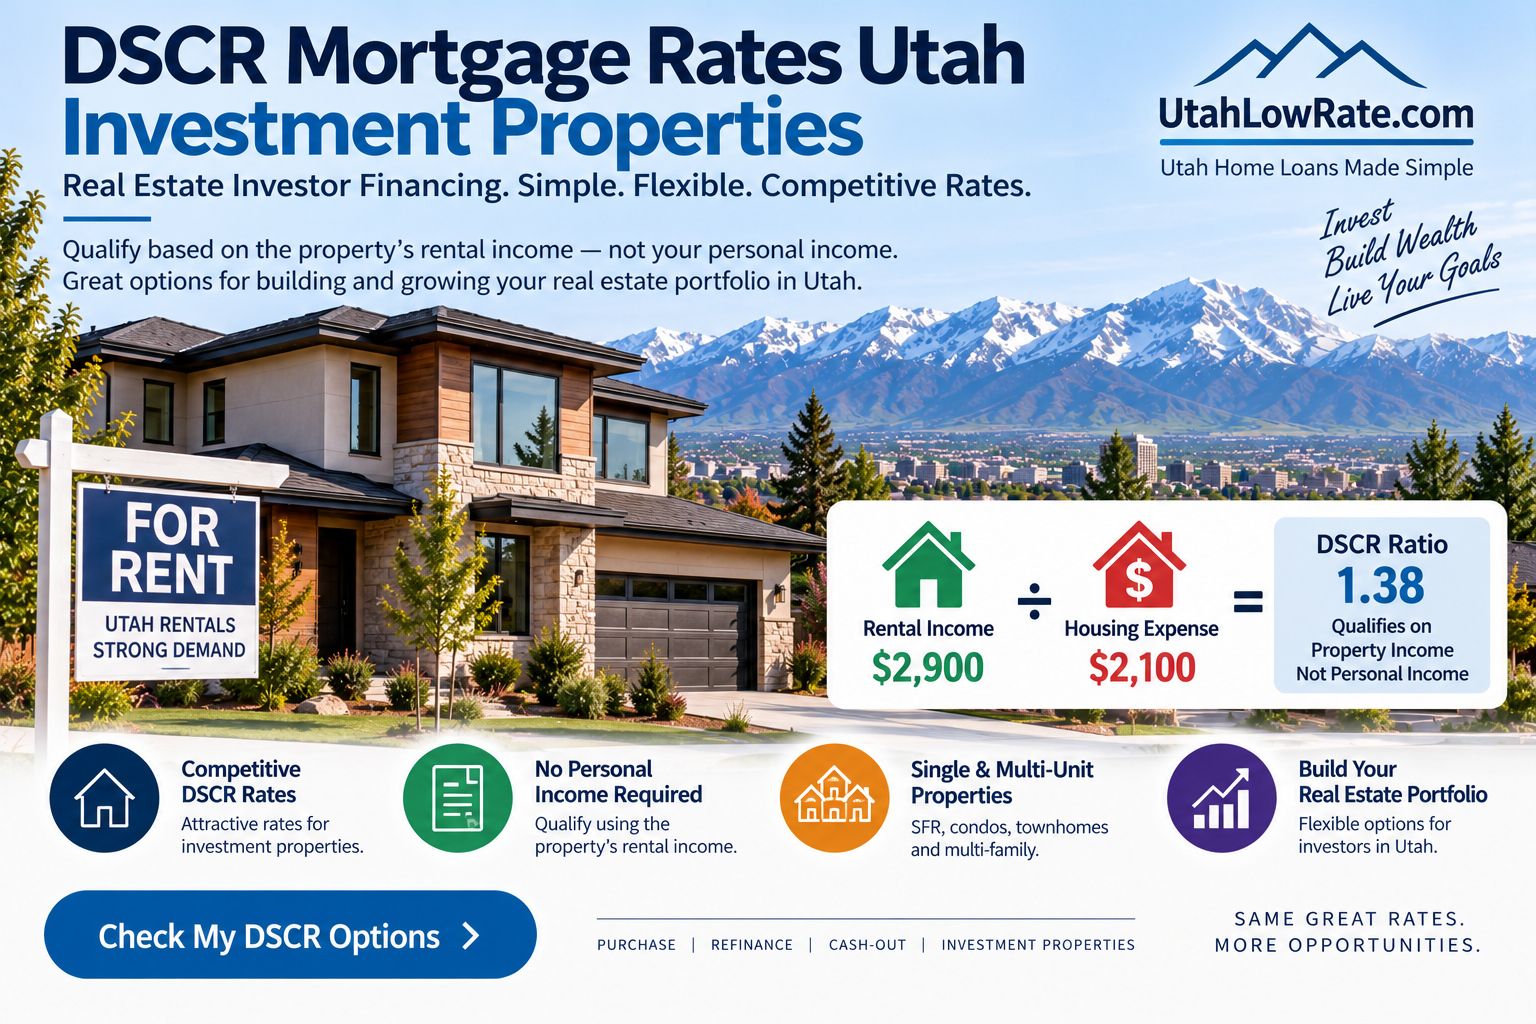
DSCR loans are designed primarily for real-estate investors and generally focus on the property's rental income and housing expense rather than traditional personal debt-to-income qualification.
DSCR stands for Debt Service Coverage Ratio.
A basic calculation is:
DSCR = Qualifying Monthly Rental Income ÷ Qualifying Monthly Property Housing Expense
For example, if qualifying rent is $4,000 and the applicable monthly housing expense is $3,200:
$4,000 ÷ $3,200 = 1.25 DSCR
DSCR pricing may vary based on:
- DSCR ratio
- Credit score
- LTV
- Loan amount
- Property type
- Rental income
- Purchase versus refinance
- Cash-out amount
- Prepayment structure
- Interest-only options
- Investor guidelines
Some programs may also offer options for properties with a DSCR below 1.00 or other specialized investor scenarios, subject to current investor guidelines.
What Determines Your Mortgage Rate in Utah?
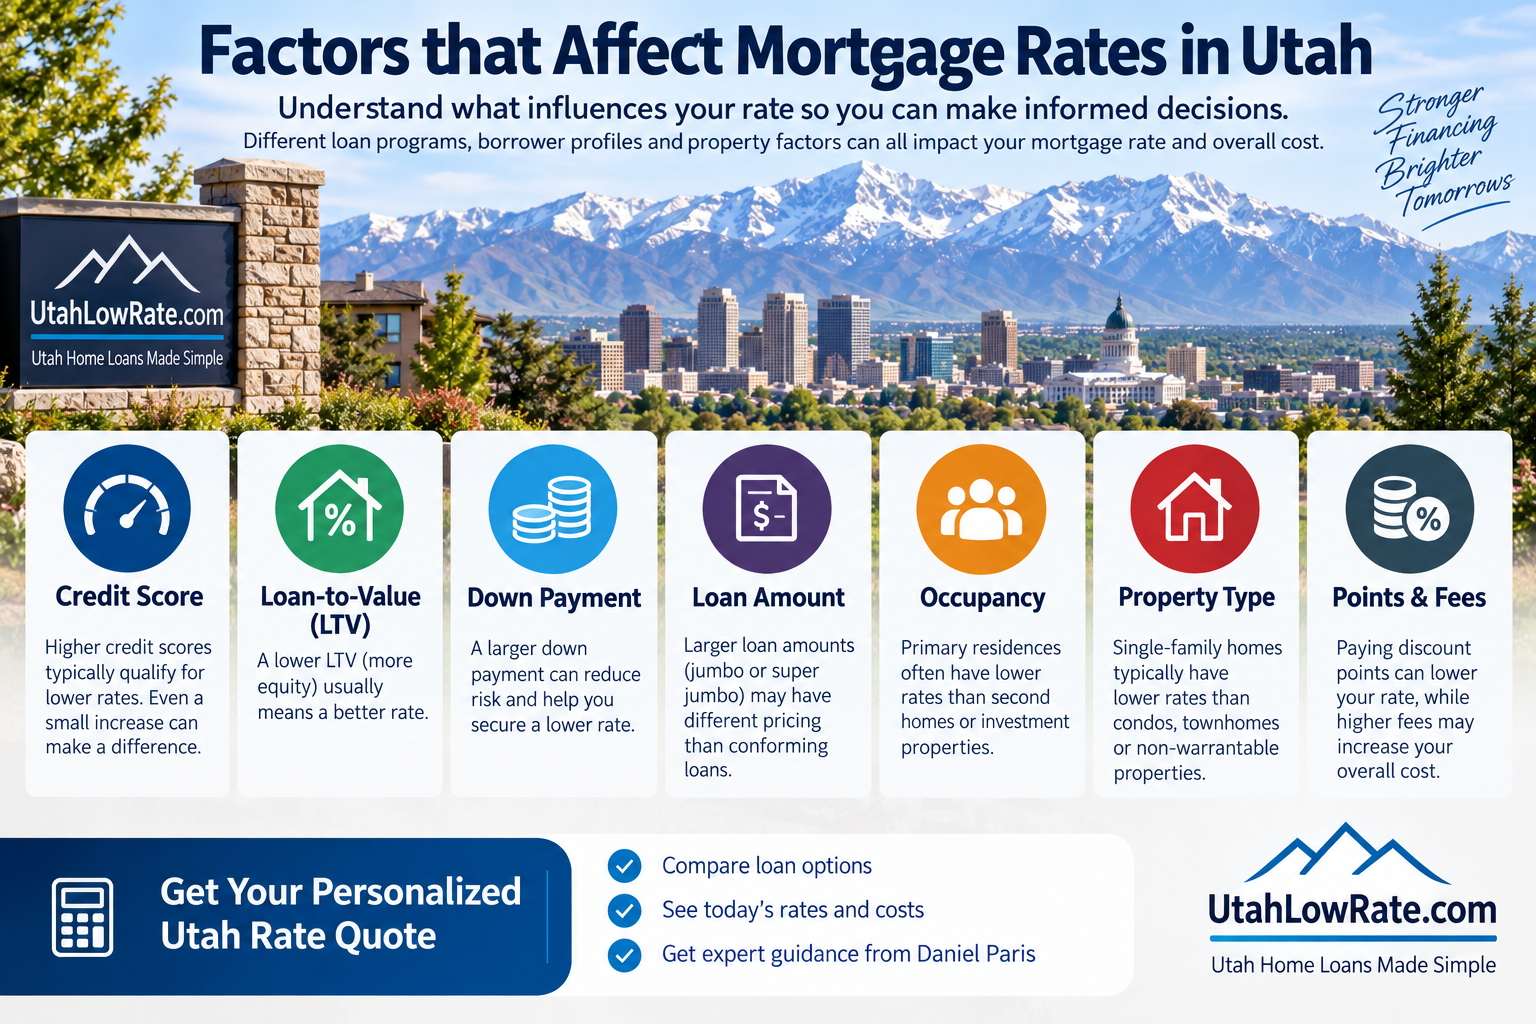
Your mortgage rate is not determined by one factor.
Lenders and mortgage investors evaluate multiple characteristics when pricing a loan.
Credit Score
Credit is an important mortgage-pricing factor.
In general, stronger qualifying credit can provide access to better pricing, while lower credit scores may result in pricing adjustments, additional requirements or fewer program choices.
However, the effect varies by mortgage program.
Do not assume that waiting to improve your credit score is automatically the best decision. Compare the financing currently available with a realistic improved-credit scenario.
Down Payment and Loan-to-Value Ratio
Loan-to-value ratio, or LTV, compares the mortgage balance with the property's value.
Lower LTV can sometimes improve mortgage pricing because the borrower has more equity in the property.
But using all available cash for a larger down payment is not always the right strategy. Maintaining adequate reserves may be important, especially for jumbo, investment and non-QM financing.
Loan Amount
Mortgage pricing can change at different loan sizes.
Conforming, high-balance, jumbo and super-jumbo loans may have different pricing and underwriting structures.
Property Type
A detached single-family residence may receive different pricing from a condominium, multi-unit property or certain investment properties.
Occupancy
Pricing can vary depending on whether the property will be:
- A primary residence
- A second home
- An investment property
Purchase vs. Refinance
Purchase, rate-and-term refinance and cash-out refinance transactions can receive different pricing.
Mortgage Points vs. No-Point Pricing
One mortgage discount point generally equals 1% of the loan amount.
On a $500,000 mortgage:
1 point = $5,000
Paying discount points may allow you to obtain a lower interest rate. A no-point or lender-credit structure may reduce upfront costs but can result in a higher interest rate.
Neither option is automatically better.
A simple breakeven calculation is:
Additional upfront cost ÷ monthly payment savings = breakeven months
For example:
$4,000 additional cost ÷ $100 monthly savings = 40 months
If you expect to sell or refinance before the breakeven period, paying additional points may provide less value.
The calculation should also consider your individual financial circumstances and the complete loan structure.
Mortgage Interest Rate vs. APR
The interest rate is the percentage used to calculate mortgage interest.
The annual percentage rate (APR) is a broader measure of borrowing cost that incorporates the interest rate and certain finance charges.
When comparing mortgage offers, review:
- Interest rate
- APR
- Discount points
- Origination/lender charges
- Lender credits
- Mortgage insurance
- Prepayment provisions, when applicable
- Monthly payment
- Cash required at closing
Two loans advertising the same interest rate can have different APRs and substantially different upfront costs.
Freddie Mac Mortgage Rates vs. Your Utah Mortgage Rate
Freddie Mac's Primary Mortgage Market Survey provides a useful national benchmark for conventional mortgage-market trends.
It is not a personalized Utah mortgage quote.
Your actual rate can differ because of:
- Credit profile
- Loan program
- Loan amount
- Property value
- LTV
- Property type
- Occupancy
- Purchase or refinance
- Cash-out amount
- Lock period
- Points
- Lender credits
- Income documentation
- Assets and reserves
Use national mortgage averages to understand market direction—not as a substitute for scenario-specific pricing.
How Mortgage Rate Locks Work
Mortgage rates can change while a loan is being processed.
A mortgage rate lock generally holds specified loan pricing for an agreed period, subject to the lock terms and the borrower and property continuing to meet applicable requirements.
Common lock periods may include:
- 15 days
- 30 days
- 45 days
- 60 days
Other lock periods may be available.
Longer rate locks can sometimes have different pricing.
Before locking your mortgage rate, ask:
- What interest rate is being locked?
- What is the APR?
- Are discount points being charged?
- Are lender credits included?
- When does the lock expire?
- What happens if closing is delayed?
- Is there a rate-lock extension cost?
- Is a float-down option available, and what are its conditions?
What Causes Utah Mortgage Rates to Change?
Utah mortgage rates are influenced heavily by national financial markets.
Factors that can influence mortgage pricing include:
- Treasury yields
- Inflation expectations
- Employment data
- Economic growth
- Federal Reserve policy expectations
- Mortgage-backed securities markets
- Investor demand
- Global economic and financial events
The Federal Reserve does not directly set consumer 30-year mortgage rates.
Mortgage rates can move before or after Federal Reserve meetings because financial markets continually adjust expectations about inflation, economic growth and monetary policy.
That is one reason trying to predict the exact lowest day to lock a mortgage can be difficult.
Utah Mortgage Rates for Home Purchases
Homebuyers should compare financing early in the purchase process rather than waiting until they are under contract.
A mortgage pre-approval can help determine:
- Estimated purchasing power
- Down-payment options
- Potential loan programs
- Estimated housing payment
- Documentation requirements
- Possible rate and cost structures
Start with Utah Mortgage Pre-Approval before making an offer.
Utah Mortgage Refinance Rates
A refinance may make sense for reasons beyond simply obtaining a lower interest rate.
Utah homeowners may consider refinancing to:
- Reduce an interest rate
- Change loan terms
- Move from an ARM to fixed financing
- Eliminate or restructure mortgage insurance
- Consolidate qualifying debt
- Access home equity
- Change borrowers on the mortgage
- Restructure a jumbo or non-QM loan
Compare the new payment, closing costs, loan balance and breakeven period before deciding.
How to Compare Utah Mortgage Rates Correctly
When comparing mortgage quotes, make sure the assumptions are the same.
Compare quotes using the same:
- Loan amount
- Property value
- Down payment
- Credit profile
- Occupancy
- Property type
- Loan program
- Loan term
- Lock period
- Number of points
- Lender-credit structure
A 6.50% rate with substantial discount points cannot fairly be compared with a 6.75% no-point rate by looking only at the note rate.
Compare the rate, APR, points, lender fees, payment and cash required at closing together.
How to Get an Accurate Utah Mortgage Rate Quote
For a useful mortgage-rate comparison, provide:
- Purchase price or estimated property value
- Requested loan amount
- Down payment or current equity
- Property city or county
- Property type
- Primary residence, second home or investment property
- Estimated credit-score range
- Purchase, refinance or cash-out refinance
- Income-documentation type
- Desired closing date
- Preference for points, no points or lower upfront costs
Daniel Paris can then compare eligible mortgage programs and explain the rate, APR, payment, closing costs and tradeoffs.
Utah Mortgage Rates by Location
UtahLowRate.com works with borrowers throughout Utah, including:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale, Park City, Deer Valley, Heber City, Midway, Kamas, Provo, Orem, Lehi, Alpine, Highland, American Fork, Saratoga Springs, Eagle Mountain, Ogden, St. George, Washington, Ivins, Santa Clara and surrounding Utah communities.
The property location itself does not create one universal local mortgage rate. Pricing still depends on the borrower, property, loan amount and selected program.
Local knowledge becomes particularly important when loan limits, property characteristics, condominium requirements, jumbo financing or specialized loan programs are involved.
Why Work With a Utah Mortgage Broker?
A mortgage broker can compare eligible programs and pricing from multiple wholesale mortgage sources rather than limiting the search to one retail lender's product menu.
Daniel Paris has more than 27 years of mortgage-industry experience and helps borrowers compare conventional, FHA, VA, jumbo, super-jumbo and alternative-documentation mortgage options.
The objective is not simply to find the lowest advertised rate.
It is to identify a financing structure that fits the borrower's qualifications, property, loan amount, cash requirements and financial goals.
Learn more about Daniel Paris and UtahLowRate.com.
Get a Personalized Utah Mortgage Rate Quote
Online mortgage averages cannot account for your credit, equity, loan amount, property, occupancy, documentation or goals.
Compare available options for:
- Conventional loans
- FHA loans
- VA loans
- Jumbo mortgages
- Super-jumbo mortgages
- Bank statement loans
- DSCR investor loans
- Alternative-documentation mortgages
- Purchase loans
- Refinances
- Cash-out refinances
Call Daniel Paris: 801-604-4949
Rates, terms and loan programs are subject to change without notice. All loans are subject to applicable underwriting requirements, property eligibility, investor guidelines and final approval. Information on this page is educational and is not a commitment to lend.
Should I compare a fixed-rate mortgage with an ARM?
A fixed-rate mortgage keeps the note rate unchanged. An adjustable-rate mortgage may begin with a fixed period and then adjust under its index, margin and caps. Compare the first adjustment date, maximum payment, adjustment limits and total costs. A planned refinance is not guaranteed, so evaluate whether the future payment fits your budget.
What should I compare on a Loan Estimate?
Compare offers for the same loan amount, term, occupancy and lock period. Review the rate, estimated total monthly payment, lender charges, discount points, lender credits, cash to close and APR. Confirm the lock expiration, any prepayment penalty and any balloon payment. Taxes, insurance and other third-party estimates can differ without reflecting a lender-price advantage.
Use the CFPB Loan Estimate explainer to review the form. Ask about any item that differs from your discussion with the lender.
Related Utah mortgage guides
Conventional mortgage loans | Jumbo mortgages | Bank statement loans | DSCR rental-property loans
Frequently Asked Questions About Utah Mortgage Rates
What are mortgage rates in Utah today?
There is no single mortgage rate for every Utah borrower. Rates depend on the loan program, credit profile, loan amount, down payment or equity, property, occupancy, points and lock period. National averages can provide market context, but a personalized quote is needed to determine the pricing available for your scenario.
What is the current 30-year mortgage rate?
Freddie Mac reported a national weekly average of 7.28% for the 30-year fixed-rate mortgage as of October 1, 2026. This is a national market benchmark and is not a UtahLowRate.com rate quote. Your actual rate may be higher or lower.
What is the current 15-year mortgage rate?
Freddie Mac reported a national weekly average of 6.60% for the 15-year fixed-rate mortgage as of October 1, 2026. Actual pricing depends on the borrower, property, loan structure and current market.
Are Utah mortgage rates different from national mortgage rates?
National mortgage markets strongly influence Utah rates, but individual Utah borrowers receive pricing based on their credit, loan amount, LTV, property, occupancy, loan program, points and lock period. National averages are useful benchmarks but are not guaranteed Utah offers.
Does a higher credit score lower my mortgage rate?
A stronger qualifying credit profile can often improve mortgage pricing, but the effect depends on the program and other loan characteristics. Credit is only one of several factors used to determine pricing.
Does a larger down payment give me a lower mortgage rate?
Sometimes. A larger down payment reduces LTV and may improve pricing for certain programs. However, the effect varies, and maintaining adequate cash reserves can also be important.
Is a 15-year mortgage rate lower than a 30-year mortgage rate?
It often can be, but the monthly payment is generally higher because the principal is repaid over 15 years instead of 30. Compare both payment and total borrowing cost.
Can I lower my mortgage rate by paying points?
Potentially. Discount points are upfront costs paid to obtain different mortgage pricing. Compare the additional cost with the monthly savings and calculate how long it will take to break even.
What is the difference between mortgage rate and APR?
The interest rate determines mortgage interest. APR is a broader cost measure that incorporates the interest rate and certain finance charges. Both should be reviewed when comparing mortgages.
Are FHA mortgage rates lower than conventional rates?
FHA note rates can sometimes be competitive, but the comparison should also include mortgage insurance, APR, fees and total payment. The lowest note rate does not automatically mean the lowest-cost loan.
Are VA mortgage rates lower than conventional rates?
VA loans can offer competitive pricing for eligible borrowers, but rates vary by lender, credit, loan amount and transaction. Funding-fee status and overall loan costs should also be considered.
Are jumbo mortgage rates higher than conventional mortgage rates?
Not necessarily. Jumbo pricing varies by market conditions, loan amount, credit, LTV, reserves, assets and property. Some well-qualified jumbo borrowers may receive highly competitive pricing.
Why are bank statement mortgage rates different?
Bank statement mortgages generally use alternative income documentation and are commonly classified as non-QM financing. Pricing depends on credit, LTV, calculated income, reserves, loan amount and program structure.
What affects DSCR mortgage rates?
DSCR pricing can be influenced by the property's debt-service coverage ratio, credit score, LTV, loan amount, property type, transaction type and prepayment structure.
When should I lock my Utah mortgage rate?
The appropriate time depends on your closing schedule, available pricing, market volatility and risk tolerance. Rather than trying to predict the exact market bottom, review your current rate, APR, costs and lock terms in relation to your transaction.
How often do mortgage rates change?
Mortgage pricing can change daily and may sometimes change more than once during a business day as financial markets move.
How often is this Utah mortgage rates page updated?
Check the Last reviewed date at the top of this page and the publication date beside the benchmark table. Survey figures describe that release, not live pricing. Request a new personalized quote before making a rate or lock decision.

