
Content updated: September 29, 2026
$30 Million Mortgage Loans Utah are specialized super jumbo financing solutions designed for qualified borrowers purchasing or refinancing exceptionally high-value real estate. UtahLowRate.com helps qualified borrowers evaluate large-balance mortgage options for luxury properties in Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Heber City, Midway, St. George and other Utah luxury-home markets.
A $30 million mortgage is far outside conventional lending limits. These transactions generally require specialized underwriting, substantial liquidity, strong credit, significant reserves and a carefully structured loan-to-value ratio.
Check My Jumbo Options or call 801-604-4949.
Daniel Paris | Utah Mortgage Broker | UtahLowRate.com
27+ Years of Mortgage Lending Experience
Call: 801-604-4949
Programs, loan amounts, rates, LTV limits and qualification requirements vary by lender and are subject to underwriting approval.
Quick Answer: Can You Get a $30 Million Mortgage in Utah?
Yes. Specialized super jumbo lending programs may provide $30 million mortgage loans in Utah for highly qualified borrowers and eligible properties. Approval can depend on property value, loan-to-value ratio, credit, income, liquidity, net worth, reserves, assets and the overall financial profile of the borrower.
Because very few traditional mortgage programs operate at this loan size, comparing specialized super jumbo lending sources can be especially important.
$30 Million Mortgage Loans Utah: Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Potential $30 Million Mortgage |
|---|---|
| Loan category | Super Jumbo |
| Potential loan amount | Up to $30 million+ with select programs |
| Property use | Primary, second home and select investment scenarios |
| Transactions | Purchase, refinance and qualifying cash-out |
| Income documentation | Program dependent |
| Asset-based qualification | May be available |
| Pledged assets | May be available through select programs |
| Fixed/ARM options | Program dependent |
| Geographic focus | Utah; select programs may extend beyond Utah |
| Underwriting | Individual high-balance underwriting |
Maximum loan amounts and program features are not guarantees of approval.
What Is a $30 Million Mortgage?
A $30 million mortgage is an exceptionally large residential real estate loan that falls within the super jumbo mortgage category.
Traditional conforming mortgage programs are not designed for transactions of this size. Even many ordinary jumbo lenders have maximum loan amounts substantially below $30 million.
That means financing a property with a $30 million mortgage may require access to specialized private-bank, portfolio, wholesale or super jumbo lending programs.
The transaction may involve:
- A luxury primary residence
- Park City or Deer Valley luxury real estate
- A second or vacation home
- A large estate
- A high-value custom residence
- A qualifying investment property
- A major refinance
- A cash-out transaction
- Complex income or asset structures
Learn more about our Super Jumbo Mortgage Loans Utah & California program and broader Jumbo Mortgage Utah options.
Who May Qualify for a $30 Million Mortgage in Utah?
Qualification for a $30 Million Mortgage Loan in Utah goes far beyond simply having enough monthly income to make the mortgage payment.
A lender may analyze the borrower's complete financial position.
Credit Profile
Strong credit is generally important for super jumbo financing. The lender may evaluate credit scores, mortgage history, revolving obligations and the borrower's overall credit profile.
Liquidity
Liquidity can become particularly important on a $30 million transaction.
A lender may want to determine how much liquid capital remains after the down payment and closing.
Net Worth
Certain super jumbo lenders evaluate a borrower's broader net worth in addition to conventional income and debt calculations.
Post-Closing Reserves
Large mortgage transactions can require significant reserves.
Required reserves vary by lender and may depend on the loan amount, LTV, occupancy and overall financial strength of the borrower.
Income and Cash Flow
Income documentation depends on the program.
Traditional borrowers may qualify with conventional documentation, while business owners and other complex borrowers may need alternative approaches.
Self-employed borrowers can also review Jumbo Bank Statement Loans Utah when conventional tax-return calculations do not accurately represent their available cash flow.
How Much Is the Down Payment on a $30 Million Mortgage?
There is no universal down-payment requirement for a $30 million mortgage.
The required equity depends on the lender, property, occupancy, credit profile, liquidity, loan amount and complete transaction.
For example, a $30 million loan at a hypothetical 50% LTV would correspond to a $60 million property value.
A hypothetical 55% LTV would require a property value of approximately $54.55 million.
These examples illustrate the mathematics only. They are not advertised lending limits or an offer of financing.
For extremely large mortgages, maximum LTV can become more restrictive as loan size increases.
Borrowers should therefore evaluate the proposed:
Property value → Loan amount → LTV → Liquidity → Reserves → Qualification structure
before assuming a particular down payment will be sufficient.
$30 Million Mortgage Loans for Park City and Deer Valley
Park City and Deer Valley are natural Utah markets for super jumbo financing because the area includes luxury estates, ski properties, resort residences and other exceptionally high-value real estate.
A borrower considering a multimillion-dollar property in:
- Deer Valley
- Empire Pass
- Old Town Park City
- Canyons Village
- Promontory
- Glenwild
- The Colony
- Jordanelle
- Hideout
- Kamas
- Heber City
- Midway
may require financing substantially above ordinary jumbo-loan limits.
At the $30 million level, it is useful to review the transaction before making assumptions about maximum leverage or documentation.
$30 Million Mortgage Loans in Salt Lake City
Utah's high-value residential market is not limited to Park City.
Super jumbo financing may also be relevant for qualifying properties in:
- Salt Lake City
- Holladay
- Federal Heights
- Cottonwood Heights
- Draper
- Sandy
- Alpine
- Highland
- Lehi
- Heber City
- Midway
- St. George
Property eligibility remains subject to appraisal and lender requirements.
Purchase Financing With a $30 Million Mortgage
A buyer purchasing an exceptionally valuable Utah residence may need to combine substantial personal capital with specialized super jumbo financing.
The lender may review:
- Purchase price
- Requested mortgage amount
- Down payment
- Loan-to-value ratio
- Property characteristics
- Borrower income
- Liquid assets
- Net worth
- Post-closing reserves
- Credit and mortgage history
Large transactions can also require additional appraisal or valuation review.
The objective is not simply to find a lender advertising a large maximum loan.
The objective is to find a lending structure compatible with the borrower, property and transaction.
$30 Million Mortgage Refinance in Utah
Super jumbo financing can also potentially be used to refinance an existing high-balance mortgage.
A refinance may be considered when a borrower wants to:
- Change the existing loan structure
- Replace a maturing loan
- Adjust fixed versus adjustable-rate exposure
- Consolidate eligible financing
- Restructure property debt
- Access equity where permitted
Rate-and-term and cash-out guidelines can differ significantly.
Borrowers considering equity access should also review our Jumbo Cash-Out Refinance Utah options.
Can You Get Cash Out on a $30 Million Property?
Potentially.
Cash-out financing may be available on certain high-value Utah properties, but maximum LTV and loan amounts can differ from purchase or rate-and-term refinance guidelines.
The lender may pay particular attention to:
- Requested cash-out amount
- Existing liens
- Property value
- Loan-to-value ratio
- Use of proceeds
- Credit
- Liquidity
- Reserves
- Borrower financial strength
A scenario review is usually the best starting point.
$30 Million Mortgage Options for Business Owners
Business owners and entrepreneurs often have substantial financial resources without showing income in the same way as a salaried borrower.
Tax strategies, depreciation, retained business earnings and ownership of multiple entities can make traditional income analysis more complicated.
Depending on the available super jumbo program, possible approaches may include:
- Full-documentation underwriting
- Bank-statement analysis
- Asset depletion
- Alternative documentation
- Pledged-asset structures
- Portfolio lending
- Other lender-specific qualification methods
For qualifying self-employed borrowers, compare our Jumbo Bank Statement Loans Utah and Bank Statement Loans Utah resources.
Asset-Based and Pledged-Asset Super Jumbo Financing
Some ultra-high-net-worth borrowers have substantial investment portfolios but prefer not to liquidate assets to purchase real estate.
Select lending programs may consider structures involving financial assets.
Depending on the program, this can potentially include:
- Asset depletion
- Pledged assets
- Securities-backed relationships
- Significant verified liquidity
- Investment-account assets
- Other eligible financial resources
These structures are highly lender-specific.
A large asset portfolio does not automatically guarantee mortgage approval.
Fixed Rate vs. ARM for a $30 Million Mortgage
Super jumbo borrowers may encounter both fixed-rate and adjustable-rate mortgage structures.
An ARM may be worth evaluating when the borrower expects to hold the financing for a defined period or has a broader liquidity strategy.
Potential structures can include intermediate-term adjustable-rate mortgages, subject to program availability.
The correct structure depends on the borrower's objectives, expected holding period, interest-rate risk and financial plan.
$30 Million Mortgage vs. Paying Cash
A borrower capable of purchasing a $40 million, $50 million or $60 million property with cash may still choose financing.
Why?
Because committing tens of millions of dollars to real estate has an opportunity cost.
A qualified borrower may prefer to maintain capital for:
- Business investments
- Securities
- Private equity
- Real estate investments
- Acquisitions
- Liquidity
- Estate planning
- Other financial objectives
Financing can preserve liquidity, although it also creates interest expense, fees and financial risk.
Borrowers should evaluate mortgage financing with their financial, tax and legal advisers when appropriate.
Investment Property Financing and DSCR Loans
A $30 million mortgage for an investment property is a very different transaction from a $30 million mortgage on a primary residence.
Investment-property underwriting may involve rental income, leases, property cash flow and business-purpose lending requirements.
For smaller or qualifying investment-property transactions where property cash flow is central to qualification, explore the UtahLowRate.com DSCR resource center:
DSCR Mortgage Loans Utah — main guide to rental-property financing.
DSCR Loan Requirements Utah — credit, LTV, reserves, property and qualification requirements.
DSCR Loan Rates Utah — factors affecting DSCR mortgage pricing.
DSCR Loan Calculator Utah — estimate debt service coverage ratio.
DSCR Loan FAQ Utah — answers to common investor questions.
DSCR Loans Salt Lake City Utah — rental-property financing in Salt Lake County.
DSCR Loans Park City Utah — investment-property financing for Park City and Summit County.
DSCR Loans St. George Utah — DSCR financing for Washington County investors.
DSCR availability should not be assumed for a $30 million transaction. Maximum loan amounts and underwriting vary significantly by investor.
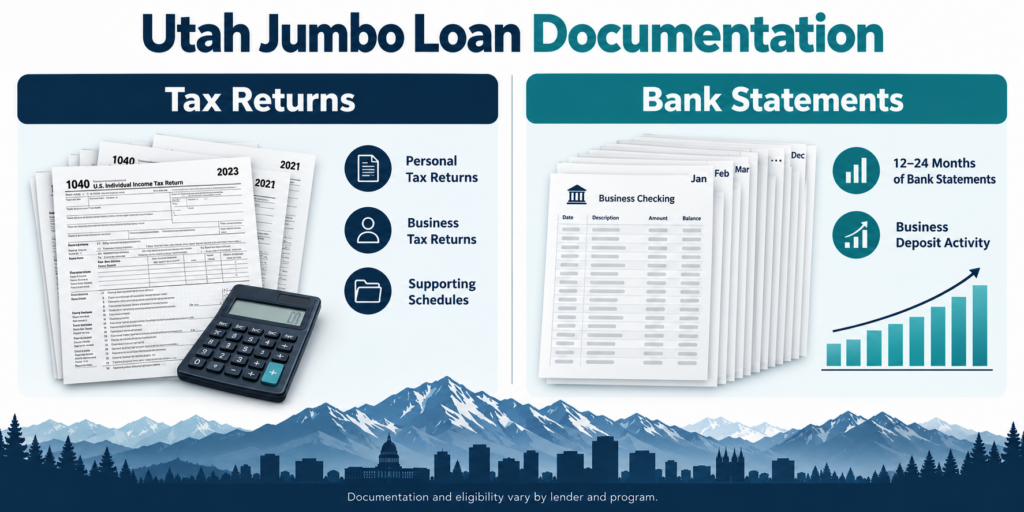
Documents That May Be Required
Documentation for a $30 million mortgage can be extensive.
Depending on the program, borrowers may be asked for:
- Personal financial statements
- Bank statements
- Brokerage statements
- Investment-account statements
- Tax returns
- W-2s or other income records
- Business financial statements
- K-1s
- Corporate or partnership documents
- Real estate schedules
- Existing mortgage statements
- Purchase contract
- Insurance information
- Entity or trust documents
- Documentation of reserves
- Source-of-funds documentation
The exact documentation depends on the selected lending program.
How to Prepare for a $30 Million Mortgage
Step 1 — Define the Transaction
Identify the property, estimated value or purchase price, occupancy and requested mortgage amount.
Step 2 — Calculate the Proposed LTV
Determine how much equity or down payment will be available.
Step 3 — Review the Borrower's Financial Profile
Evaluate income, assets, liabilities, liquidity, net worth and credit.
Step 4 — Determine the Best Documentation Method
Traditional income documentation may work well for one borrower while asset-based or alternative documentation may fit another.
Step 5 — Compare Super Jumbo Programs
Large mortgage transactions can vary considerably between lending sources.
Step 6 — Prepare for Property Review
Exceptionally valuable properties can require detailed appraisal and collateral analysis.
Step 7 — Complete Underwriting
The lender reviews the complete borrower and property file before issuing final approval.
Why Work With a Mortgage Broker on a $30 Million Loan?
At this loan size, lender selection matters.
A traditional retail bank may have one set of portfolio guidelines.
Another lender may have a different maximum loan amount, LTV requirement, liquidity test, reserve calculation or documentation approach.
A mortgage broker can help evaluate available lending sources based on the specific transaction rather than assuming one lender fits every borrower.
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified borrowers seeking jumbo, super jumbo, self-employed and alternative-documentation mortgage solutions.
Related Utah Jumbo and Super Jumbo Mortgage Resources
Continue researching your financing options:
- Super Jumbo Mortgage Loans Utah & California
- Jumbo Mortgage Utah
- Jumbo Purchase Loans Utah
- Jumbo Refinance Loans Utah
- Jumbo Cash-Out Refinance Utah
- Jumbo Second Home Loans Utah
- Jumbo Investment Property Loans Utah
- Jumbo Loans for Self-Employed Borrowers Utah
- Jumbo Bank Statement Loans Utah
- $2 Million Mortgage Loans Utah
- $5 Million Mortgage Loans Utah
- $10 Million Mortgage Loans Utah
- $20 Million Mortgage Loans Utah
These supporting resources help users and search engines understand the relationship between standard jumbo financing and increasingly specialized super jumbo transactions.
Frequently Asked Questions About $30 Million Mortgage Loans Utah
Can I get a $30 million mortgage in Utah?
Potentially. Specialized super jumbo lenders may provide $30 million mortgage loans to highly qualified borrowers. Approval depends on borrower qualifications, property eligibility, LTV, income, assets, liquidity, reserves, credit and lender guidelines.
What is the down payment on a $30 million mortgage?
There is no universal down-payment requirement. Required equity depends on the maximum LTV available for the specific borrower, property, occupancy and lending program.
Can I get a $30 million mortgage in Park City?
Potentially. Park City and Deer Valley contain properties where super jumbo financing may be relevant. Approval remains subject to borrower qualifications, collateral review and program availability.
Are $30 million mortgages available for second homes?
Select super jumbo programs may permit second-home financing. Maximum loan amount and LTV can differ from primary-residence programs.
Can a self-employed borrower qualify for a $30 million mortgage?
Potentially. Qualification methods may include traditional income documentation or lender-specific alternatives such as bank statements, asset depletion or other approved documentation.
Can I refinance a $30 million mortgage?
Potentially. Super jumbo programs may provide rate-and-term refinancing and, under qualifying circumstances, cash-out refinancing.
Are $30 million mortgage rates higher than regular mortgage rates?
Pricing for a $30 million mortgage cannot reliably be inferred from ordinary conforming mortgage rates. Super jumbo pricing depends on the lender, market conditions, loan structure, LTV, credit, liquidity, property, occupancy and complete borrower profile.
How do I get a quote for a $30 million Utah mortgage?
Start with the requested loan amount, property value or purchase price, occupancy, approximate credit profile, income structure, available liquidity and estimated down payment or equity. Those details make it possible to identify potentially suitable super jumbo programs.
Discuss a $30 Million Mortgage in Utah
Financing a $30 million mortgage is not an ordinary residential mortgage transaction.
The combination of loan size, property value, liquidity, documentation, reserves and underwriting makes program selection especially important.
Daniel Paris helps qualified borrowers evaluate jumbo and super jumbo mortgage financing throughout Utah, including Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Heber City, Midway and St. George.
Check My $30 Million Mortgage Options
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
27+ Years of Mortgage Lending Experience
Request a confidential review of your proposed property value, mortgage amount, down payment, liquidity and financing objectives.
Mortgage programs, rates, APRs, loan amounts, LTV limits, credit requirements, reserve requirements and underwriting guidelines are subject to change without notice. Maximum program loan amounts do not constitute an offer, guarantee or commitment to lend. All financing is subject to borrower qualification, property eligibility, appraisal, lender/investor requirements and final underwriting approval.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

