
Home / Loan Programs / Bank Statement Home Equity Loans Utah: Self-Employed Guide
Last reviewed: October 12, 2026 | Daniel Paris, NMLS #243976
Quick answer: Bank statement home equity loans Utah
Some specialty home equity programs may let self-employed Utah homeowners document income using eligible bank statements. Availability must be checked with the specific lender. A home equity loan or HELOC can add a second mortgage, while cash-out refinancing replaces the first loan. Compare income rules, combined equity limits, both payments and total costs with Daniel Paris.
Check My Self-Employed Equity Options
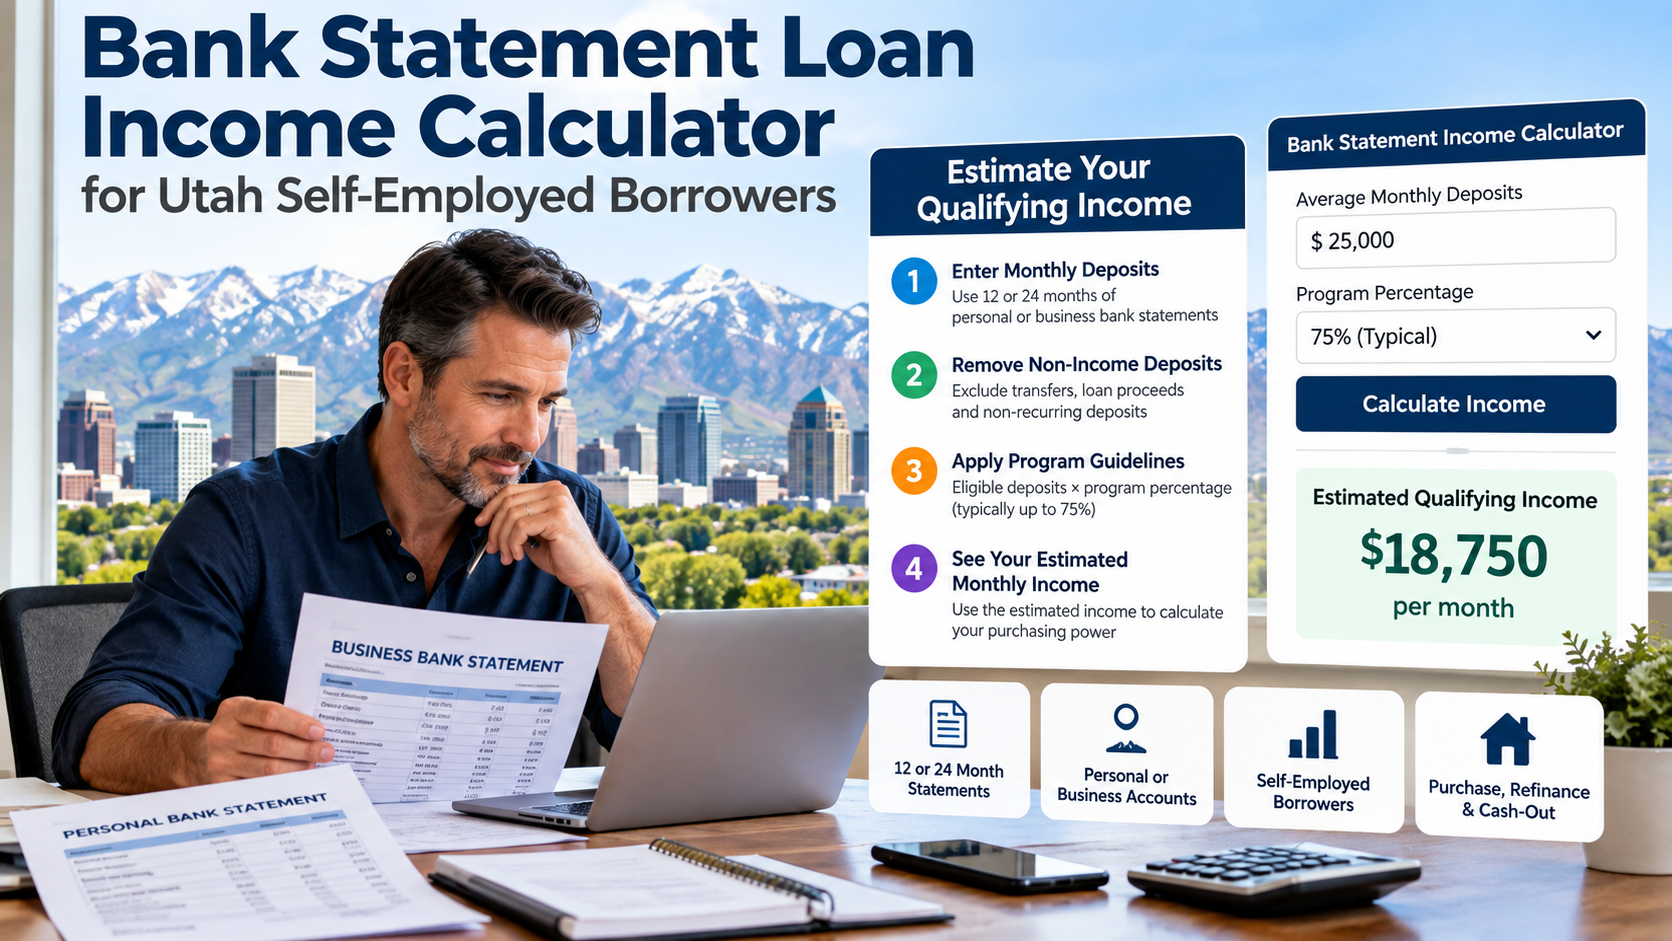
Compare self-employed home equity choices
A business owner may have strong deposits but limited taxable income after deductions. That can make traditional income documentation difficult. The first step is to identify whether an available equity product accepts alternative documents. Do not assume the rules from a bank statement purchase loan apply to a second mortgage.
| Option | Structure | Question to ask |
|---|---|---|
| Home equity loan | A separate lump-sum loan secured by the home | Does this lender accept bank statement income? |
| HELOC | A credit line with draw and repayment terms | How can the rate and future payments change? |
| Bank statement cash-out refinance | A new first mortgage replaces the old loan | What is the cost of refinancing the entire balance? |
Read our Utah HELOC guide and bank statement cash-out refinance guide. These categories solve different financing needs. A lender must confirm which options fit your property and income.
How bank statement income may be reviewed
Prepare a complete statement history and identify revenue deposits separately from transfers, borrowed money and other funds that do not represent business earnings. Business expenses and your ownership share may affect the calculation. Personal and business account methods can differ.
Use the bank statement income calculator as a planning estimate. If a first-mortgage program accepts a 12-month period or a particular expense factor, that does not establish the requirements for a second mortgage. Ask for the actual product's documentation rules before relying on an estimate.
Equity and combined loan-to-value example
Equity alone does not determine approval. The lender evaluates existing secured debt and the proposed new borrowing relative to the accepted property value. A HELOC may be assessed using its full credit limit.
Illustration: A $700,000 home with $420,000 in existing liens has $280,000 in estimated equity. Under a hypothetical 80% combined financing limit, total secured debt would be limited to $560,000. Subtracting $420,000 leaves $140,000 before costs and other restrictions. This is a math example, not an available loan offer or maximum.
Documents for a self-employed equity review
- Current mortgage and other lien statements.
- Property address, estimated value, occupancy and desired borrowing amount.
- Complete bank statements for the period requested.
- Business history, ownership and explanation of unusual deposits.
- Expense documentation where accepted or required by the lender.
- Identification, credit authorization and asset or reserve records requested for underwriting.
Use the bank statement document checklist to prepare your records. The lender may request additional documents for a second lien, property valuation or condominium review.
How to compare a second mortgage with refinancing
- Record the existing mortgage balance, rate, payment and remaining term.
- Decide how much money is needed and when it will be used.
- Ask which current programs accept your income documents and occupancy.
- Compare the first plus second payment against the proposed refinance payment.
- Review fees, future payment changes and total borrowing cost over your expected holding period.
- Confirm conditions, valuation and funding requirements before making plans around the proceeds.
Keeping an existing first-mortgage rate may be useful, but a higher-rate second lien can still increase costs. A lower refinance payment may partly reflect a longer repayment term. Compare both monthly affordability and the balance you would owe later.
Common mistakes to avoid
Do not apply Griffin Funding's or another lender's published limits to every broker or investor. Do not treat total deposits as net income. Do not combine the maximum LTV, minimum credit score and lowest rate from different programs into one assumed offer.
Your home secures the borrowing. Replacing unsecured debts with a mortgage changes the collateral risk. Tax treatment depends on the use of funds and current rules; ask your tax adviser.
Utah property and occupancy review
A primary home, vacation home and rental property may qualify under different programs. Park City condominiums can require a separate project review. A Salt Lake Valley home, Lehi new build or St. George property still needs valuation and lien review. Geographic availability alone does not establish approval.
Send Daniel Paris your scenario: property location, approximate value, lien balances, desired funds, income type and credit range. Call 801-604-4949 to compare available paths.
Consumer reference: CFPB alternatives to a HELOC.
Frequently asked questions
Can bank statements be used for a home equity loan in Utah?
Some specialty lenders accept eligible bank statements for selected second-mortgage programs. Availability must be checked separately from a first-mortgage bank statement loan.
Will I need to refinance my first mortgage?
A separate second mortgage can leave the first loan in place. A cash-out refinance replaces the first mortgage. Compare combined payments and costs.
Do all bank statement lenders offer HELOCs?
No. A lender offering bank statement purchase or refinance loans may not offer bank statement HELOCs or home equity loans.
Are deposits automatically qualifying income?
No. The lender reviews deposit sources, excludes ineligible funds and applies its approved expense and ownership calculations.
What credit score and equity are required?
There is no universal minimum for this category. Requirements depend on the available lender, documentation, occupancy, loan size and complete scenario.

