
Last reviewed: | Daniel Paris, NMLS #243976.
Estimate Qualifying Income from Personal or Business Bank Statements
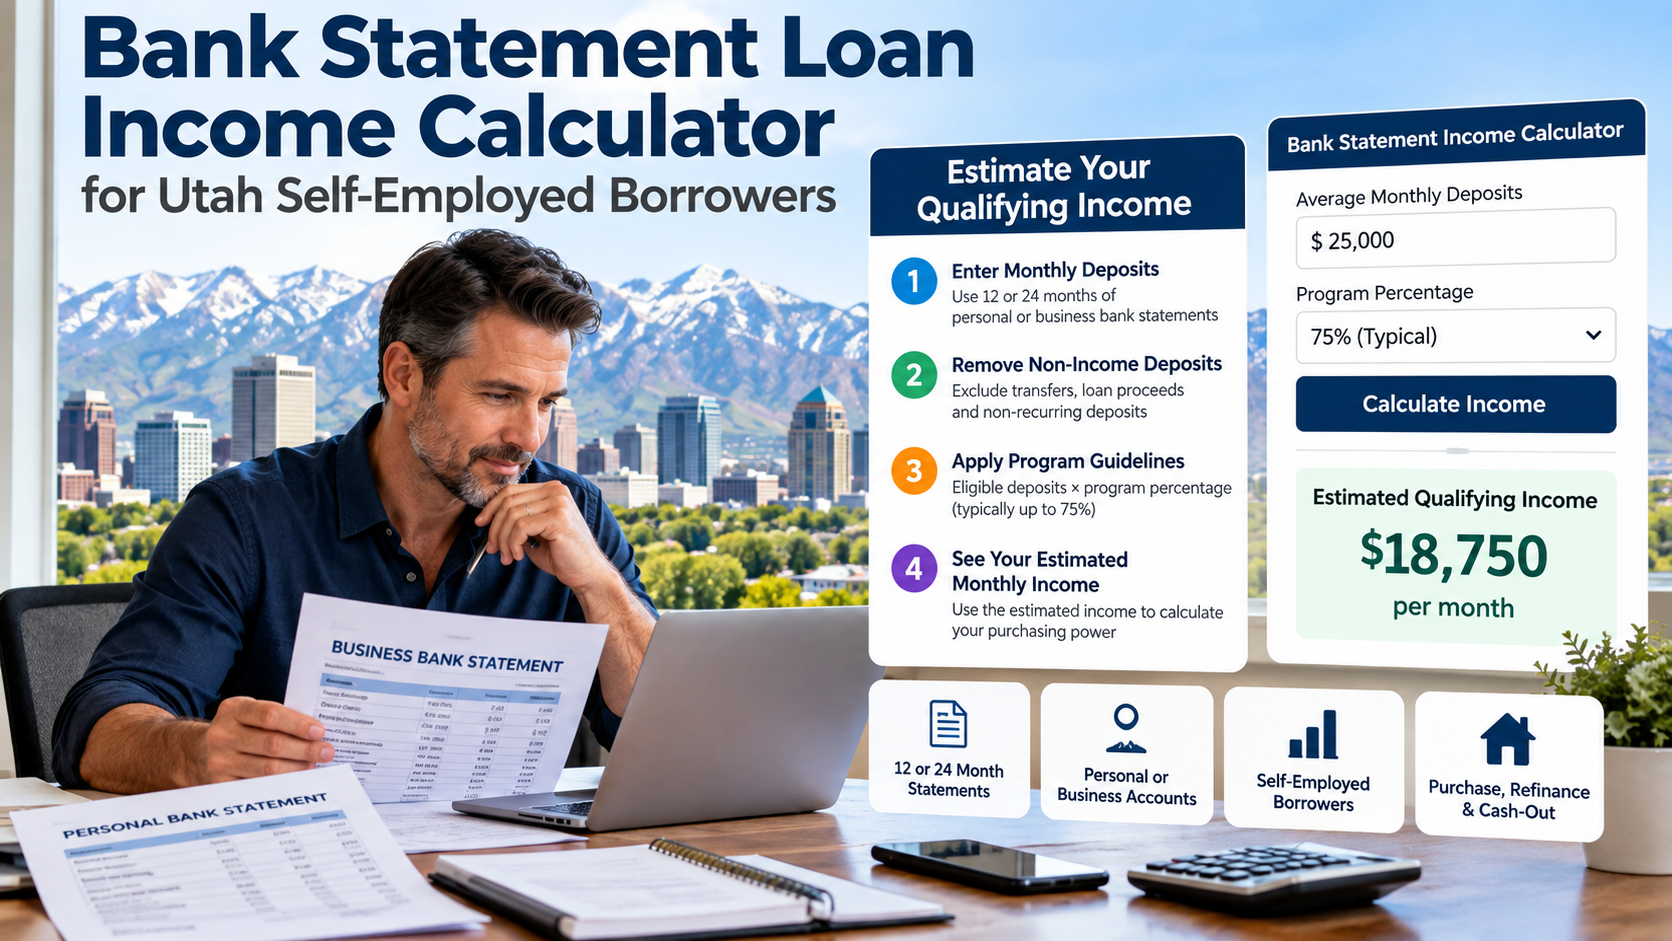
A Bank Statement Loan Income Calculator can help self-employed borrowers estimate how eligible bank deposits may translate into mortgage qualifying income. Instead of relying primarily on traditional tax-return income calculations, certain bank statement mortgage programs may review 12 or 24 months of eligible personal or business bank deposits.
The calculation is not simply total deposits divided by the number of months. Transfers, loan proceeds, refunds and other non-income deposits may need to be removed. When business bank statements are used, an applicable expense methodology may also be applied.
This guide explains how bank statement mortgage income may be calculated for qualified self-employed borrowers in Utah.
Quick Answer
A simplified bank statement loan income calculation starts by identifying eligible deposits, removing transfers and other non-income transactions, and averaging the remaining deposits over the required statement period. For business statements, the lender may then apply an approved expense methodology to estimate qualifying monthly income.
Final qualifying income is determined by the applicable lender or investor during underwriting.
Request a Bank Statement Income Review
Interactive bank statement income calculator
Enter totals for the entire statement period. This estimates income only; it does not determine mortgage approval. No information is submitted.
Expense factors and ownership treatment require lender approval. Personal-statement programs may use a different method. This calculator assumes one uniform approved business expense factor and ownership adjustment.
Bank Statement Loan Income Calculator: Quick Formula
A simplified calculation may look like this:
Simplified Bank Statement Income Formula
Eligible Deposits ÷ Number of Statement Months = Average Eligible Monthly Deposits
Average Eligible Monthly Deposits × Applicable Qualifying Percentage = Estimated Monthly Qualifying Income
Example:
$480,000 eligible annual deposits ÷ 12 months = $40,000 average monthly deposits
$40,000 × 50% = $20,000 estimated monthly qualifying income
Request a Bank Statement Income Review
The applicable calculation can vary substantially between mortgage programs. Do not assume that a particular percentage of deposits will automatically qualify.
Bank Statement Income Calculation at a Glance
| Step | What Happens |
|---|---|
| 1. Gather statements | Review the required 12 or 24 months of eligible statements |
| 2. Identify deposits | Determine which deposits may represent recurring qualifying income |
| 3. Remove transfers | Identify transfers between accounts so funds are not counted twice |
| 4. Remove non-income deposits | Exclude applicable loan proceeds, refunds or other non-income transactions |
| 5. Calculate the monthly average | Divide eligible deposits by the applicable number of months |
| 6. Apply expense methodology | For applicable business statements, account for permitted business expenses |
| 7. Determine estimated income | Calculate preliminary monthly qualifying income under the program |
| 8. Complete underwriting | Lender verifies the final calculation and all other mortgage requirements |
Bank statement income analysis is only one part of mortgage qualification. Credit, assets, reserves, debts, loan-to-value, occupancy, property type and other underwriting requirements can also affect eligibility.
How Do Bank Statement Loans Calculate Income?
A bank statement mortgage may allow a qualifying self-employed borrower to establish income using eligible deposits instead of relying primarily on the taxable income reported on traditional tax returns.
The general process starts with the bank statements required by the selected mortgage program.
The lender or underwriter may evaluate:
- recurring deposits;
- the source of deposits;
- transfers between accounts;
- unusual or one-time deposits;
- refunds and reimbursements;
- loan proceeds;
- personal versus business accounts;
- business operating expenses; and
- income trends during the review period.
After applicable non-income transactions are removed, eligible deposits may be averaged over the required statement period.
When business bank statements are used, an approved expense methodology may then be applied because gross business revenue is not necessarily the same as the business owner's qualifying personal income.
For a broader explanation of these programs, see our Bank Statement Loans Utah guide.
Example 1: Bank Statement Income With a 50% Expense Factor
Assume a self-employed borrower has:
- $480,000 in eligible business deposits for 12 months;
- no duplicate transfers included in that total; and
- a program that permits a 50% qualifying percentage after the applicable expense analysis.
Step 1: Calculate Average Monthly Deposits
$480,000 ÷ 12 = $40,000 per month
Step 2: Apply the Example Percentage
$40,000 × 50% = $20,000 per month
The preliminary estimated qualifying income would therefore be $20,000 per month under this simplified example.
That does not mean every borrower or business receives a 50% expense factor. Actual treatment depends on the mortgage program and supporting documentation.
Example 2: When a Different Expense Method Produces a 75% Result
Assume another business produces average eligible monthly deposits of $40,000.
The qualifying percentage depends on the lender-approved expense calculation, business structure and supporting records. Any percentage shown here is hypothetical and must be verified for the selected program.
$40,000 × 75% = $30,000 per month
The estimated qualifying income would be $30,000 per month.
This example demonstrates why the business-expense methodology can materially affect mortgage qualification.
A 75% calculation should not be treated as a universal bank statement loan rule. The applicable percentage or expense methodology must be supported by the selected program.
Example 3: Why Transfers Must Be Identified
Suppose a business owner receives $25,000 in customer revenue and then transfers $15,000 of those funds from one business account into another account.
If both transactions were treated as new income, the analysis could incorrectly show:
$25,000 + $15,000 = $40,000
But the $15,000 transfer may simply represent movement of money that was already counted.
The actual new revenue in this simplified example remains $25,000.
Identifying transfers helps prevent the same income from being counted twice.
Example 4: 12-Month Bank Statement Income Calculation
Assume a borrower provides 12 months of eligible business bank statements.
Total deposits during the period:
$720,000
Identified transfers and applicable non-income deposits:
$60,000
Remaining eligible deposits:
$720,000 − $60,000 = $660,000
Average eligible monthly deposits:
$660,000 ÷ 12 = $55,000
If the applicable program's expense methodology results in 50% being treated as qualifying income:
$55,000 × 50% = $27,500 estimated monthly qualifying income
This is an educational example. Actual underwriting calculations may differ.
Example 5: 24-Month Bank Statement Income Calculation
Now assume a borrower provides 24 months of eligible statements.
Total deposits:
$1,200,000
Transfers and applicable non-income deposits:
$120,000
Remaining eligible deposits:
$1,200,000 − $120,000 = $1,080,000
Average eligible monthly deposits:
$1,080,000 ÷ 24 = $45,000
If the applicable expense methodology results in 50% being treated as qualifying income:
$45,000 × 50% = $22,500 estimated monthly qualifying income
A longer review period can produce a different average because it captures more of the borrower's business history.
12-Month vs. 24-Month Bank Statement Calculations
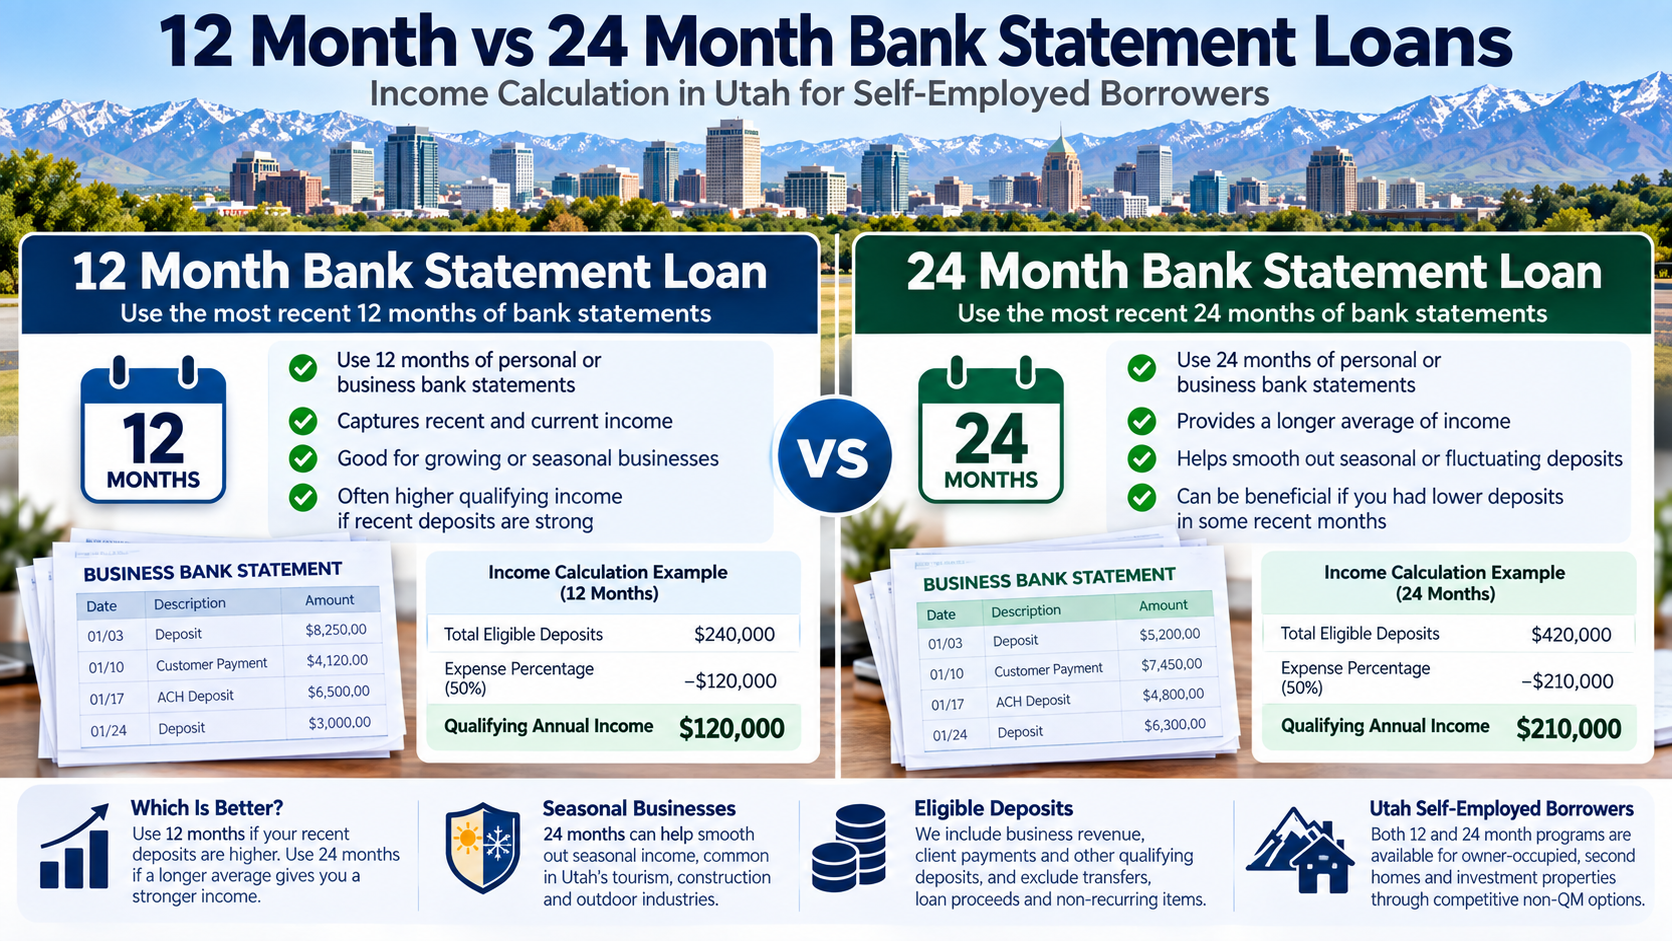
Many bank statement mortgage programs review approximately 12 or 24 months of statements.
Neither period is automatically better.
12-Month Bank Statement Review
Certain programs may permit approximately 12 months of statements.
A shorter period may provide a more recent picture of the business, but eligibility and the treatment of income trends depend on the applicable program.
24-Month Bank Statement Review
Other programs may use approximately 24 months.
A longer review can provide a broader picture of deposits and may help an underwriter evaluate businesses with variable or seasonal revenue.
Which Is Better?
The appropriate statement period may depend on:
- business history;
- income trends;
- seasonality;
- account structure;
- loan amount;
- credit profile;
- occupancy;
- property type; and
- investor requirements.
The statement period is only one qualification requirement. Review our Bank Statement Loan Requirements guide for additional information about documentation, credit, reserves, property eligibility and other underwriting considerations.
What Counts as an Eligible Bank Statement Deposit?
Not every deposit appearing on a bank statement should automatically be considered qualifying income.
Potential eligible deposits may include recurring business revenue or other qualifying self-employment receipts that can be appropriately documented under the applicable program.
Transactions that may require additional review or exclusion can include:
- transfers between accounts;
- loan proceeds;
- refunds;
- reimbursements;
- returned funds;
- one-time non-business deposits;
- proceeds from asset sales; and
- other deposits that do not represent qualifying recurring income.
The exact treatment depends on the applicable lender or investor guidelines.
This is one reason a preliminary deposit review can be more useful than simply adding every deposit appearing on the statements.
Personal vs. Business Bank Statement Income
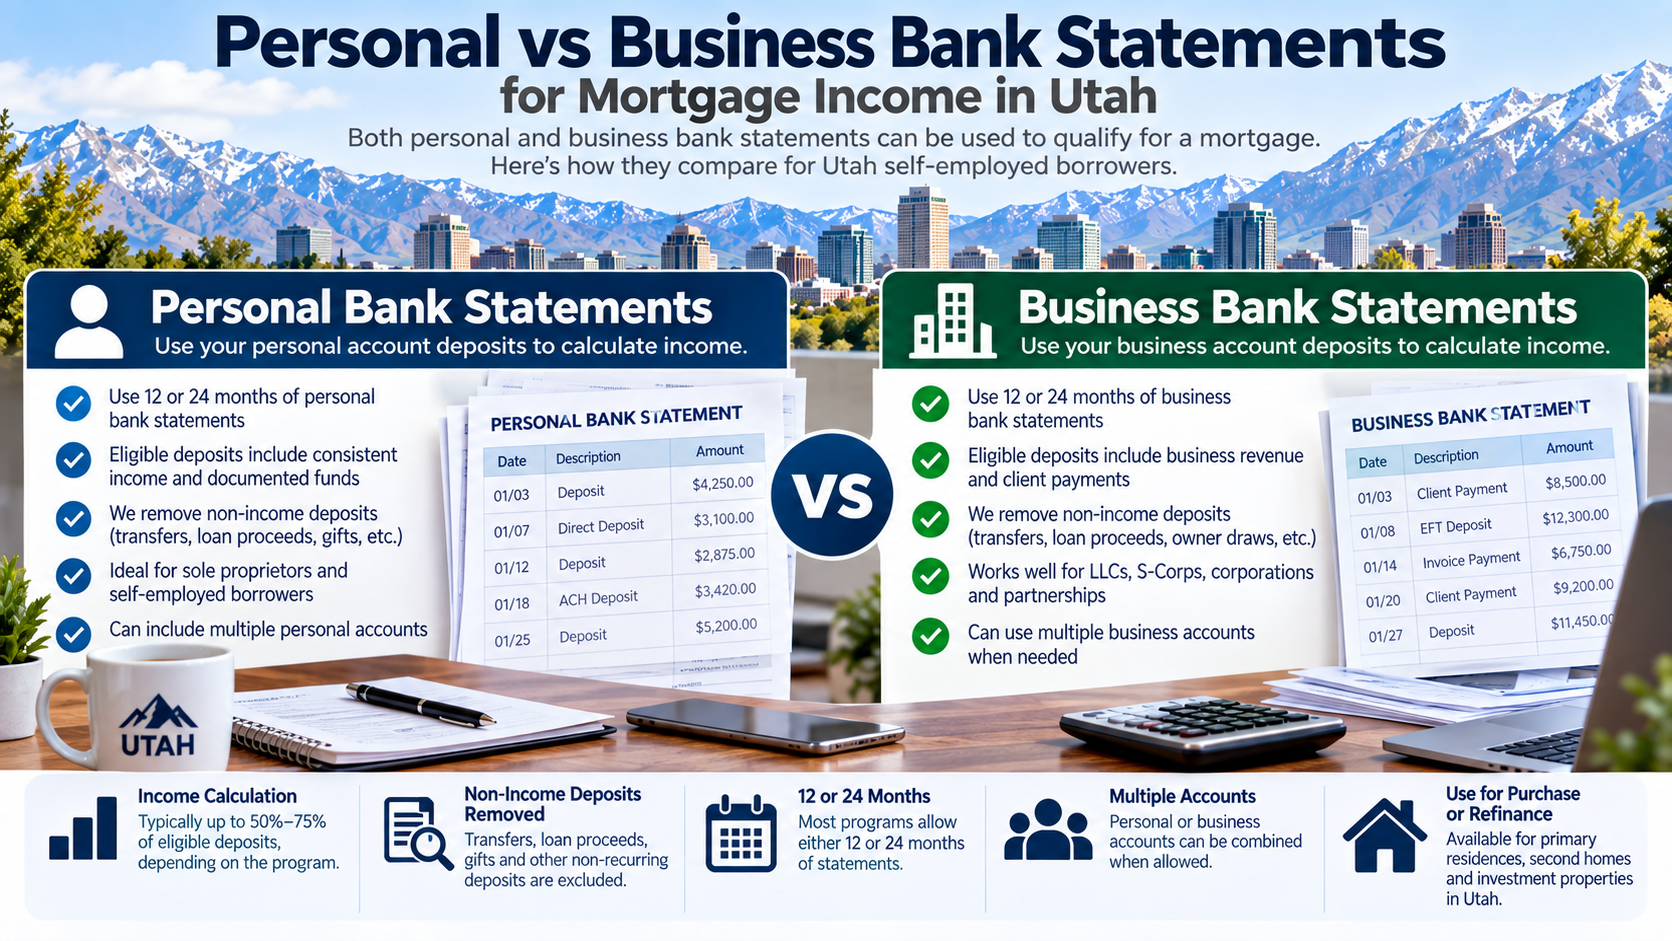
Self-employed borrowers do not all manage their income in the same way.
Some deposit self-employment income directly into personal accounts. Others operate primarily through business accounts.
Depending on the mortgage program, either structure may be considered.
Personal Bank Statements
Certain mortgage programs may permit personal bank statements when qualifying self-employment income is regularly deposited into the borrower's personal account.
The analysis may involve identifying recurring qualifying deposits and excluding transfers and applicable non-income transactions.
The lender will also evaluate the source and consistency of deposits according to its program requirements.
Business Bank Statements
Business statements may be considered when most operating revenue flows through a company account.
Business statements require special attention because:
gross business deposits do not necessarily equal the business owner's personal qualifying income.
Businesses have expenses.
The lender or investor may therefore apply an approved expense methodology when converting eligible business deposits into estimated qualifying income.
Can Multiple Accounts Be Used?
Potentially.
Some business owners maintain multiple operating, savings or personal accounts.
Whether multiple accounts may be included depends on the program and the relationship between the accounts.
Transfers must be identified carefully so the same funds are not counted more than once.
Why the Business Expense Factor Matters
The expense methodology can be one of the most important parts of a business bank statement income calculation.
Consider two borrowers who each have average eligible monthly business deposits of $40,000.
If one applicable calculation results in 50% of eligible deposits being treated as income:
$40,000 × 50% = $20,000
The qualifying percentage depends on the lender-approved expense calculation, business structure and supporting records. Any percentage shown here is hypothetical and must be verified for the selected program.
$40,000 × 75% = $30,000
That is a $10,000 monthly difference in estimated qualifying income.
This does not mean borrowers can simply choose the percentage that produces the highest income. The methodology must comply with the applicable lender or investor requirements and may require supporting documentation.
Learn more about how bank statement loans work in Utah before relying on a preliminary calculation.
Why Working With a Mortgage Broker Can Matter
Bank statement mortgage programs are not standardized across every lender or investor.
Different programs may have different requirements for:
- 12 versus 24 months of statements;
- personal versus business accounts;
- business expense calculations;
- self-employment history;
- credit scores;
- loan-to-value ratios;
- mortgage reserves;
- loan amounts;
- occupancy;
- property types; and
- jumbo financing.
As a mortgage broker, Daniel Paris can compare available wholesale mortgage programs rather than limiting the review to one bank's bank statement product.
The goal is not simply to find a lender that offers a bank statement mortgage. It is to determine which available program appropriately fits the borrower's income structure, property and overall financial profile.
Can I Calculate My Own Bank Statement Mortgage Income?
You can create a useful preliminary estimate.
Start by gathering the required statement period and then:
- total potentially eligible deposits;
- identify transfers between accounts;
- remove applicable non-income deposits;
- calculate remaining eligible deposits;
- divide by the number of statement months; and
- apply the expense methodology permitted by the potential mortgage program.
That can provide a preliminary estimate.
It is not a mortgage approval or final underwriting calculation.
The lender must determine which deposits are eligible and which expense methodology applies.
Does Bank Statement Income Determine How Much House I Can Buy?
No.
Estimated bank statement income is only one part of mortgage qualification.
An underwriter may also evaluate:
- monthly liabilities;
- credit score and credit history;
- down payment;
- loan-to-value ratio;
- assets;
- mortgage reserves;
- property type;
- occupancy;
- loan amount;
- appraisal;
- housing history; and
- other lender or investor requirements.
A borrower with substantial calculated income may still be limited by another underwriting factor.
Likewise, two borrowers with identical bank statement income may qualify differently because their credit, debts, down payments, reserves or properties differ.
Bank Statement Loan Calculator Worksheet
Use this worksheet to organize a preliminary calculation.
| Calculation | Amount |
|---|---|
| Total deposits during statement period | $________ |
| Less identified transfers | − $________ |
| Less applicable non-income deposits | − $________ |
| Estimated eligible deposits | $________ |
| Number of statement months | 12 / 24 |
| Average eligible monthly deposits | $________ |
| Applicable qualifying percentage / expense methodology | ________ |
| Estimated monthly qualifying income | $________ |
Important: This worksheet is educational and is not an underwriting decision. Do not assume that every deposit qualifies or that a specific expense percentage will apply to your mortgage program.
Want Your Bank Statement Income Calculated?
A preliminary bank statement review can help estimate how eligible personal or business deposits may translate into mortgage qualifying income before you apply.
Daniel Paris — Utah Mortgage Broker
NMLS #243976
801-604-4949
Request a Bank Statement Income Review
Bank Statement Loan Income Calculator for Utah Borrowers
Bank statement financing can be useful for qualified Utah borrowers whose businesses generate consistent cash flow but whose traditional tax-return income does not fully represent their current financial profile.
UtahLowRate.com works with qualifying self-employed borrowers throughout Utah, including Salt Lake City, Park City, Heber City, St. George, Lehi, Provo, Orem, Draper, Sandy, South Jordan, Herriman, Riverton, Midway, Kamas, Washington and surrounding communities.
Local bank statement mortgage resources include:
- Bank Statement Loans Salt Lake City — bank statement mortgage information for self-employed borrowers throughout the Salt Lake Valley.
- Bank Statement Loans Park City Utah — bank statement and jumbo mortgage information for Park City, Deer Valley and surrounding Summit County communities.
- Bank Statement Loans Heber City Utah — alternative-documentation mortgage information for Heber City and the Wasatch Back.
- Bank Statement Loans St. George Utah — bank statement mortgage options for St. George and Southern Utah.
- Bank Statement Loans Utah County & Lehi — information for Lehi, Provo, Orem and surrounding Utah County communities.
Jumbo Bank Statement Income Calculations
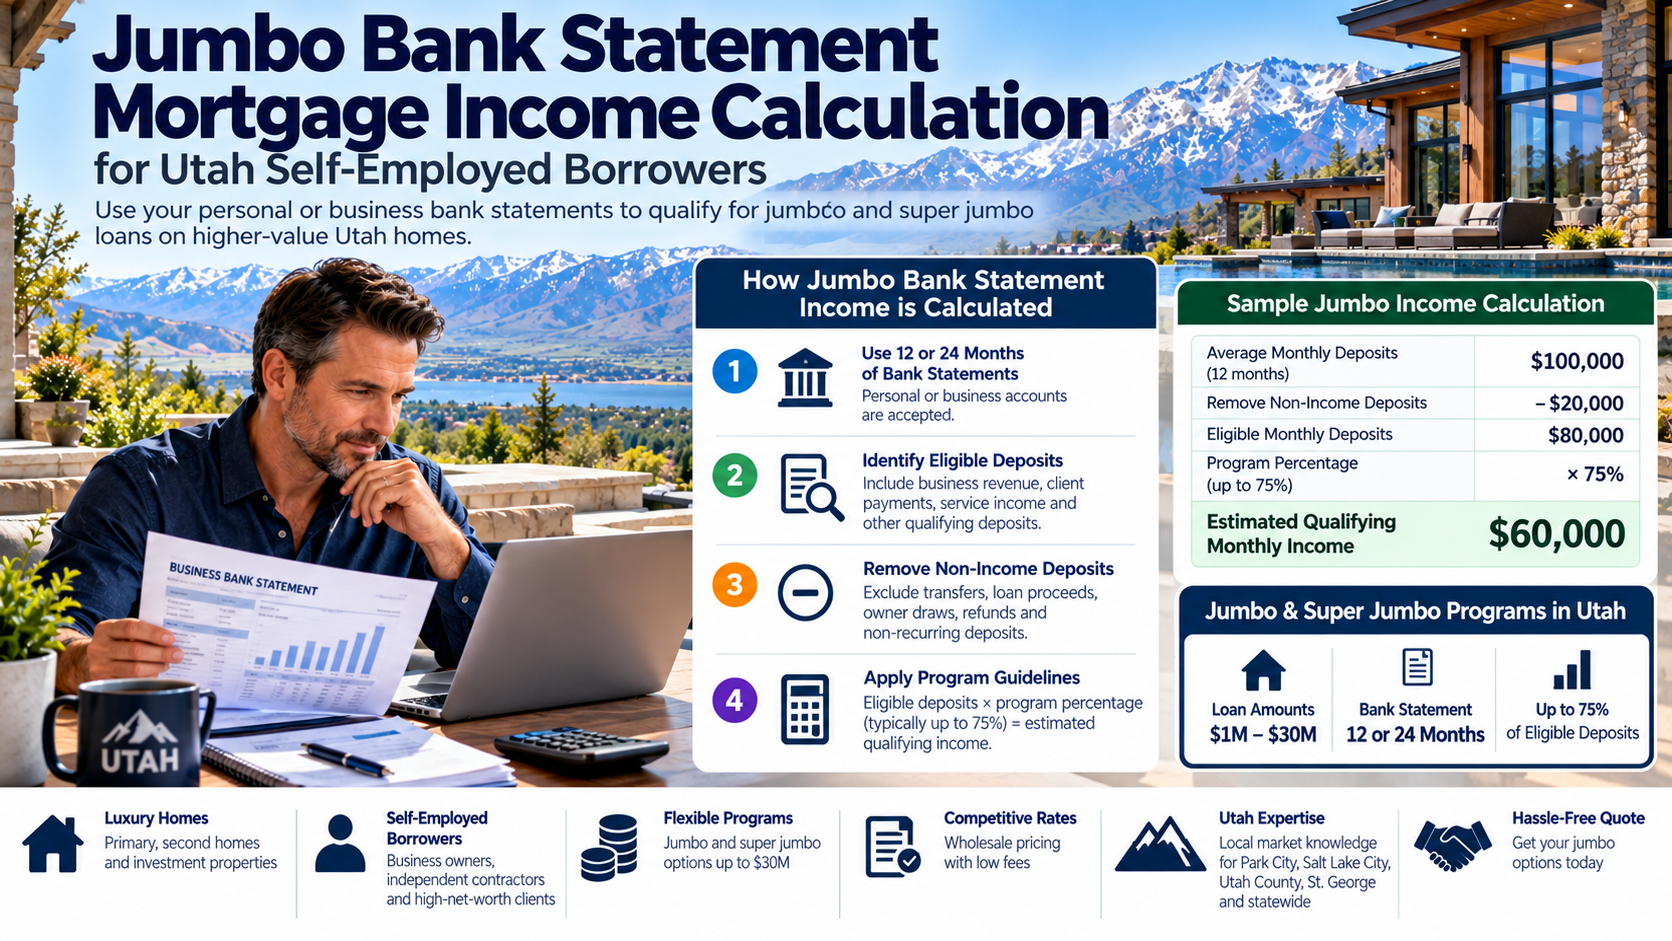
Self-employed borrowers financing higher-value Utah properties may also have access to select jumbo bank statement mortgage programs.
The basic concept remains similar: eligible deposits may be analyzed to establish qualifying income.
However, larger loan amounts can involve additional underwriting considerations, including:
- greater reserve requirements;
- lower maximum LTVs under certain programs;
- liquidity requirements;
- credit requirements;
- property valuation;
- occupancy;
- business history; and
- overall financial strength.
For larger mortgage amounts, review Jumbo Bank Statement Loans Utah for additional information about alternative-documentation jumbo financing.
Explore Utah Bank Statement Loan Resources
Bank Statement Loans Utah
Start with the statewide bank statement mortgage guide.
Bank Statement Loan Requirements
Review documentation, deposits, credit, reserves and qualification requirements.
Bank Statement Loan FAQ
Get answers to common bank statement mortgage questions.
Jumbo Bank Statement Loans Utah
Explore larger bank statement mortgage options for qualified self-employed borrowers.
Bank Statement Loans Salt Lake City
Self-employed mortgage information for the Salt Lake Valley.
Bank Statement Loans Park City Utah
Bank statement and jumbo financing information for Park City and surrounding communities.
Bank Statement Loans Heber City Utah
Alternative-documentation financing information for Heber City and the Wasatch Back.
Bank Statement Loans St. George Utah
Bank statement mortgage information for Southern Utah.
Bank Statement Loans Utah County & Lehi
Self-employed mortgage information for Lehi, Provo, Orem and Utah County.
Bank Statement Loan Income Calculator FAQ
For more questions about documentation, tax returns, self-employment history, personal versus business statements and loan eligibility, visit the Bank Statement Loan FAQ.
How is income calculated for a bank statement loan?
A lender may review eligible deposits over the required statement period, remove transfers and applicable non-income transactions, calculate average eligible monthly deposits and apply the permitted expense methodology when required. Exact calculations vary by lender and investor.
Can 100% of my bank deposits be used as mortgage income?
Do not assume that 100% of deposits will qualify. Business accounts can contain gross revenue, transfers and other transactions that do not represent personal qualifying income. Applicable business expenses may also need to be considered.
Can 75% of business bank statement deposits be used?
Certain program methodologies may produce a calculation in which approximately 75% of eligible deposits is recognized as qualifying income. It is not a universal rule. The calculation depends on the program, business, account structure and required documentation.
Do transfers count as income on a bank statement loan?
Transfers generally do not represent new revenue. They may need to be identified and excluded so the same funds are not counted more than once.
Are 12 months or 24 months of bank statements better?
Neither is automatically better. Program requirements, business history, income trends and seasonality can affect which statement period is appropriate.
Can I use personal bank statements instead of business statements?
Certain programs permit eligible personal statements, while others permit business statements. The documentation and income calculation can differ between the two approaches.
Do bank statement loans require tax returns?
Certain bank statement mortgage programs are designed to establish qualifying income using eligible bank deposits rather than relying primarily on traditional tax-return income calculations. Other documentation and complete underwriting requirements still apply.
Does calculated bank statement income determine my maximum mortgage amount?
No. Qualifying income is one component of underwriting. Credit, debts, assets, reserves, loan-to-value, occupancy, property type and other requirements can also affect the amount for which a borrower qualifies.
Can bank statement income be used for a jumbo mortgage?
Select investors offer jumbo bank statement programs for qualified self-employed borrowers. Maximum loan amounts, credit requirements, LTVs and reserves vary by program.
Are bank statement loans the same as no-documentation mortgages?
No. Bank statement mortgages use alternative income documentation but still require underwriting and supporting borrower, asset, credit and property documentation.
Request a Bank Statement Income Review in Utah
If you are self-employed and want to know how your personal or business bank statements may translate into mortgage qualifying income, a preliminary review can help identify potential eligible deposits, transfers and the documentation structure that may apply.
Daniel Paris | UtahLowRate.com
Utah Mortgage Broker
NMLS #243976
Call: 801-604-4949
Request a Bank Statement Income Review
Important Mortgage Disclosure
Bank statement mortgage programs, interest rates, terms, loan amounts, credit requirements, loan-to-value limits, expense methodologies, reserve requirements and underwriting guidelines vary by lender and investor and are subject to change.
The formulas and calculations on this page are educational examples only. They do not represent a commitment to lend, an approval, a guaranteed income calculation or a guarantee that a particular borrower, deposit, property or transaction will qualify.
Final qualifying income and mortgage eligibility are determined through complete lender and investor underwriting.
Request a Bank Statement Income Review · Call Daniel Paris: 801-604-4949

