
Content updated: .
Bank statement mortgage options for self-employed homebuyers in Heber City and the Wasatch Back.
Bank statement loans Heber City Utah can give qualified self-employed borrowers another way to document mortgage income when tax returns do not fully reflect recurring business cash flow.
Instead of relying primarily on traditional tax-return income, certain bank statement mortgage programs may calculate qualifying income using eligible deposits from 12 or 24 months of personal or business bank statements.
These alternative-documentation mortgage programs can be useful for business owners, entrepreneurs, independent contractors and other qualified self-employed borrowers buying or refinancing homes in Heber City, Midway, Jordanelle, Hideout, Kamas and surrounding Wasatch County communities.
Daniel Paris | Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
UtahLowRate.com | NMLS #243976-3138
801-604-4949
Request a Bank Statement Income Review
Quick Answer: How Do Bank Statement Loans in Heber City Work?
A bank statement loan in Heber City, Utah may allow a qualified self-employed borrower to establish mortgage income using eligible deposits from personal or business bank statements instead of relying primarily on traditional tax-return income.
Programs commonly review 12 or 24 months of statements. Eligible deposits are analyzed, transfers and other non-income deposits are excluded, and an applicable expense methodology may be used when business statements are involved.
Bank statement mortgages are still fully underwritten loans. Credit, debts, assets, reserves, down payment or equity, property value, occupancy and other requirements apply.
For the statewide program overview, see our Bank Statement Loans Utah guide.
Bank Statement Loans Heber City Utah: Quick Facts
| Feature | General Guideline |
|---|---|
| Designed primarily for | Self-employed borrowers |
| Income documentation | Eligible recurring bank deposits |
| Statement period | Commonly 12 or 24 months |
| Personal statements | Available with qualifying programs |
| Business statements | Available with qualifying programs |
| Tax returns | May not be the primary income calculation |
| Purchase | Available with qualifying programs |
| Rate-and-term refinance | Available with qualifying programs |
| Cash-out refinance | Available with qualifying programs |
| Primary residence | Available |
| Second home | Select programs |
| Investment property | Select programs |
| Jumbo financing | Available through select investors |
| Credit requirements | Investor-specific |
| LTV | Program-specific |
| Reserves | Often required |
| Underwriting | Full lender/investor underwriting |
Important: Mortgage guidelines vary by lender and investor and can change. Loan amount, credit, LTV, reserves, income calculation, property and documentation requirements depend on the individual program and transaction.
What Is a Heber City Bank Statement Mortgage?
A bank statement mortgage is an alternative-documentation mortgage primarily designed for qualified self-employed borrowers.
Traditional mortgage underwriting may calculate self-employment income using tax returns and other standard financial documentation.
For some business owners, legitimate deductions and business expenses can reduce taxable income even though the business produces significant recurring cash flow.
A bank statement program provides another potential method for documenting income.
Depending on the mortgage program, a lender may analyze eligible deposits appearing on personal or business bank statements and apply the program's required calculation to determine qualifying monthly income.
This does not mean income is simply stated by the borrower.
The lender still documents and analyzes income, credit, assets, liabilities, reserves, property, occupancy and other underwriting factors.
For a broader explanation of these programs throughout the state, visit Bank Statement Loans Utah.
Who May Benefit From Bank Statement Loans Heber City Utah?
A self-employed Heber City borrower reviewing alternative mortgage income documentation.
A bank statement mortgage in Heber City may be worth evaluating when a self-employed borrower's traditional tax-return calculation does not accurately represent recurring business cash flow.
Potential borrowers may include:
- Business owners
- Entrepreneurs
- Independent contractors
- Consultants
- Real estate professionals
- Medical professionals
- Attorneys
- Construction company owners
- Contractors and tradespeople
- Freelancers
- Commission-based professionals
- 1099 professionals
- Other qualified self-employed borrowers
Being self-employed does not automatically mean you need a bank statement loan.
Some borrowers may qualify through conventional, FHA, VA or jumbo financing using traditional income documentation.
You can compare additional options in our Self-Employed Mortgage Utah guide.
How Bank Statement Loans Heber City Utah Work
1. Determine Whether Personal or Business Statements Should Be Used
The first step is determining which account or combination of accounts most accurately documents recurring self-employment income.
Depending on the program, personal statements, business statements or qualifying combinations may be considered.
2. Provide 12 or 24 Months of Bank Statements
Many bank statement programs analyze either 12 or 24 consecutive months.
The appropriate documentation period can depend on the investor, length of self-employment, income consistency and overall borrower profile.
3. Identify Eligible Deposits
Statements are reviewed to identify recurring deposits associated with legitimate business or self-employment income.
Not every deposit automatically becomes qualifying mortgage income.
4. Remove Transfers and Non-Income Deposits
Transfers between accounts generally do not create additional income.
Loan proceeds, refunds, reimbursements, asset-sale proceeds and other non-recurring deposits may also require review or exclusion.
5. Apply the Appropriate Business-Expense Method
When business bank statements are used, the lender generally must account for business expenses.
The methodology can differ between investors and programs.
6. Calculate Average Qualifying Income
The lender calculates qualifying monthly income based on the eligible deposits and applicable program methodology.
7. Complete Mortgage Underwriting
The lender then evaluates the complete mortgage transaction, including:
- Credit
- Existing debts
- Assets
- Reserves
- Down payment or equity
- Property value
- Appraisal
- Occupancy
- Loan-to-value ratio
- Loan amount
For a detailed underwriting checklist, see Bank Statement Loan Requirements Utah.
12-Month vs. 24-Month Bank Statement Loans
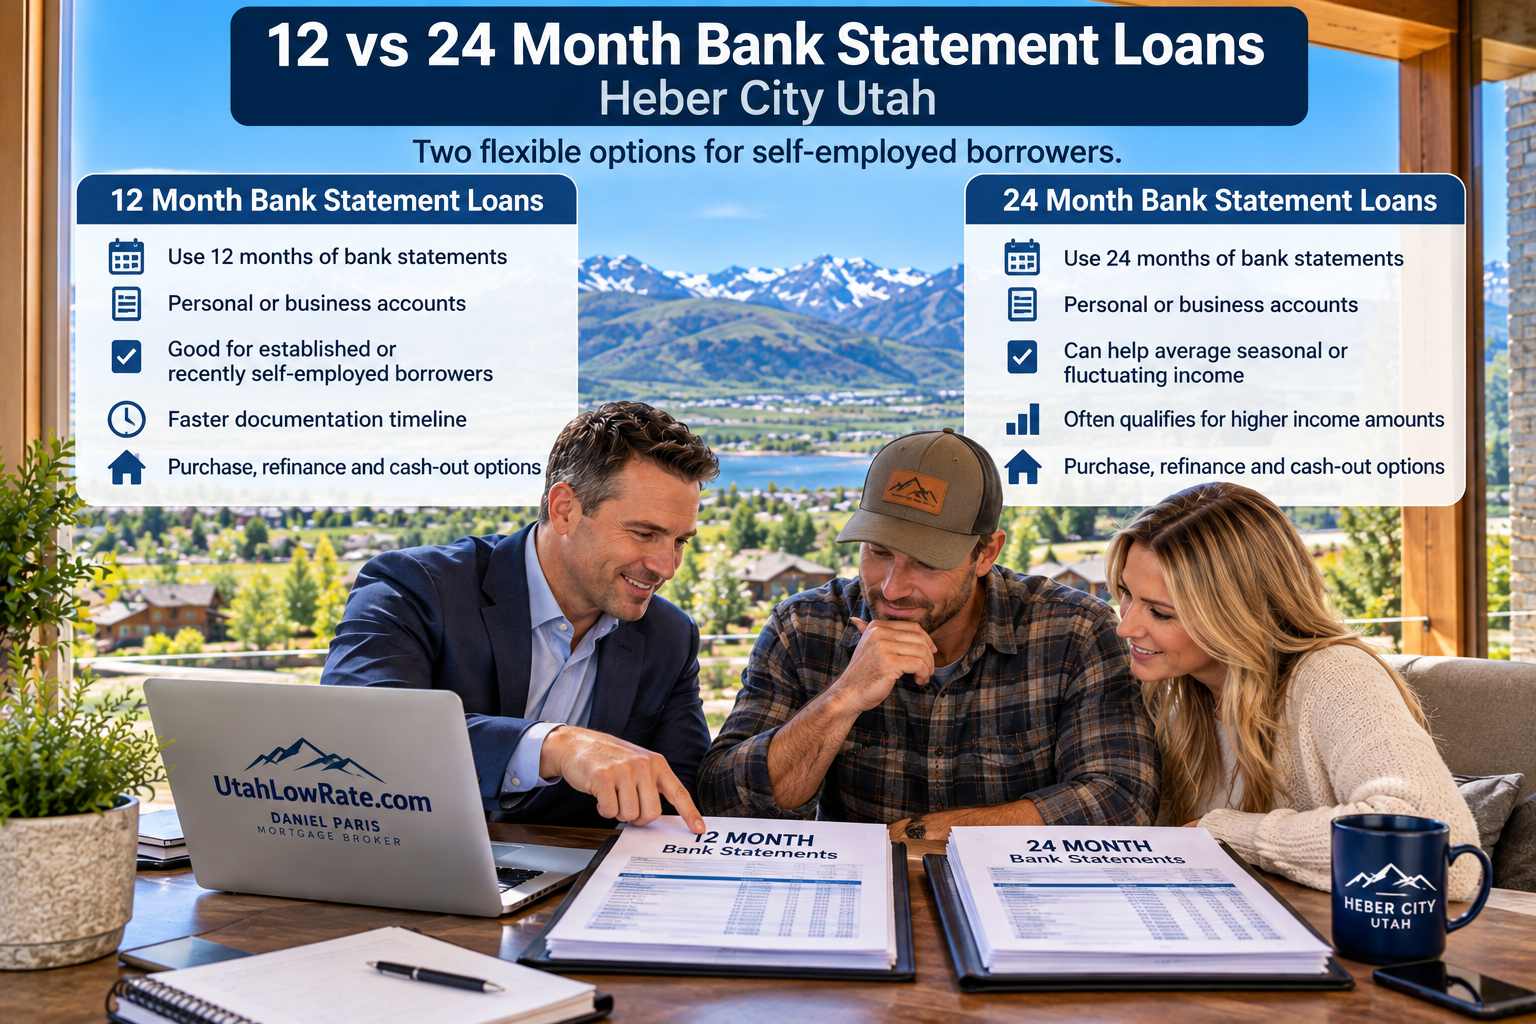
Comparing 12-month and 24-month bank statement documentation for self-employed borrowers.
12-Month Bank Statement Mortgage
Certain programs may permit approximately 12 consecutive months of bank statements.
This structure may be useful when the most recent year provides an appropriate and supportable picture of the borrower's current business income.
24-Month Bank Statement Mortgage
Other programs analyze approximately 24 months.
A longer documentation period can provide a broader view of business revenue and may help demonstrate consistency for businesses with variable or seasonal income.
Which Is Better: 12 or 24 Months?
Neither is automatically better.
The appropriate option depends on factors including:
- Length of self-employment
- Business history
- Deposit trends
- Seasonality
- Credit
- Loan amount
- LTV
- Property
- Occupancy
- Investor guidelines
Reviewing both calculations before selecting a program may help identify which documentation period fits the transaction.
Personal vs. Business Bank Statements
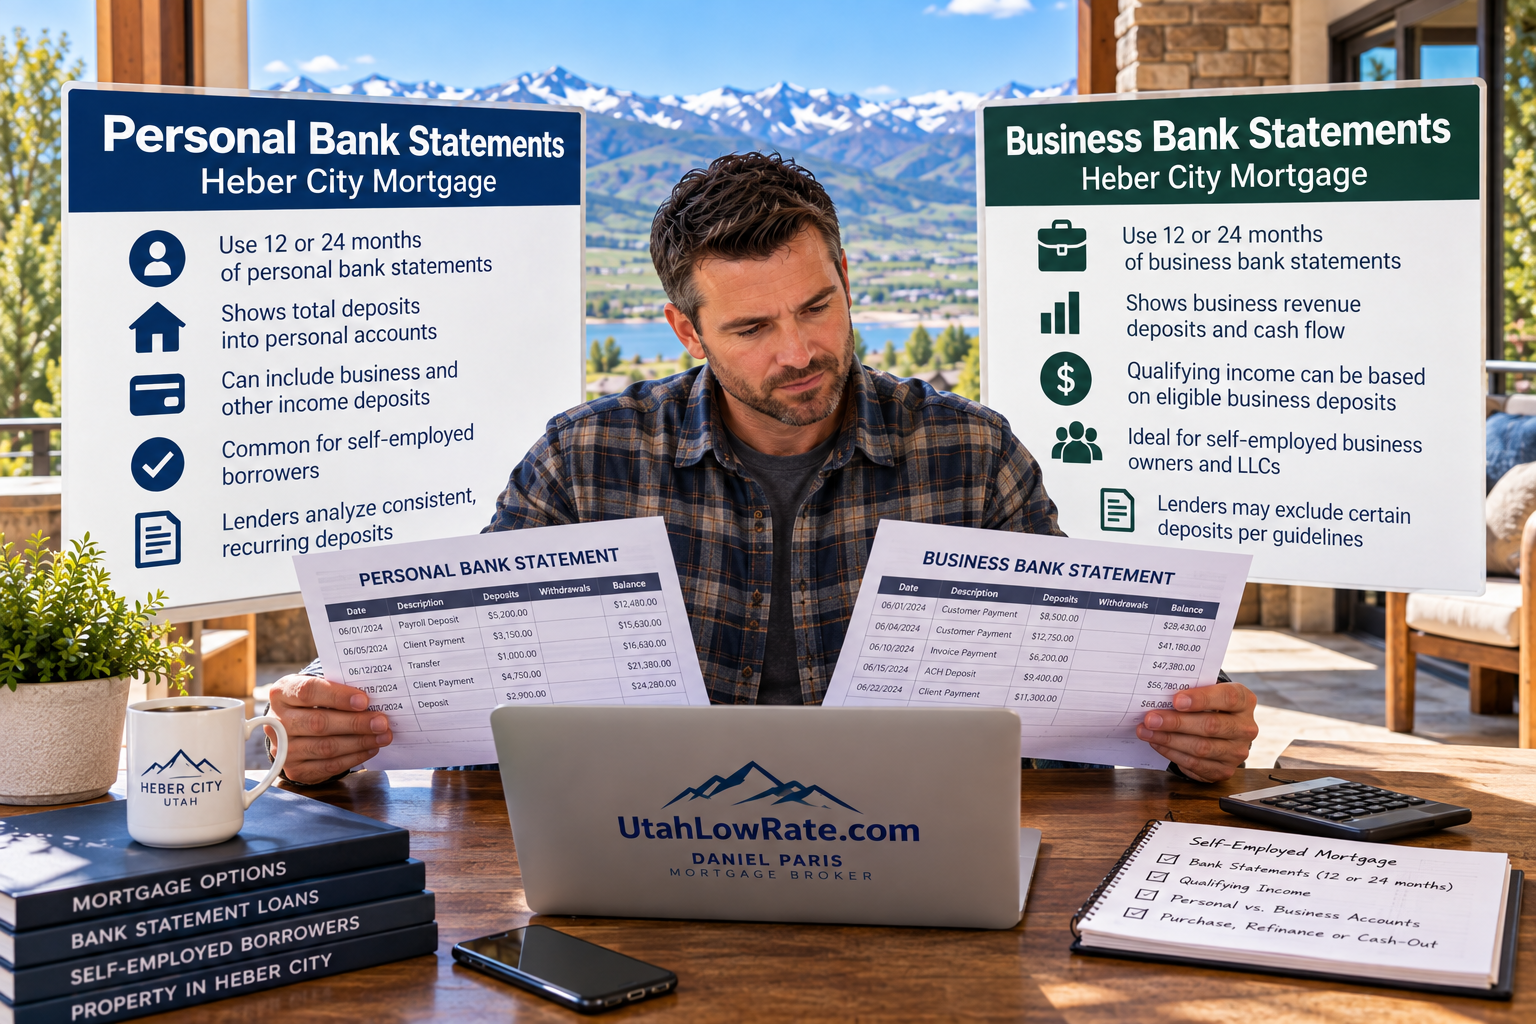
Personal and business bank statements can be evaluated differently when calculating qualifying mortgage income.
Personal Bank Statements
Certain programs permit personal statements when recurring self-employment income is deposited into a personal account.
The lender analyzes the statements and determines which deposits may qualify under the applicable program.
Business Bank Statements
Business statements may be appropriate when most company revenue flows through business accounts.
However, gross business deposits do not automatically equal qualifying personal income.
Business expenses generally must be considered using the methodology required by the selected mortgage program.
Multiple Business Accounts
Some programs may permit multiple legitimate business accounts.
Transfers between those accounts must be identified so the same revenue is not counted more than once.
How Is Bank Statement Mortgage Income Calculated?
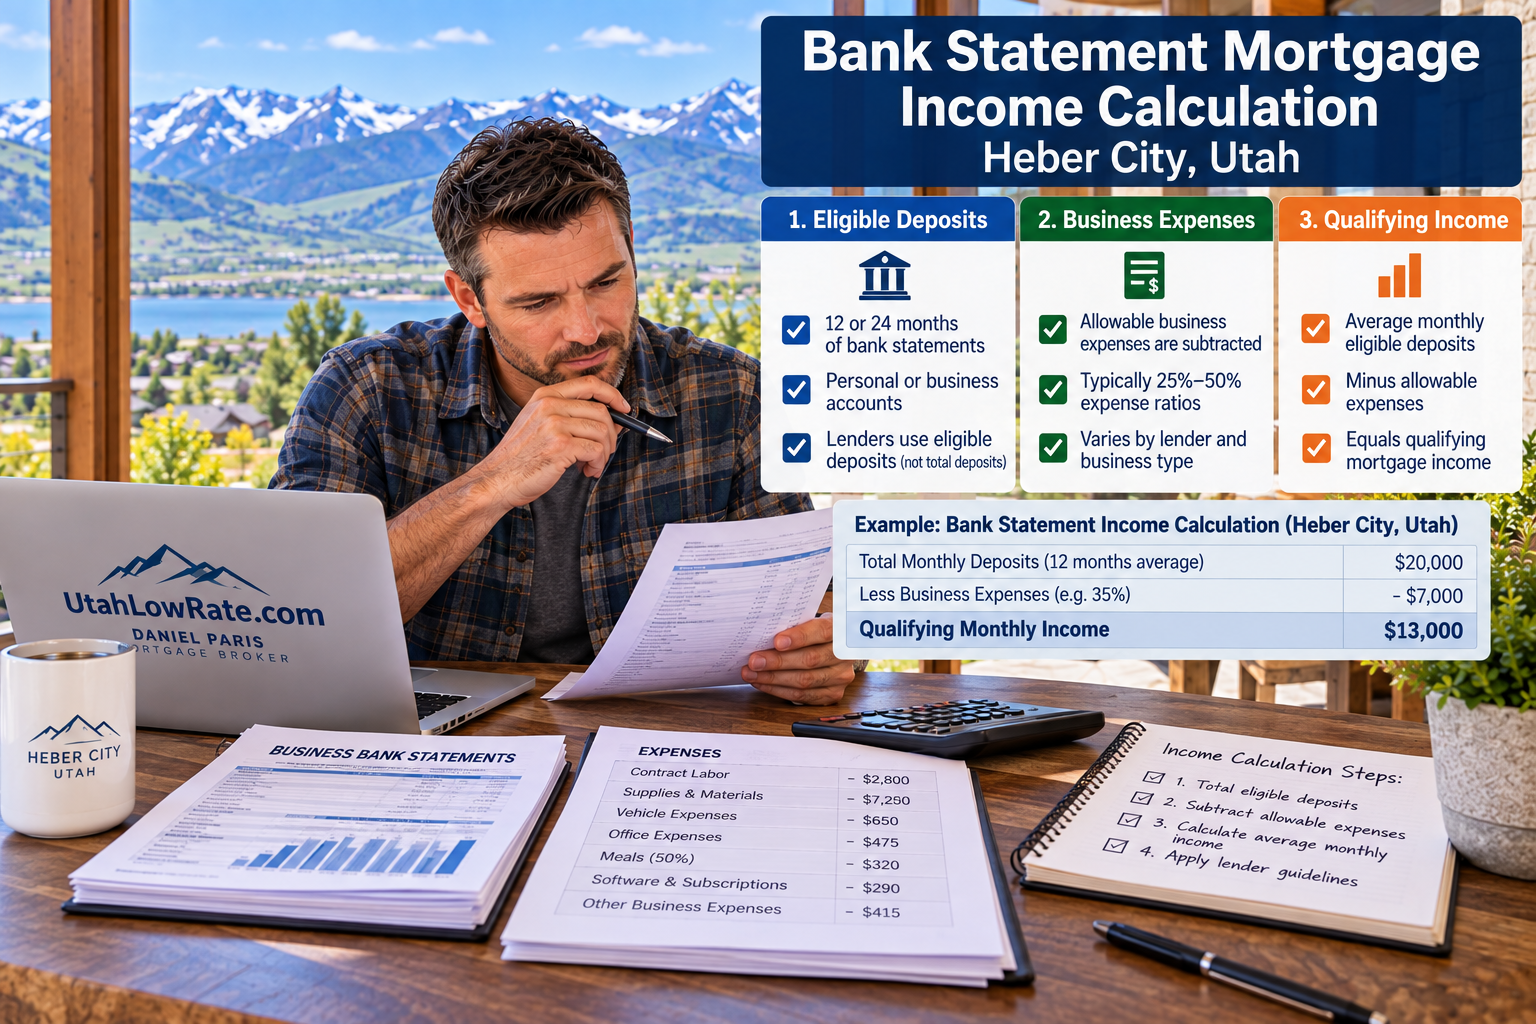
Eligible deposits and business expenses can affect bank statement mortgage qualifying income.
Income calculation is one of the most important parts of a bank statement loan in Heber City Utah.
Suppose a qualifying business averages:
$40,000 per month in eligible deposits
If the applicable program calculation results in 50% of eligible deposits being treated as qualifying income:
$40,000 × 50% = $20,000 potential qualifying monthly income
Request a Bank Statement Income Review
That example is for illustration only.
Another lender or program may use a different approved expense methodology.
Actual qualifying income can depend on:
- Eligible deposits
- Type of business
- Business expenses
- Statement period
- Ownership percentage
- Account structure
- Transfers
- Unusual deposits
- Investor requirements
Use our Bank Statement Loan Income Calculator to learn how eligible deposits and business-expense calculations may affect estimated qualifying income.
Which Bank Deposits May Count Toward Mortgage Income?
The goal of a bank statement income analysis is to identify legitimate, recurring and supportable income.
Eligible business revenue may potentially be included under the selected program.
However, statements can contain transactions that require additional review, such as:
- Transfers between accounts
- Loan proceeds
- Refunds
- Reimbursements
- Asset-sale proceeds
- Duplicate transactions
- Large unusual deposits
- Other non-recurring funds
For example, moving $15,000 from one business account to another does not create an additional $15,000 of business income.
Reviewing statements before formal underwriting can help identify transfers, unusual deposits and other potential documentation issues early.
Bank Statement Loans in Heber City and the Wasatch Back
Alternative-documentation mortgage options for qualified borrowers in Midway, Jordanelle and the Wasatch Back.
Heber City is part of a distinct Wasatch Back real estate market where self-employment, second homes and higher-value properties can sometimes overlap.
Heber City
Self-employed borrowers purchasing or refinancing in Heber City may consider bank statement financing when conventional tax-return calculations do not adequately represent recurring business income.
Your business does not necessarily need to be located in Heber City.
Qualification depends on the borrower, income documentation, property and applicable mortgage program.
Midway
Midway includes primary residences, second homes and higher-value properties.
Self-employed borrowers purchasing or refinancing a Midway property may want to compare traditional mortgage qualification with alternative bank statement income documentation.
Jordanelle
Properties surrounding Jordanelle can involve larger purchase prices, primary residences, second homes and investment scenarios.
Some borrowers may therefore need to solve two issues simultaneously:
Alternative income documentation + jumbo financing
Hideout
Higher-value homes around Hideout can create similar financing needs.
The bank statement income calculation, available loan amount, down payment, liquidity and reserve requirements should be evaluated together.
Kamas
Qualified self-employed borrowers purchasing or refinancing properties around Kamas may also have access to bank statement mortgage programs.
Program availability depends on the complete borrower and property profile.
Borrowers looking west toward Summit County can also review our bank statement mortgage resources for Park City and other Wasatch Back luxury markets.
Jumbo Bank Statement Loans Heber City Utah
Jumbo bank statement financing may help qualified self-employed borrowers purchasing higher-value Wasatch Back homes.
Higher-value Heber City, Midway, Jordanelle and Hideout properties can create two separate financing questions:
How will your self-employed income be documented?
and
Which mortgage program can accommodate the required loan amount?
A jumbo bank statement mortgage may potentially address both.
Select wholesale investors provide higher-balance alternative-documentation mortgages for qualified self-employed borrowers.
Jumbo underwriting can place additional emphasis on:
- Qualifying bank statement income
- Credit profile
- Liquidity
- Assets
- Mortgage reserves
- Down payment
- Property value
- Appraisal
- Occupancy
- LTV
- Requested loan amount
If the property requires a higher mortgage amount, review Jumbo Bank Statement Loans Utah.
For broader jumbo options that are not limited to bank statement qualification, visit our Utah mortgage loan resources to compare traditional and alternative financing.
Bank Statement Loans Heber City Utah Requirements
There is no single credit score, LTV, reserve requirement or loan amount that applies to every bank statement program.
Guidelines vary by investor.
For a comprehensive breakdown, see Bank Statement Loan Requirements Utah.
Credit Requirements
There is no universal minimum credit score for every bank statement program.
Credit can affect:
- Available programs
- Maximum LTV
- Down payment
- Pricing
- Loan amount
- Reserve requirements
Down Payment and LTV
The amount of required equity or down payment corresponds to the maximum LTV available under the applicable program.
| Example LTV | Corresponding Equity/Down Payment |
|---|---|
| 90% | 10% |
| 85% | 15% |
| 80% | 20% |
| 75% | 25% |
These percentages illustrate the mathematical relationship between LTV and equity only. They do not mean every borrower qualifies for each LTV.
Mortgage Reserves
Many bank statement mortgage programs require eligible assets remaining after closing.
Reserve requirements may depend on:
- Credit
- Loan amount
- Property type
- Occupancy
- Number of financed properties
- LTV
- Investor requirements
Self-Employment History
Required self-employment history varies by program.
The selected investor determines the required self-employment history. A shorter business history needs a current, individual review; a statement period alone does not establish eligibility.
Documents for a Heber City Bank Statement Mortgage
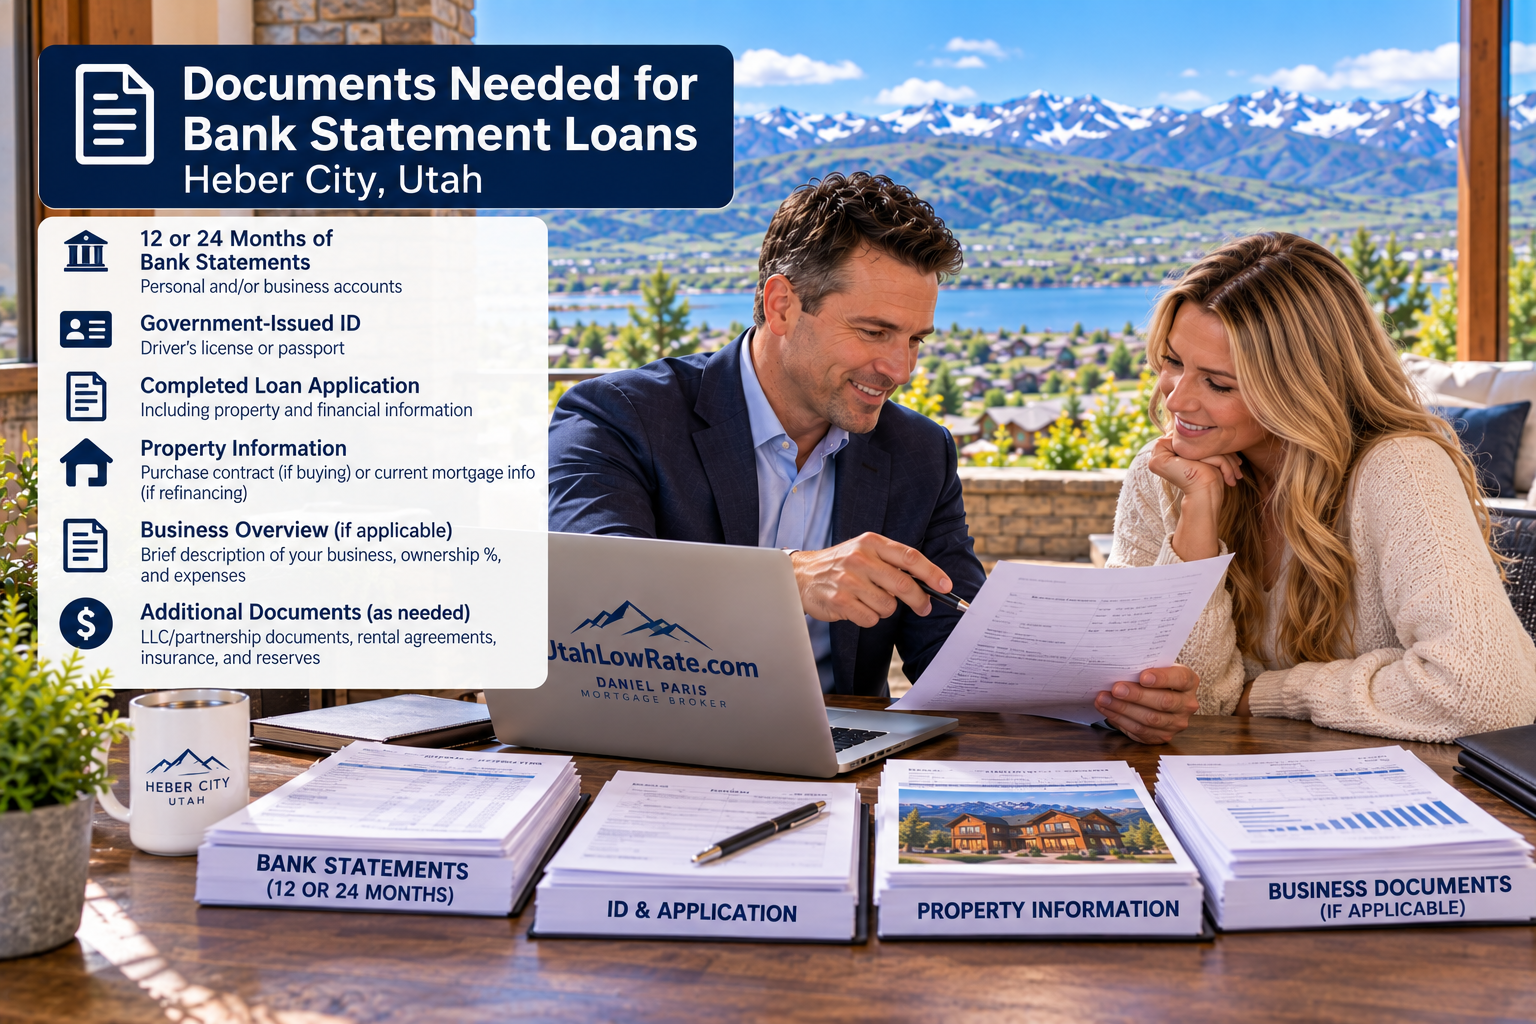
Common documents reviewed during a Heber City bank statement mortgage application.
Documentation varies by program, but a borrower may be asked for:
- 12 or 24 months of complete bank statements
- Identification
- Evidence of self-employment
- Business documentation
- Asset statements
- Down-payment documentation
- Closing-fund documentation
- Reserve documentation
- Explanations for unusual deposits
- Documentation supporting transfers
- Housing history
- Purchase contract
- Property information
- Insurance documentation
- Additional lender-requested documents
Preparing these documents before underwriting can help identify potential issues earlier in the mortgage process.
For a detailed checklist, visit Bank Statement Loan Requirements Utah.
Bank Statement Loan vs. Traditional Mortgage
| Feature | Bank Statement Mortgage | Traditional Mortgage |
|---|---|---|
| Primary income method | Eligible bank deposits | Traditional income documentation |
| Typical use | Self-employed borrowers | Wage earners and self-employed borrowers |
| Bank statement period | Commonly 12 or 24 months | Primarily used for asset verification |
| Business expense analysis | Often important | Tax-return calculation may incorporate expenses |
| Full underwriting | Yes | Yes |
| Credit reviewed | Yes | Yes |
| Assets reviewed | Yes | Yes |
| Property reviewed | Yes | Yes |
| Jumbo options | Select investors | Yes |
A bank statement mortgage is not automatically better than conventional financing.
The appropriate structure depends on the borrower's actual income documentation, credit, assets, property, loan amount and financial objectives.
Bank Statement Loan vs. DSCR Loan in Heber City
Bank statement and DSCR mortgages solve different qualification problems.
A bank statement mortgage generally evaluates the borrower's eligible personal or business income.
A DSCR mortgage generally focuses on the qualifying rental cash flow of an investment property rather than traditional personal employment income.
For example:
Self-employed borrower purchasing a primary residence in Heber City: a bank statement program may be appropriate.
Investor purchasing a qualifying rental property: a DSCR mortgage may be worth comparing.
Real estate investors can learn more at DSCR Mortgage Loans Utah.
Can I Purchase, Refinance or Take Cash Out With a Bank Statement Loan?
Potentially, depending on the program.
Purchase
Qualified borrowers may use bank statement financing to purchase eligible primary residences and, under qualifying programs, second homes or investment properties.
Rate-and-Term Refinance
Certain programs permit borrowers to refinance qualifying existing mortgage debt using bank statement income documentation.
Cash-Out Refinance
Select investors may also permit bank statement cash-out refinancing.
Cash-out transactions can have different requirements for:
- Credit
- LTV
- Property
- Seasoning
- Reserves
- Loan amount
- Documentation
How to Prepare Before Applying for a Heber City Bank Statement Loan
One of the most useful first steps is having your bank statements reviewed before assuming how much income a lender will use.
A preliminary review can help determine:
- Whether personal or business statements are more appropriate.
- Whether a 12- or 24-month program should be evaluated.
- Which deposits may potentially qualify.
- Whether transfers need to be excluded.
- Whether unusual deposits need documentation.
- How business expenses may affect qualifying income.
- Approximate qualifying monthly income.
- Whether jumbo financing may be necessary.
- Potential down-payment and reserve considerations.
This can be especially valuable before making an offer on a higher-value property in Heber City, Midway, Jordanelle or Hideout.
Explore the Utah Bank Statement Loan Cluster
If you are researching bank statement financing, continue with these UtahLowRate.com resources:
Bank Statement Loans Utah
Start with the statewide guide to bank statement mortgage programs for self-employed Utah borrowers.
Bank Statement Loan Requirements Utah
Review documentation, credit, deposits, assets, reserves, LTV and other underwriting considerations.
Bank Statement Loan Income Calculator
Learn how eligible deposits and applicable business-expense methodologies may affect estimated qualifying income.
Bank Statement Loan FAQ
Find answers to common questions about bank statement mortgage qualification.
Jumbo Bank Statement Loans Utah
Explore higher-balance alternative-documentation financing for qualified self-employed borrowers.
Bank Statement Loans Salt Lake City
Explore local bank statement mortgage options for Salt Lake City and the Salt Lake Valley.
Bank Statement Loans Utah County & Lehi
Learn about self-employed mortgage options for Lehi, Provo, Orem and surrounding Utah County communities.
Frequently Asked Questions About Bank Statement Loans Heber City Utah
Can I get a bank statement loan in Heber City without using tax returns to calculate qualifying income?
Potentially. Certain programs may calculate qualifying income using eligible personal or business bank deposits rather than relying primarily on traditional tax-return income calculations. Full underwriting and other documentation are still required.
Do I need 12 or 24 months of bank statements?
Both structures may be available. The appropriate documentation period depends on the lender or investor, business history, income consistency and complete transaction.
Can I use business bank statements for a Heber City mortgage?
Potentially. Certain programs permit business statements, but gross deposits generally cannot simply be treated as personal qualifying income without considering the applicable business-expense methodology.
Can I use personal bank statements?
Certain programs permit personal bank statements when they appropriately document recurring self-employment income.
Can I get a bank statement loan in Midway or Jordanelle?
Potentially. Bank statement mortgage programs may be available for qualified borrowers in Midway, Jordanelle and other Wasatch County communities. Eligibility depends on the borrower, property, occupancy and selected program.
Can I get a jumbo bank statement loan in Heber City?
Select investors provide jumbo bank statement mortgages for qualified self-employed borrowers requiring larger mortgage amounts. Credit, income, assets, reserves, property, LTV and other underwriting requirements apply.
Can I refinance using bank statements?
Certain programs permit rate-and-term and cash-out refinancing using bank statement income documentation, subject to applicable underwriting requirements.
Are bank statement mortgages no-documentation loans?
No. Bank statement mortgages require underwriting and documentation. The primary difference is the method used to establish qualifying income.
Get a Bank Statement Loan Review in Heber City
If you are self-employed and buying or refinancing in Heber City, Midway, Jordanelle, Hideout, Kamas or another Wasatch Back community, the important question is not simply how much money enters your bank account.
The important question is:
How much of your recurring bank statement revenue can an applicable mortgage program use as qualifying income?
Daniel Paris can review your bank-statement structure, proposed property, credit, assets, reserves, down payment or equity and desired loan amount and compare available mortgage programs through wholesale lending sources.
Talk With Daniel Paris
Daniel Paris
Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
NMLS #243976-3138
UtahLowRate.com
801-604-4949
Ask for a Heber City bank statement mortgage review.
Mortgage programs, rates, terms, credit requirements, LTV limits, reserve requirements, loan amounts and investor guidelines are subject to change. All financing is subject to borrower qualification, underwriting, property eligibility, appraisal requirements and lender/investor guidelines. This page is for educational purposes and does not constitute a commitment or guarantee to lend.
Request a Bank Statement Income Review · Call Daniel Paris: 801-604-4949

