
Content updated: September 29, 2026
Credit Requirements for Jumbo Mortgages
If you are researching Jumbo Loan Credit Score Utah requirements, there is no single credit score that applies to every jumbo mortgage. Jumbo lenders and investors establish their own guidelines, and the credit score needed can change based on the loan amount, down payment, loan-to-value ratio, property type, occupancy, reserves and overall borrower profile.
Check My Jumbo Options or call 801-604-4949.
UtahLowRate.com helps qualified borrowers compare jumbo mortgage programs for higher-value properties throughout Utah, including Salt Lake City, Park City, Deer Valley, Holladay, Cottonwood Heights, Draper, Alpine, Highland, Heber City, Midway, Provo and St. George.
Daniel Paris | Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Quick Answer: There is no universal minimum credit score for a jumbo loan in Utah. Many traditional jumbo programs favor stronger credit profiles, while specialized jumbo and Non-QM programs may consider borrowers with lower scores. Your credit score is only one part of underwriting; LTV, reserves, income, assets, loan amount and property type can all affect eligibility.
Jumbo Loan Credit Score Utah: Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Factor | Why It Matters |
|---|---|
| Credit score | May affect eligibility, pricing and maximum LTV |
| Loan amount | Larger jumbo loans can have different credit standards |
| Down payment | More equity may help offset other risk factors |
| LTV | Lower LTV generally represents less lender risk |
| Reserves | Jumbo programs commonly review post-closing liquidity |
| Income | Must meet the documentation rules of the selected program |
| Property type | Condos, investment homes and unique properties may have additional rules |
| Occupancy | Primary, second-home and investment guidelines can differ |
| Cash-out | Cash-out programs may have different credit/LTV requirements |
| Documentation | Full-doc, bank statement and asset-based programs can use different guidelines |
What Credit Score Do You Need for a Jumbo Loan in Utah?
The credit score needed for a jumbo loan in Utah depends on the particular lender and loan program.
Unlike agency-conforming mortgages, jumbo mortgages are not governed by one universal jumbo credit-score matrix. One investor might require stronger credit for a high-LTV jumbo purchase, while another may permit a lower score when the borrower has substantial equity, reserves or other compensating factors.
This is why asking only, “What is the minimum jumbo credit score?” can be misleading.
A better question is:
What jumbo mortgage programs are available for my credit score, loan amount, LTV, occupancy and property?
That allows a mortgage broker to compare the entire transaction rather than focusing on one number.
Is 700 a Good Credit Score for a Jumbo Loan?
A 700 credit score may provide access to jumbo financing, but it does not automatically qualify a borrower.
A lender may also evaluate:
- Requested loan amount
- Purchase price or appraised value
- Down payment
- Loan-to-value ratio
- Debt-to-income ratio
- Income stability
- Employment or self-employment history
- Cash reserves
- Property type
- Occupancy
- Mortgage and housing payment history
- Recent credit events
- Number and type of financed properties
Two borrowers with the same 700 score can therefore receive very different jumbo loan options.
One may be purchasing a $1.5 million primary residence with a substantial down payment and significant liquid reserves. Another may want a high-LTV cash-out refinance on an investment property.
Their credit scores are identical, but the mortgage risk profiles are not.
Can You Get a Jumbo Loan With a Credit Score Below 700?
Potentially.
A credit score below 700 does not necessarily mean jumbo financing is unavailable. Specialized jumbo and Non-QM investors may have programs for borrowers whose credit profiles fall outside conventional jumbo guidelines.
Eligibility becomes increasingly dependent on the complete transaction.
A borrower with a lower credit score may benefit from factors such as:
- Larger down payment
- Lower loan-to-value ratio
- Significant liquid assets
- Strong reserves
- Stable qualifying income
- Lower debt-to-income ratio
- Strong recent mortgage history
- Lower requested loan amount relative to property value
Program availability varies and approval is never determined by credit score alone.
What About a 680 Jumbo Loan Credit Score?
A 680 credit score may be considered by some jumbo or Non-QM programs, depending on the rest of the file.
For example, a borrower with substantial equity and strong reserves could have different options from a borrower seeking maximum financing.
Instead of assuming that 680 automatically qualifies—or automatically disqualifies—you should have the complete scenario reviewed.
How Credit Score Affects Jumbo Loan Down Payment
Credit score and down payment often work together in jumbo underwriting.
As LTV increases, lenders take on more exposure. Some investors therefore require stronger credit at higher LTVs.
Consider two hypothetical borrowers:
| Borrower | Credit | Down Payment | General Risk Profile |
|---|---|---|---|
| A | 760 | 30% | Strong credit + substantial equity |
| B | 680 | 10% | Lower credit + higher leverage |
These borrowers should not expect identical program availability or pricing.
A borrower with a lower credit score may find that increasing the down payment improves the range of available jumbo programs.
Read our Jumbo Loan Down Payment Utah guide to understand how credit, equity and LTV interact.
Credit Score and Jumbo Loan LTV
Loan-to-value is another important component of jumbo underwriting.
The formula is straightforward:
Loan Amount ÷ Property Value = LTV
For example, a $1,200,000 mortgage on a $1,500,000 property represents an 80% LTV.
A $900,000 mortgage on the same $1,500,000 property represents a 60% LTV.
The second transaction gives the lender substantially more equity protection.
This is why borrowers with less-than-perfect credit should not evaluate their jumbo eligibility from credit score alone.
Higher Credit + Lower LTV
This combination may provide access to a broader range of jumbo programs and potentially more favorable pricing.
Lower Credit + Lower LTV
A larger equity position may help make a transaction eligible for programs that would not accept the same credit profile at a higher LTV.
Lower Credit + Higher LTV
This combination can reduce available program choices and may increase pricing or reserve requirements.
Actual limits vary by lender and investor.
Jumbo Loan Credit Score Requirements by Loan Amount
Credit requirements may also change as the requested mortgage becomes larger.
A $900,000 mortgage and a $5 million mortgage are both potentially considered jumbo financing depending on the property location and applicable conforming limit, but they do not necessarily have the same underwriting guidelines.
As loan amounts increase, an investor may place additional emphasis on:
- Credit history
- Liquidity
- Net worth
- Reserves
- Property marketability
- Appraisal requirements
- Income stability
- Debt obligations
- Loan-to-value ratio
Borrowers requiring substantially larger mortgages should also review our Super Jumbo Mortgage Loans information.
Jumbo Loan Credit Score for Park City and Deer Valley
Park City and Deer Valley frequently involve higher property values and larger mortgage amounts than many other Utah housing markets.
Borrowers purchasing or refinancing homes in:
- Deer Valley
- Empire Pass
- Old Town Park City
- Canyons Village
- Promontory
- Prospector
- Kimball Junction
- Jordanelle
- Hideout
may encounter jumbo or high-balance financing depending on the loan amount and applicable county loan limit.
Summit County also has a higher conforming loan limit than most Utah counties, so the property location and requested loan amount should be checked before assuming the mortgage must be jumbo.
For luxury transactions well beyond conventional limits, credit requirements may depend heavily on loan size, liquidity, reserves and LTV.
Jumbo Loan Credit Score for Salt Lake City Luxury Homes
Jumbo financing is also common in higher-priced portions of the Salt Lake Valley, including:
- Salt Lake City
- Holladay
- Cottonwood Heights
- Millcreek
- Sandy
- Draper
- South Jordan
A borrower purchasing a luxury home in Holladay may have different jumbo options from a borrower buying an investment property in downtown Salt Lake City.
Property use matters.
Primary residences, second homes and investment properties may each carry different credit and LTV guidelines.
Jumbo Credit Requirements for Self-Employed Borrowers
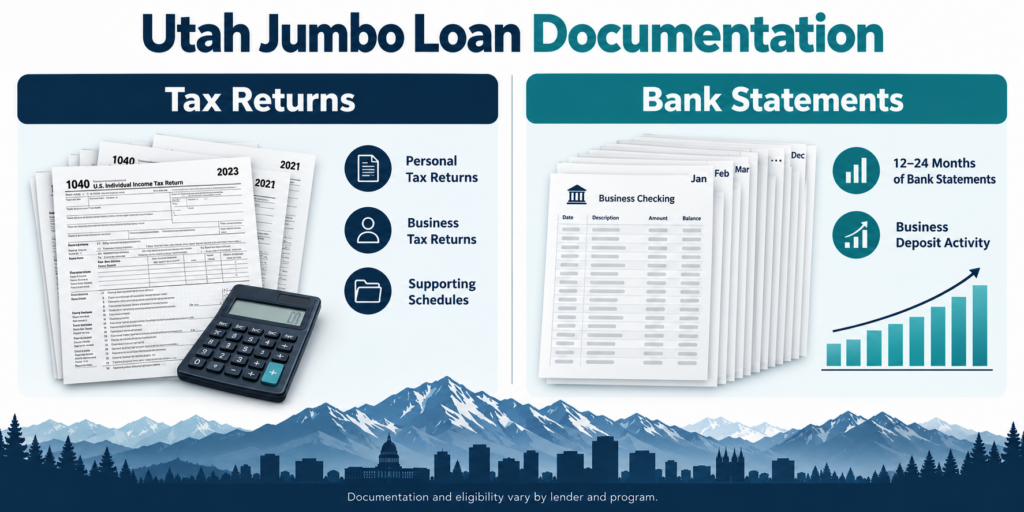
Self-employed borrowers sometimes have excellent credit but cannot document enough qualifying income using traditional tax-return calculations.
That does not necessarily mean the borrower cannot qualify for a jumbo mortgage.
Alternative-documentation programs may include:
- Jumbo bank statement loans
- Personal bank statement loans
- Business bank statement loans
- Asset-based qualification
- Asset depletion
- Profit-and-loss programs
- Other Non-QM jumbo mortgages
With a bank statement mortgage, eligible deposits may be analyzed to establish qualifying income rather than relying primarily on traditional tax-return income calculations.
Credit remains important, but income documentation is evaluated differently.
Self-employed borrowers can learn more in our Jumbo Bank Statement Loans Utah guide.
Does a Higher Credit Score Lower a Jumbo Mortgage Rate?
It can.
Credit is one of several risk factors that may influence jumbo mortgage pricing. Higher credit scores can sometimes provide better pricing or access to programs unavailable at lower scores.
However, jumbo mortgage rates can also depend on:
- Loan amount
- LTV
- Occupancy
- Property type
- Documentation
- Loan term
- Fixed versus adjustable rate
- Interest-only features
- Cash-out amount
- Reserves
- Investor pricing
This means the borrower with the highest credit score does not automatically receive the lowest available rate.
The complete loan structure matters.
How Can I Improve My Jumbo Loan Options?
Before applying for a jumbo mortgage, consider reviewing the entire financial profile rather than concentrating exclusively on your credit score.
1. Review Your Credit
Look for inaccurate reporting, excessive revolving balances or other items that may affect mortgage scoring.
2. Evaluate Your Down Payment
Increasing the down payment lowers the LTV and may open additional program choices.
3. Preserve Liquid Assets
Do not assume that putting every available dollar into the down payment is the best strategy. Some jumbo programs place significant importance on post-closing reserves.
4. Avoid New Debt Before Closing
New auto loans, credit cards or other obligations can affect both credit and debt-to-income ratios.
5. Compare Multiple Jumbo Investors
Jumbo underwriting is not standardized across every lender.
A mortgage broker may be able to compare programs from multiple wholesale lending sources instead of evaluating your application under a single bank's jumbo guidelines.
Jumbo Loan Credit Score vs. Conforming Mortgage Credit
Jumbo and conforming mortgages operate differently.
Conforming loans are designed to meet the requirements for mortgages purchased by Fannie Mae or Freddie Mac.
Jumbo loans generally fall outside the applicable conforming loan amount or agency parameters and are therefore subject to the guidelines of the lender or investor providing the financing.
This distinction matters because a credit profile that does not fit one jumbo lender may potentially fit another.
For 2026, the baseline one-unit conforming loan limit in most Utah counties is $832,750. Certain Utah counties have higher limits.
Before deciding you need a jumbo mortgage, verify the current limit for the county where the property is located.
Documents Needed for a Utah Jumbo Mortgage
Documentation depends on the selected program, but borrowers may be asked for:
- Identification
- Credit authorization
- Income documentation
- Employment history
- Bank and investment statements
- Retirement account statements
- Documentation of down-payment funds
- Reserve verification
- Purchase contract
- Homeowners insurance
- Property information
- Existing mortgage statements for refinances
Self-employed and alternative-documentation programs may require different documentation.
Jumbo Mortgage Options Available in Utah
Depending on borrower qualifications and program availability, jumbo financing may include:
- Fixed-rate jumbo loans
- Adjustable-rate jumbo mortgages
- Jumbo purchase loans
- Jumbo rate-and-term refinance
- Jumbo cash-out refinance
- Jumbo bank statement loans
- Asset-depletion jumbo mortgages
- Interest-only jumbo loans
- Second-home jumbo financing
- Investment-property jumbo loans
- Super jumbo mortgages
Loan amounts, minimum credit scores, maximum LTVs and reserve requirements vary by program.
Utah Jumbo Loan Areas We Serve
UtahLowRate.com works with qualified jumbo borrowers throughout Utah, including:
Salt Lake County: Salt Lake City, Holladay, Millcreek, Cottonwood Heights, Murray, Sandy, Draper and South Jordan.
Summit County: Park City, Deer Valley, Canyons Village, Promontory, Old Town, Empire Pass and Kimball Junction.
Wasatch County: Heber City, Midway and Jordanelle.
Utah County: Alpine, Highland, Lehi, American Fork, Pleasant Grove, Provo, Orem and Saratoga Springs.
Washington County: St. George, Washington, Ivins, Santa Clara and Hurricane.
Frequently Asked Questions About Jumbo Loan Credit Scores in Utah
What credit score do I need for a jumbo loan in Utah?
There is no universal minimum credit score for every Utah jumbo loan. Requirements vary by lender, loan amount, LTV, property type, occupancy, reserves and documentation program.
Can I get a jumbo loan with a 680 credit score?
Some jumbo and Non-QM programs may consider a 680 credit score depending on the loan amount, equity, reserves, income, property and other underwriting factors.
Is a 700 credit score enough for a jumbo mortgage?
A 700 score may fit some jumbo programs, but credit alone does not determine approval. LTV, income, assets, reserves, property and loan amount also matter.
Do jumbo loans require better credit?
Traditional jumbo lenders often emphasize strong credit because of the larger loan exposure. Specialized jumbo and Non-QM investors may offer different credit requirements.
Does a larger down payment help if my credit score is lower?
Potentially. A larger down payment reduces LTV and lender exposure and may expand the number of jumbo programs available to a borrower.
What credit score do I need for a $2 million mortgage?
There is no universal score requirement for a $2 million mortgage. Requirements depend on the lender, LTV, occupancy, reserves, documentation, property and overall borrower profile.
Can self-employed borrowers qualify for jumbo loans?
Yes. Qualified self-employed borrowers may use traditional full-documentation jumbo programs or alternative programs such as jumbo bank statement, asset-based or other Non-QM mortgages.
Compare Jumbo Loan Options in Utah
Your credit score is important, but it should not be evaluated in isolation.
The combination of credit score + loan amount + LTV + reserves + income documentation + occupancy + property type determines which jumbo programs may be worth considering.
UtahLowRate.com can review the complete scenario and compare available wholesale jumbo mortgage options.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
Call: 801-604-4949
CTA: Check My Jumbo Loan Options
Mortgage programs, rates, credit requirements, LTV limits, loan amounts and reserve requirements are subject to lender/investor guidelines and change without notice. All loans are subject to complete underwriting, borrower qualification, acceptable collateral and program availability.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

