
Content updated: September 29, 2026
Jumbo Purchase Loans Utah provide financing for qualified homebuyers purchasing properties when the required mortgage amount exceeds the applicable conforming loan limit or otherwise requires non-conforming financing. Jumbo financing can be especially important when buying luxury and higher-value homes in Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Highland, Heber City, Midway, St. George and other Utah communities.
Daniel Paris with UtahLowRate.com helps qualified Utah buyers compare jumbo and super jumbo purchase mortgage programs from multiple lending sources.
Check My Jumbo Options or call 801-604-4949.
Daniel Paris | Utah Mortgage Broker
UtahLowRate.com | NMLS #243976-3138
Call: 801-604-4949
Loan programs, rates, down-payment requirements, credit requirements, loan amounts, reserves and underwriting guidelines vary by lender and are subject to change.
Quick Answer: What Is a Jumbo Purchase Loan in Utah?
A jumbo purchase loan in Utah is a mortgage used to buy a home when the required loan amount exceeds the applicable conforming loan limit or falls outside standard conforming guidelines. Jumbo lenders may use different requirements for credit, income, assets, reserves, down payment, property type and debt-to-income ratio.
Jumbo purchase financing may be available for qualified buyers purchasing primary residences, second homes and, under certain programs, investment properties.
For a broader overview, see the Utah Jumbo Mortgage guide.
Jumbo Purchase Loans Utah: Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Typical Jumbo Purchase Consideration |
|---|---|
| Purpose | Purchase a higher-priced property |
| Loan type | Non-conforming/jumbo mortgage |
| Occupancy | Primary, second home; select investment programs |
| Down payment | Depends on loan amount and borrower profile |
| Credit | Program-specific |
| Income | Full documentation or eligible alternative documentation |
| Assets | Funds for closing plus applicable reserves |
| Property | Must meet lender/appraisal requirements |
| Loan size | Above conforming through jumbo and super jumbo ranges |
| Fixed rates | Available under qualifying programs |
| ARM options | Available under qualifying programs |
| Interest-only | Select jumbo programs |
| Self-employed options | Bank statement and other eligible programs may be available |
There is no single jumbo program that is best for every Utah buyer. The combination of loan amount, property value, occupancy, credit, income, assets and reserves determines which programs should be compared.
How Do Jumbo Purchase Loans in Utah Work?
The basic purchase process is similar to other mortgages, but jumbo underwriting can involve additional financial review.
A lender may evaluate:
- Purchase price
- Requested loan amount
- Down payment
- Loan-to-value ratio
- Credit scores and credit history
- Employment and income
- Debt-to-income ratio
- Liquid assets
- Funds required for closing
- Post-closing reserves
- Property type
- Occupancy
- Appraisal
- Overall borrower financial strength
Because jumbo loans are not necessarily sold under the same standards as conforming mortgages, requirements can vary substantially between lenders.
That makes lender comparison particularly important.
When Does a Utah Homebuyer Need a Jumbo Loan?
A homebuyer generally enters jumbo territory when the mortgage amount exceeds the applicable conforming loan limit.
The important number is usually the loan amount, not simply the purchase price.
For example, two buyers could purchase homes at the same price while only one requires jumbo financing because their down payments are different.
Current conforming limits can also vary by year, property type and applicable location.
Before assuming that a particular purchase requires jumbo financing, compare the proposed loan amount with the current conforming threshold.
Jumbo Purchase Loan Down Payment in Utah
One of the most common questions is:
How much do I need to put down on a jumbo loan in Utah?
There is no universal jumbo down-payment requirement.
The required down payment depends on factors such as:
- Loan amount
- Property value
- Credit profile
- Occupancy
- Property type
- Income documentation
- Assets
- Reserves
- Debt-to-income ratio
- Selected lender
- Overall transaction risk
A borrower requesting a relatively modest jumbo loan with strong credit, substantial liquidity and a primary residence may have different options from someone requesting a multi-million-dollar mortgage on a second home.
For a deeper explanation, see the Jumbo Loan Down Payment Utah guide.
Why LTV Matters on a Jumbo Purchase
Loan-to-value, or LTV, compares the mortgage amount with the property's value or applicable purchase price.
For example, if an eligible property is purchased for $2,000,000 with a $1,400,000 mortgage:
$1,400,000 ÷ $2,000,000 = 70% LTV
That means the borrower is financing 70% of the purchase price and contributing 30%, before applicable closing costs.
Lower LTV can sometimes improve available jumbo program choices or pricing, although other underwriting factors still matter.
What Credit Score Is Needed for a Jumbo Purchase Loan?
There is no single minimum credit score covering every jumbo lender.
Credit requirements can vary according to:
- Loan amount
- LTV
- Occupancy
- Property type
- Reserves
- Documentation
- Recent credit history
- Overall borrower profile
A higher credit score may provide access to additional programs or more favorable pricing, but credit score should not be evaluated by itself.
See Jumbo Loan Credit Score Utah for a detailed discussion of how credit interacts with LTV, loan size and underwriting.
How Much Can You Borrow With a Utah Jumbo Purchase Loan?
Jumbo mortgages can extend significantly beyond conventional conforming loan sizes.
Depending on borrower qualifications and available programs, UtahLowRate.com can evaluate traditional jumbo and super jumbo mortgage financing for high-value properties.
Large transactions can require a more detailed analysis of:
- Liquidity
- Net worth
- Reserves
- Income stability
- Asset concentration
- Property characteristics
- Loan structure
- LTV
- Credit
- Overall financial profile
For larger transactions, the right structure may be just as important as the interest rate.
See Jumbo Loan Limits Utah and the UtahLowRate.com Super Jumbo Mortgage information for additional options.
Jumbo Purchase Loans for Utah Luxury Homes
Jumbo purchase mortgages are particularly relevant in Utah communities where home values frequently exceed conventional financing ranges.
Park City and Deer Valley Jumbo Purchase Loans
Park City and Deer Valley contain some of Utah's highest-value residential real estate.
Buyers may be purchasing:
- Luxury primary residences
- Second homes
- Resort-area properties
- Condominiums
- High-value single-family homes
- Properties in private communities
- Multi-million-dollar residences
A Park City jumbo purchase may require careful review of the property itself in addition to the borrower.
Condominium eligibility, project characteristics, occupancy, rental activity and appraisal considerations can all affect financing.
Salt Lake City, Holladay and Cottonwood Heights
Salt Lake County has numerous higher-value neighborhoods where jumbo financing may be appropriate.
Buyers in Salt Lake City, Holladay, Millcreek, Cottonwood Heights, Sandy and surrounding areas may need jumbo financing for larger custom homes and luxury properties.
Draper, Alpine and Highland
Draper, Alpine and Highland include many high-value homes where a jumbo purchase mortgage may be appropriate.
Buyers with substantial assets or complex compensation may benefit from comparing several jumbo lenders rather than relying on a single bank's underwriting model.
Heber City, Midway and Wasatch County
Heber City, Midway and the Jordanelle area continue to attract buyers looking for primary residences, vacation properties and second homes.
The correct mortgage structure depends on the property's intended occupancy and borrower qualifications.
St. George and Southern Utah
Luxury housing is also found throughout St. George, Ivins, Santa Clara and surrounding Washington County communities.
Qualified buyers purchasing higher-priced primary residences or second homes may use jumbo financing when the requested mortgage exceeds applicable conforming parameters.
Primary Residence vs. Second-Home Jumbo Purchase Loans
Occupancy matters.
Primary Residence
A primary residence is generally the home the borrower intends to occupy as their principal residence.
Depending on the program, primary residences may receive more favorable maximum LTV or underwriting treatment than other occupancy types.
Second Home
A qualifying second home may also be financed using a jumbo mortgage.
However, lenders can impose different requirements for:
- Down payment
- Reserves
- Location
- Property use
- Rental activity
- Loan amount
Buyers purchasing Utah resort-area properties should establish the intended occupancy early in the mortgage process.
Jumbo Purchase Loans for Self-Employed Borrowers
Business owners frequently encounter a different challenge when purchasing an expensive home: their financial strength may not be accurately represented by taxable income alone.
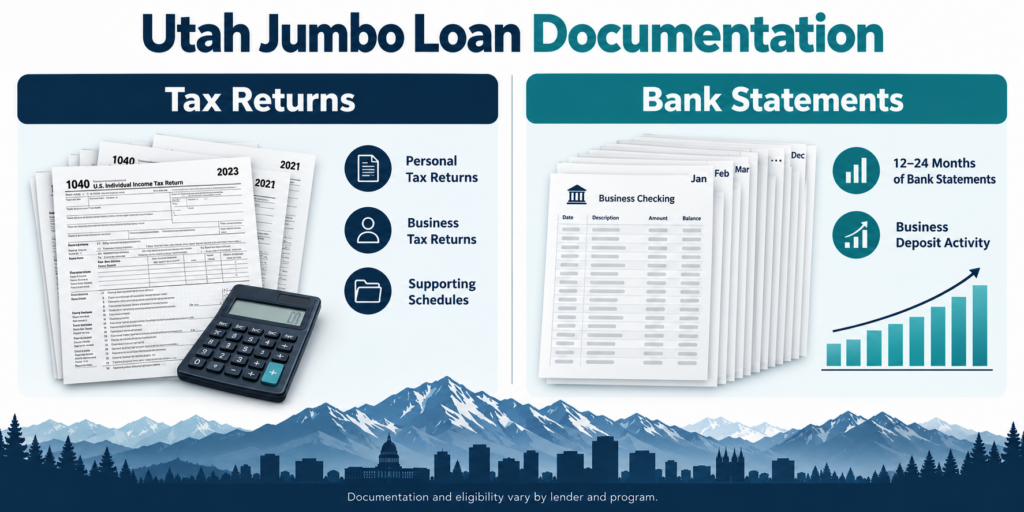
Traditional jumbo underwriting may use tax returns, W-2s, K-1s, business returns and other documentation.
But qualified self-employed borrowers may also have alternative-documentation options.
Jumbo Bank Statement Loans
A jumbo bank statement loan may allow an eligible self-employed borrower to establish qualifying income using eligible deposits from personal or business bank statements.
Programs may evaluate:
- 12 or 24 months of statements
- Eligible business or personal deposits
- Applicable business expenses
- Length of self-employment
- Credit
- Down payment
- Reserves
- Property
- Requested loan amount
Bank statement financing remains fully underwritten.
It is not a no-income or no-document mortgage.
Self-employed buyers can compare the Jumbo Bank Statement Loans Utah and Bank Statement Loans Utah guides for additional information.
Jumbo Purchase Loans With Complex Income
Jumbo borrowers often have income that does not fit neatly into a basic salary calculation.
Examples can include:
- Business ownership
- Bonuses
- Commissions
- Restricted stock
- RSUs
- Investment income
- Partnership income
- K-1 income
- Trust income
- Rental income
- Multiple businesses
- Asset-based income
- Retirement distributions
The correct documentation depends on the specific jumbo program.
A mortgage broker can compare lenders that treat a borrower's income or assets differently instead of assuming that one bank's answer represents the entire jumbo market.
Asset-Based and Pledged-Asset Jumbo Options
Some high-net-worth borrowers have substantial assets but prefer not to liquidate investments simply to purchase real estate.
Depending on available programs and borrower qualifications, financing strategies may include:
- Asset depletion
- Asset utilization
- Pledged assets
- Traditional jumbo financing
- Alternative-documentation jumbo financing
- Super jumbo financing
Each approach has different underwriting, liquidity and risk considerations.
Borrowers should also discuss investment, tax and legal consequences with their own qualified advisors where appropriate.
Fixed-Rate vs. ARM Jumbo Purchase Loans
Utah jumbo buyers may be able to choose between fixed-rate and adjustable-rate mortgage structures.
Fixed-Rate Jumbo Mortgage
The mortgage interest rate remains fixed according to the loan terms.
This may appeal to buyers who prioritize payment stability.
Jumbo ARM
Adjustable-rate mortgages may provide an initial fixed-rate period followed by adjustments according to the loan's terms.
Potential structures can include 5-, 7- and 10-year initial fixed periods under applicable programs.
The correct structure depends on the available pricing, expected holding period, financial objectives and tolerance for future rate changes.
Interest-Only Jumbo Purchase Options
Select jumbo programs may provide an interest-only payment period.
Interest-only financing can reduce the required contractual payment during the interest-only period, but principal is generally not reduced through those scheduled interest-only payments.
Borrowers should understand:
- Interest-only period
- Subsequent amortization
- Potential payment changes
- Rate structure
- Total interest expense
- Loan maturity
- Prepayment terms
An interest-only loan should be evaluated as a complete financial structure rather than solely by its initial payment.
Reserves for Jumbo Purchase Loans
Jumbo lenders may require borrowers to maintain assets after closing.
These are commonly called reserves.
Reserve requirements vary considerably and may depend on:
- Loan amount
- Number of financed properties
- Occupancy
- LTV
- Credit
- Property type
- Income documentation
- Overall borrower strength
Eligible reserve assets may also differ by lender.
For a high-value purchase, determine reserve requirements before moving substantial assets or committing all available liquidity to the down payment.
Jumbo Purchase Loan Documentation
A fully documented jumbo purchase may require documents such as:
Income
- Pay stubs
- W-2s
- Personal tax returns
- Business tax returns
- K-1s
- Employment verification
- Other applicable income documentation
Assets
- Bank statements
- Brokerage statements
- Retirement accounts
- Documentation of funds for closing
- Documentation of required reserves
- Documentation for large or unusual deposits when required
Property
- Purchase contract
- Appraisal
- Title information
- Homeowners insurance
- HOA or condominium documentation when applicable
Alternative-documentation programs can require a different set of documents.
Jumbo Purchase Loan Pre-Approval
Jumbo buyers should consider mortgage pre-approval before making an offer, particularly when purchasing an expensive property.
A meaningful jumbo pre-approval should evaluate more than a credit score.
It should review:
- Proposed purchase price
- Requested loan amount
- Down payment
- Credit
- Income documentation
- Assets
- Required reserves
- Occupancy
- Property type
- Potential jumbo lender guidelines
This can identify issues before the borrower is under contract.
How to Get a Jumbo Purchase Loan in Utah
Step 1: Determine Your Target Purchase Price
Estimate the property price range and desired down payment.
Step 2: Calculate the Required Loan Amount
Determine whether the proposed mortgage is likely to require jumbo financing.
Step 3: Review Credit
Credit can influence both program eligibility and pricing.
Step 4: Review Income Documentation
Determine whether traditional documentation, bank statements, asset-based qualification or another eligible approach is appropriate.
Step 5: Review Assets and Reserves
Separate funds required for the down payment and closing from assets that may need to remain available after closing.
Step 6: Compare Jumbo Programs
Compare more than the interest rate.
Review:
- Rate
- APR
- Points
- Lender fees
- LTV
- Reserve requirements
- Documentation
- Fixed vs. ARM structure
- Interest-only availability
- Prepayment provisions when applicable
- Property requirements
Step 7: Obtain Jumbo Pre-Approval
Complete underwriting review as early as practical before submitting an offer.
Step 8: Complete Property Underwriting
Once under contract, the property, appraisal, title and applicable project documentation are reviewed.
Step 9: Final Approval and Closing
After all underwriting conditions are satisfied, the loan can proceed toward final approval and closing.
Jumbo Purchase Loan vs. Conventional Loan
| Jumbo Purchase Loan | Conventional Conforming Loan |
|---|---|
| Designed for larger/non-conforming loan amounts | Must remain within applicable conforming parameters |
| Lender-specific underwriting | More standardized agency guidelines |
| Potentially higher reserve requirements | Reserve requirements depend on transaction |
| Large loan sizes available | Loan size constrained by applicable limits |
| Alternative documentation may be available | Primarily traditional agency documentation |
| Super jumbo options may be available | Not designed for multi-million-dollar non-conforming balances |
Neither loan is automatically better.
The correct choice depends on the required loan amount and complete transaction.
Jumbo Purchase Loan vs. DSCR Loan
A jumbo purchase mortgage and a DSCR mortgage serve different borrower needs.
A jumbo purchase loan is commonly used to purchase a higher-priced primary residence or second home and typically evaluates the borrower's ability to qualify under the selected jumbo program.
A DSCR loan is generally intended for business-purpose investment property and focuses heavily on whether qualifying property rental income supports the applicable property debt obligation.
| Jumbo Purchase | DSCR Purchase |
|---|---|
| Primary residence may qualify | Generally investment property |
| Second homes may qualify | Business-purpose rental property |
| Borrower income commonly evaluated | Property rental cash flow is central |
| Jumbo/super jumbo loan amounts | Investor-specific loan limits |
| Luxury-home financing | Rental-property financing |
If the property will be held strictly as an investment, review the DSCR Mortgage Loans Utah cluster before assuming a traditional jumbo mortgage is the best structure.
Utah DSCR Loan Resources for Investment Buyers
Buyers researching jumbo financing sometimes discover that the property they intend to purchase will actually be held as an investment.
For those transactions, review the UtahLowRate.com DSCR loan resources covering:
- DSCR Mortgage Loans Utah
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Loan LTV Utah
- DSCR Loans for LLCs Utah
- Interest-Only DSCR Loans Utah
- DSCR Purchase Loans Utah
- DSCR Refinance Loans Utah
- DSCR vs. Conventional Investment Loan Utah
- DSCR Loans Salt Lake City
- DSCR Loans Park City
- DSCR Loans St. George
These pages should form a tightly interconnected investment-property financing cluster.
Common Jumbo Purchase Mistakes to Avoid
Shopping Only for the Lowest Advertised Rate
A rate is meaningful only when you understand the points, fees, lock period and underwriting assumptions behind it.
Moving Assets During Underwriting
Large transfers can create additional documentation requirements.
Discuss major asset movements with your mortgage professional before making them.
Waiting Until Under Contract to Review Jumbo Eligibility
Jumbo transactions can involve additional underwriting complexity. Early review can identify issues before contractual deadlines begin.
Assuming Every Jumbo Lender Has the Same Guidelines
They do not.
One lender's maximum LTV, reserve requirement or treatment of income may differ significantly from another lender's guidelines.
Using All Available Cash for the Down Payment
A larger down payment does not automatically produce the best transaction if it leaves the borrower without sufficient required reserves.
Evaluate down payment and liquidity together.
Frequently Asked Questions About Jumbo Purchase Loans Utah
What is a jumbo purchase loan in Utah?
A jumbo purchase loan is a mortgage used to purchase a Utah property when the requested loan amount exceeds applicable conforming limits or otherwise requires non-conforming financing.
How much down payment is required for a Utah jumbo loan?
There is no universal down-payment requirement. The required amount depends on loan size, credit, occupancy, property type, assets, reserves, documentation and the selected lender's guidelines.
What credit score do I need for a jumbo purchase loan?
Credit requirements vary by jumbo program. Higher loan amounts or higher LTVs can have different credit requirements, so the complete transaction should be evaluated rather than relying on a single universal minimum score.
Can I use a jumbo loan to buy a Park City home?
Potentially. Qualified borrowers can use jumbo or super jumbo financing for eligible Park City and Deer Valley properties, including qualifying primary residences and second homes.
Can self-employed borrowers qualify for jumbo purchase loans?
Yes, subject to underwriting. Self-employed borrowers may qualify through traditional documentation or eligible alternative-documentation programs such as jumbo bank statement mortgages.
Can I get an interest-only jumbo mortgage?
Select jumbo programs may offer interest-only payment structures. Availability depends on the loan amount, LTV, borrower profile, occupancy, property and current lender guidelines.
Are jumbo loans only for luxury homes?
No. Jumbo status generally relates to the mortgage amount and applicable conforming limits, not whether the property is formally considered a luxury home.
Can I use DSCR financing instead of a jumbo mortgage?
If the property is an eligible investment property, a DSCR program may be worth comparing. DSCR loans generally focus on qualifying rental cash flow rather than traditional personal employment income. They are generally not designed for owner-occupied primary residences.
Compare Jumbo Purchase Loans in Utah
Purchasing a high-value Utah home requires more than finding a mortgage with a large enough loan limit.
The right jumbo structure should consider your:
- Purchase price
- Loan amount
- Down payment
- Credit
- Income
- Assets
- Reserves
- Occupancy
- Property
- Expected ownership period
- Financial objectives
Daniel Paris with UtahLowRate.com helps qualified borrowers compare jumbo and super jumbo mortgage programs for properties throughout Utah.
Serving Salt Lake City, Park City, Deer Valley, Holladay, Cottonwood Heights, Draper, Sandy, Alpine, Highland, Lehi, Heber City, Midway, St. George and communities throughout Utah.
Check My Jumbo Purchase Options
Buying a higher-priced Utah home?
Get a preliminary review of your proposed purchase price, down payment, credit, income documentation, assets and desired loan amount.
Daniel Paris
Utah Mortgage Broker | UtahLowRate.com
NMLS #243976-3138
Call: 801-604-4949
Apply online through UtahLowRate.com or request a jumbo purchase loan quote.
Mortgage programs, rates, APRs, loan amounts, LTV limits, credit requirements, reserve requirements, documentation requirements and underwriting guidelines are subject to change. All loans are subject to borrower qualification, acceptable property, appraisal, underwriting, investor guidelines and program availability. This information is educational and does not constitute a commitment to lend.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

