
Content updated: September 29, 2026
Super Jumbo Mortgage Rates Utah can vary substantially from one borrower, lender, property and loan structure to another. For qualified borrowers financing luxury homes, UtahLowRate.com can help compare specialized Super Jumbo mortgage programs from approximately $1 million to $30 million+, subject to lender guidelines and underwriting.
Unlike a standard conforming mortgage, there is no single Super Jumbo interest rate that applies to every multimillion-dollar transaction. Pricing may depend on your loan amount, credit profile, loan-to-value ratio, assets, reserves, property, occupancy, documentation and whether you choose fixed-rate or adjustable-rate financing.
Check My Jumbo Options or call 801-604-4949.
Daniel Paris | Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
UtahLowRate.com
Call: 801-604-4949
Serving qualified borrowers throughout Utah, including Salt Lake City, Park City, Deer Valley, Holladay, Cottonwood Heights, Draper, Alpine, Highland, Heber City, Midway and St. George.
Important: Mortgage rates change frequently. The rates available for a specific Super Jumbo transaction must be determined from the complete borrower and property scenario.
Quick Answer: What Are Super Jumbo Mortgage Rates in Utah?
There is no universal Super Jumbo mortgage rate in Utah. Rates are individually priced according to factors such as the loan amount, credit score, LTV, property type, occupancy, assets, reserves, income documentation, loan term and market conditions.
A borrower requesting a $2 million mortgage at a conservative LTV may receive different pricing from someone requesting a $10 million or $20 million mortgage.
For that reason, the best way to compare Super Jumbo Mortgage Rates Utah is to obtain pricing for the exact transaction rather than relying on a generic online rate.
Want a personalized comparison? Call Daniel Paris at 801-604-4949.
Super Jumbo Mortgage Rates Utah: Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Factor | Super Jumbo Mortgage Financing |
|---|---|
| Typical loan category | Approximately $1M–$30M+ |
| Fixed-rate options | Available on qualifying programs |
| ARM options | Available on qualifying programs |
| Purchase financing | Available |
| Rate-and-term refinance | Available |
| Cash-out refinance | Select programs |
| Primary residence | Available |
| Second home | Available |
| Investment property | Select programs |
| Bank statement qualification | Select programs |
| Asset-based qualification | Select programs |
| Pledged assets | May be available |
| Interest-only | Select programs |
| Pricing | Scenario-specific |
| Maximum LTV | Varies by loan size and program |
All rates, terms, LTVs, loan amounts and program features are subject to lender guidelines, borrower qualification and current market availability.
How Are Super Jumbo Mortgage Rates Determined?
Super Jumbo loans involve much larger credit exposure than an ordinary residential mortgage. As a result, lenders typically evaluate the complete financial profile of the borrower and property before determining pricing.
Loan Amount
Loan size can have a significant effect on Super Jumbo pricing.
A $2 million loan does not necessarily receive the same rate or pricing structure as a $5 million, $10 million, $20 million or $30 million mortgage.
Very large transactions may be handled by specialized private-bank, portfolio, wholesale or institutional lending programs.
If you are comparing a particular loan size, see our guides to:
- $2 Million Mortgage Loans Utah
- $5 Million Mortgage Loans Utah
- $10 Million Mortgage Loans Utah
- $20 Million Mortgage Loans Utah
- $30 Million Mortgage Loans Utah
Loan-to-Value Ratio
LTV is one of the most important variables in Super Jumbo underwriting.
A borrower putting substantial equity into a transaction generally represents less lending risk than a borrower requesting a higher LTV.
For example, pricing and program availability at 50% LTV may differ substantially from options at 70% or 80% LTV.
The relationship becomes especially important as loan amounts increase.
Credit Score and Super Jumbo Mortgage Rates
Credit is another major pricing factor.
Strong credit may provide access to a larger selection of Super Jumbo lenders and potentially more favorable pricing. However, credit score alone does not determine the rate.
A lender may evaluate:
- Mortgage payment history
- Overall credit history
- Revolving debt
- Installment debt
- Recent credit inquiries
- Derogatory credit
- Debt-to-income ratio
- Liquidity
- Net worth
- Post-closing reserves
A borrower with exceptional liquidity and a conservative LTV can present a very different overall risk profile from another borrower with the same credit score.
Fixed vs. ARM Super Jumbo Mortgage Rates Utah
Super Jumbo borrowers may have both fixed-rate and adjustable-rate mortgage options.
Fixed-Rate Super Jumbo Mortgage
A fixed-rate mortgage keeps the note rate fixed for the applicable loan term.
This may appeal to borrowers who value long-term payment predictability.
Super Jumbo ARM
Adjustable-rate mortgages can be particularly relevant in the Super Jumbo market.
Depending on current lender offerings, qualified borrowers may find options structured around an initial fixed period before the loan becomes adjustable.
Potential structures can include:
- 5-year ARM
- 7-year ARM
- 10-year ARM
Availability varies by lender and market conditions.
For borrowers who expect to sell, refinance or substantially reduce the mortgage before the initial fixed period ends, comparing ARM pricing against a longer-term fixed mortgage can be worthwhile.
Can an ARM Have a Lower Super Jumbo Mortgage Rate?
Potentially.
An ARM may sometimes provide a lower initial rate than a comparable long-term fixed-rate Super Jumbo mortgage. However, the lowest initial rate is not automatically the best financing strategy.
You should consider:
- Expected ownership period
- Expected loan payoff period
- Adjustment index
- Margin
- Initial adjustment cap
- Periodic adjustment cap
- Lifetime rate cap
- Potential future payment
The appropriate structure depends on your financial objectives and tolerance for future rate changes.
What Affects Super Jumbo Mortgage Rates in Utah?
Several variables can change pricing simultaneously.
1. Loan Amount
Larger loan amounts may have different pricing tiers and maximum LTV requirements.
2. Credit
Stronger credit can improve access to competitive Super Jumbo programs.
3. LTV
Lower leverage may provide more favorable financing choices.
4. Property Type
A traditional single-family luxury residence may receive different treatment from a unique estate, resort condominium or highly specialized property.
5. Occupancy
Pricing can differ for:
- Primary residences
- Second homes
- Vacation properties
- Investment properties
6. Documentation
Traditional full-documentation financing can be priced differently from alternative-documentation programs.
7. Assets and Reserves
Super Jumbo lenders often pay close attention to liquidity and post-closing reserves.
8. Loan Structure
Fixed-rate, ARM and interest-only structures may have different pricing.
9. Discount Points
Borrowers may have the option to pay discount points to obtain a different interest rate.
Always compare both rate and total cost.
Super Jumbo Rates for $2 Million Mortgage Loans
A $2 million mortgage sits within the range where borrowers may have access to numerous jumbo and Super Jumbo financing options.
Depending on the borrower and property, options can include conventional jumbo-style documentation, bank statements, asset-based qualification and other specialized structures.
The best rate depends on the complete scenario rather than the loan amount alone.
Super Jumbo Rates for $5 Million Mortgage Loans
At approximately $5 million, liquidity, reserves, property value and LTV can become increasingly important.
Qualified high-net-worth borrowers may have access to specialized lending sources that are not typically visible on consumer mortgage-rate websites.
Super Jumbo Rates for $10 Million Mortgage Loans
A $10 million mortgage requires a substantially different underwriting approach than a standard jumbo mortgage.
The lender may closely evaluate:
- Global financial profile
- Liquidity
- Net worth
- Income stability
- Property marketability
- LTV
- Post-closing reserves
- Other real estate obligations
The right question is often not simply, “Who has the lowest advertised rate?”
It is:
Which lender offers the strongest combination of rate, leverage, documentation and structure for this exact $10 million transaction?
Super Jumbo Rates for $20 Million to $30 Million+ Mortgages
Very large residential mortgages are highly specialized.
Qualified borrowers seeking approximately $20 million to $30 million+ may require access to lenders capable of handling exceptionally large residential credit exposure.
Available structures can vary based on borrower strength, liquidity, collateral and the property.
This is an area where working with a mortgage broker who can evaluate multiple specialized lending sources can be particularly valuable.
Super Jumbo Purchase Mortgage Rates Utah
Purchasing a multimillion-dollar property often requires financing to be structured before an offer or closing deadline becomes critical.
Super Jumbo purchase pricing can depend heavily on the down payment and resulting LTV.
A borrower purchasing a $10 million residence with $5 million down creates a very different lending scenario from a borrower requesting $8 million against the same purchase price.
If you are buying a luxury Utah property, compare both your financing options and maximum leverage before choosing a mortgage.
Super Jumbo Refinance Rates Utah
Super Jumbo refinancing may be used to:
- Reduce an existing mortgage rate
- Change from an ARM to fixed financing
- Change the loan term
- Restructure existing debt
- Remove or modify an existing mortgage
- Access a different lender program
Whether refinancing makes financial sense depends on the rate improvement, closing costs, remaining loan term and anticipated ownership period.
Super Jumbo Cash-Out Refinance Rates
Qualified borrowers with substantial equity may also consider Super Jumbo cash-out refinancing.
Cash-out transactions can have different pricing and lower maximum LTV limits than purchase or rate-and-term refinance transactions.
Available proceeds can also depend on:
- Property value
- Existing mortgage balance
- Requested cash out
- Credit
- Liquidity
- Loan amount
- Property type
- Occupancy
Super Jumbo Mortgage Rates for Self-Employed Borrowers
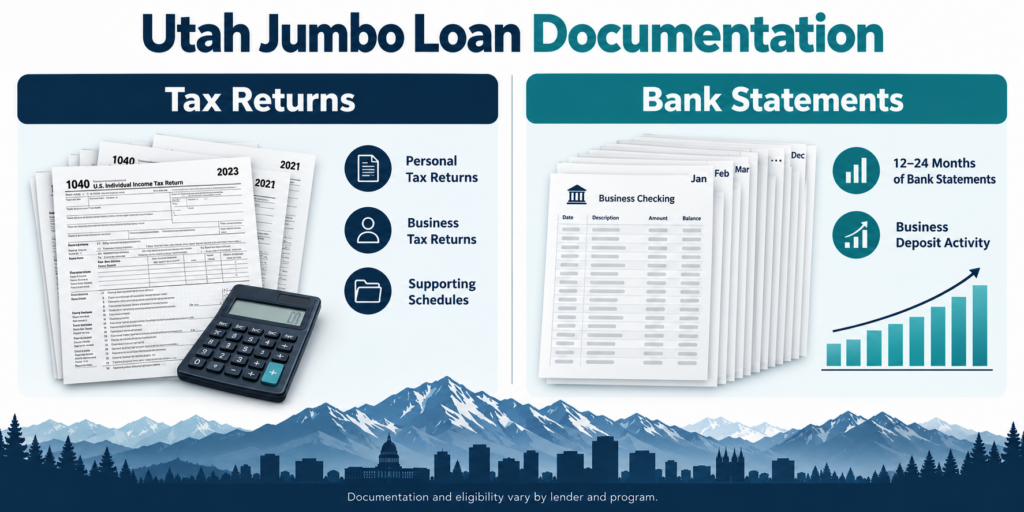
Being self-employed does not automatically prevent a borrower from obtaining Super Jumbo financing.
The primary question is how the lender will document and calculate qualifying income.
Options may include:
Full Documentation
Tax returns, business returns, K-1s and other traditional income documentation may be used.
Bank Statement Super Jumbo Loans
Eligible self-employed borrowers may have access to programs that analyze personal or business bank deposits rather than relying exclusively on taxable income.
Profit and Loss Programs
Select programs may permit qualifying income to be evaluated through eligible P&L documentation.
Asset Depletion
Borrowers with substantial assets may qualify under programs that convert eligible assets into calculated monthly income.
These alternative-documentation programs can carry different rates and costs than traditional full-documentation Super Jumbo mortgages.
Super Jumbo Mortgage Rates in Park City and Deer Valley
Park City and Deer Valley are among Utah's most important markets for Super Jumbo financing.
Luxury real estate can include:
- Ski-in/ski-out homes
- Deer Valley residences
- Luxury condominiums
- Second homes
- Vacation properties
- Mountain estates
- New construction
- Resort-area properties
A Park City Super Jumbo mortgage may require specialized underwriting because of the property's value, occupancy, condominium characteristics or unique luxury features.
Borrowers purchasing in Deer Valley, Empire Pass, Old Town, Canyons Village, Promontory and surrounding Summit County communities should compare lenders experienced with high-value resort real estate.
Super Jumbo Mortgage Rates in Salt Lake City
Luxury-home financing is also important throughout the Salt Lake Valley.
Super Jumbo borrowers may purchase or refinance high-value properties in:
- Salt Lake City
- Holladay
- Cottonwood Heights
- Draper
- Sandy
- Millcreek
- South Jordan
- Salt Lake County
Large custom homes and luxury estates can require mortgage structures well beyond ordinary conforming financing.
Super Jumbo Financing in Alpine and Highland
Alpine and Highland contain some of Utah County's highest-value residential properties.
Qualified buyers purchasing large custom homes or luxury estates may need traditional jumbo or Super Jumbo financing depending on the requested loan amount.
Super Jumbo Mortgage Rates in Heber City and Midway
The Wasatch Back continues to include luxury primary residences, vacation properties and second homes.
Heber City, Midway, Jordanelle, Hideout and surrounding areas can generate financing needs similar to nearby Park City, particularly for high-value mountain and resort-area properties.
Super Jumbo Mortgage Rates in St. George
Southern Utah also has a growing luxury-property market.
Super Jumbo financing may be relevant for eligible properties in:
- St. George
- Ivins
- Santa Clara
- Washington
- Hurricane
- Southern Utah resort communities
Second-home and vacation-property classifications should be reviewed carefully because occupancy can affect available programs and rates.
Super Jumbo vs. Jumbo Mortgage Rates
Jumbo and Super Jumbo mortgages are both non-conforming forms of financing, but very large Super Jumbo loans may involve different lending sources, underwriting requirements and pricing.
| Feature | Jumbo | Super Jumbo |
|---|---|---|
| Loan size | Above applicable conforming limits | Typically substantially larger |
| Lenders | Jumbo lenders | Specialized jumbo/private/portfolio lenders |
| Liquidity review | Important | Often especially important |
| Reserves | Commonly required | Can be substantial |
| Property review | Detailed | May be highly detailed |
| Pricing | Scenario-specific | Highly scenario-specific |
| Alternative documentation | Available | Available through select programs |
| Loan amounts | Lender dependent | May extend to $30M+ through select programs |
There is no universal industry definition establishing exactly where “jumbo” becomes “Super Jumbo.” Individual lenders establish their own program ranges.
How to Get the Best Available Super Jumbo Mortgage Rate
Do not compare Super Jumbo mortgages based on rate alone.
Compare the complete structure.
A useful comparison should include:
- Interest rate
- APR when applicable
- Discount points
- Lender fees
- Loan amount
- LTV
- Fixed versus ARM structure
- Interest-only availability
- Prepayment terms when applicable
- Reserve requirements
- Asset requirements
- Income documentation
- Cash-out restrictions
- Closing timeline
A seemingly lower rate can become less attractive if it requires significantly more cash, assets, points or restrictive loan terms.
Why Use a Mortgage Broker for Super Jumbo Financing?
The Super Jumbo market is fragmented.
Different lending sources can specialize in different borrower profiles, property types and loan sizes.
One lender may be competitive for a $3 million primary residence.
Another may be better suited for a $10 million Park City second home.
A different lender may specialize in $20 million or $30 million high-net-worth transactions.
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified borrowers seeking jumbo, Super Jumbo and alternative-documentation mortgage financing.
Rather than assuming one lender is best for every transaction, the objective is to match the borrower and property with an appropriate lending source.
Super Jumbo Mortgage Rates Utah FAQ
What are Super Jumbo Mortgage Rates Utah today?
There is no single Super Jumbo mortgage rate for every Utah borrower. Rates depend on market conditions plus the loan amount, LTV, credit, assets, property, occupancy, documentation and loan structure. A scenario-specific quote is the most accurate way to determine current pricing.
What is considered a Super Jumbo mortgage in Utah?
There is no government-defined Super Jumbo threshold. The term generally refers to residential mortgages substantially larger than ordinary jumbo loans, often beginning around $1 million to $2 million depending on the lender.
Can I get a $10 million mortgage in Utah?
Qualified borrowers may have access to Super Jumbo financing around $10 million and substantially higher. Approval depends on the borrower, property, LTV, income, assets, liquidity, reserves and lender guidelines.
Can I get a $20 million mortgage in Utah?
Potentially. Specialized Super Jumbo lending programs may accommodate qualified borrowers seeking approximately $20 million in residential financing. These transactions typically require extensive financial and property underwriting.
Can I get a $30 million mortgage in Utah?
Select specialized programs may accommodate qualified borrowers seeking approximately $30 million or more. Maximum financing and LTV depend on the lender, borrower and property.
Are Super Jumbo ARM rates lower than fixed rates?
Sometimes, but not always. ARM pricing may provide a lower initial rate under certain market conditions. Borrowers should compare the initial rate with adjustment terms, caps and their expected holding period.
Can a self-employed borrower get a Super Jumbo mortgage?
Yes. Qualified self-employed borrowers may use traditional documentation or select alternative programs such as bank statements, P&L documentation or asset-based qualification.
Are Super Jumbo loans available for Park City homes?
Yes. Qualified borrowers may use Super Jumbo financing for eligible Park City and Deer Valley primary residences, second homes, vacation properties and certain investment properties.
Compare Super Jumbo Mortgage Rates in Utah
If you are financing a multimillion-dollar Utah property, your mortgage deserves more analysis than an advertised online rate.
UtahLowRate.com can help qualified borrowers evaluate financing for approximately:
$1 Million | $2 Million | $5 Million | $10 Million | $20 Million | $30 Million+
Potential financing includes purchases, refinances, cash-out transactions, fixed-rate mortgages, ARMs, second homes, bank statement loans, asset-based programs and other specialized Super Jumbo structures.
Daniel Paris
Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
UtahLowRate.com
801-604-4949
CTA: Compare My Super Jumbo Mortgage Rates
Mortgage rates, APRs, points, lender fees, loan amounts, LTVs, documentation requirements and program availability can change without notice. All financing is subject to borrower qualification, property eligibility, appraisal, lender/investor guidelines and final underwriting approval.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

