
Content updated: September 29, 2026
Understanding 2026 Utah jumbo loan limits starts with one important distinction: there is not one universal jumbo threshold for every Utah county.
A mortgage is generally considered a jumbo loan when the loan amount exceeds the applicable conforming loan limit for the property's county and number of residential units.
Check My Jumbo Options or call 801-604-4949.
For 2026, the baseline conforming loan limit for a one-unit property is $832,750 in most Utah counties. However, Grand, Wayne, Summit and Wasatch counties have higher one-unit conforming limits.
That means a loan can be considered jumbo in Salt Lake County while the same loan amount may still fall within the conforming range in Summit or Wasatch County.
For most Utah counties, a one-unit mortgage generally enters jumbo territory when the loan amount is above $832,750.
Four Utah counties have higher 2026 one-unit conforming thresholds:
- Grand County: $839,500
- Wayne County: $997,050
- Summit County: $1,150,000
- Wasatch County: $1,150,000
The threshold is based on the loan amount, not the purchase price.
Utah Low Rate offers jumbo and super-jumbo mortgage options for higher-priced Utah properties.
Daniel Paris | UtahLowRate.com
Call: 801-604-4949
2026 Utah Jumbo Loan Limits at a Glance
Most Utah counties: $832,750
Grand County: $839,500
Wayne County: $997,050
Summit County: $1,150,000
Wasatch County: $1,150,000
National high-cost ceiling: $1,249,125
Limits established by: Federal Housing Finance Agency (FHFA)
2026 Utah Jumbo Loan Limits by County
The following table shows the 2026 one-unit conforming limit for every Utah county. A conventional mortgage above the applicable county limit will generally be classified as a jumbo or non-conforming mortgage.
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Utah County | 2026 1-Unit Conforming Limit | Jumbo Generally Begins Above |
|---|---|---|
| Beaver | $832,750 | $832,750 |
| Box Elder | $832,750 | $832,750 |
| Cache | $832,750 | $832,750 |
| Carbon | $832,750 | $832,750 |
| Daggett | $832,750 | $832,750 |
| Davis | $832,750 | $832,750 |
| Duchesne | $832,750 | $832,750 |
| Emery | $832,750 | $832,750 |
| Garfield | $832,750 | $832,750 |
| Grand | $839,500 | $839,500 |
| Iron | $832,750 | $832,750 |
| Juab | $832,750 | $832,750 |
| Kane | $832,750 | $832,750 |
| Millard | $832,750 | $832,750 |
| Morgan | $832,750 | $832,750 |
| Piute | $832,750 | $832,750 |
| Rich | $832,750 | $832,750 |
| Salt Lake | $832,750 | $832,750 |
| San Juan | $832,750 | $832,750 |
| Sanpete | $832,750 | $832,750 |
| Sevier | $832,750 | $832,750 |
| Summit | $1,150,000 | $1,150,000 |
| Tooele | $832,750 | $832,750 |
| Uintah | $832,750 | $832,750 |
| Utah | $832,750 | $832,750 |
| Wasatch | $1,150,000 | $1,150,000 |
| Washington | $832,750 | $832,750 |
| Wayne | $997,050 | $997,050 |
| Weber | $832,750 | $832,750 |
Important: These figures represent conforming loan limits. A loan amount above the applicable limit is generally where jumbo financing begins.
What Is a Jumbo Loan in Utah?
A jumbo mortgage is a conventional mortgage with a loan balance that exceeds the applicable conforming loan limit established by the Federal Housing Finance Agency.
Fannie Mae and Freddie Mac operate within these conforming loan limits. Loans exceeding the applicable threshold are generally considered non-conforming and may require a jumbo mortgage program.
Jumbo loans can be important in higher-priced Utah markets, including:
- Park City
- Deer Valley
- Canyons Village
- Heber City
- Midway
- Holladay
- Cottonwood Heights
- Draper
- Alpine
- Highland
- St. George
- Ivins
Learn more about Utah jumbo mortgages.
Why Utah Does Not Have One Jumbo Loan Limit
The phrase Utah jumbo loan limit can be misleading because FHFA establishes conforming limits by geographic area and property-unit count.
For most Utah counties, the 2026 one-unit conforming limit is $832,750.
However, housing costs result in higher limits in certain areas.
Summit County Jumbo Loan Limit 2026
The 2026 one-unit conforming loan limit in Summit County is $1,150,000.
This is particularly important for buyers financing homes in areas such as Park City, Deer Valley, Canyons Village, Kamas, Hideout and other Summit County communities.
A $1 million mortgage, for example, exceeds the conforming limit in Salt Lake County but remains below the one-unit conforming limit in Summit County.
Explore jumbo loans in Park City, Utah.
Wasatch County Jumbo Loan Limit 2026
The 2026 one-unit conforming limit in Wasatch County is $1,150,000.
This higher threshold can apply to eligible properties in:
- Heber City
- Midway
- Jordanelle-area communities
- Other Wasatch County locations
Because the county limit is higher, some mortgages that would require jumbo financing elsewhere in Utah may remain conforming in Wasatch County.
Salt Lake County Jumbo Loan Limit 2026
The 2026 one-unit conforming limit in Salt Lake County is $832,750.
A conventional mortgage above that amount generally enters jumbo territory.
The threshold applies throughout Salt Lake County, including:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale, Midvale and surrounding communities.
Utah County Jumbo Loan Limit 2026
For a one-unit property in Utah County, the 2026 conforming loan limit is $832,750.
This applies to communities including:
- Provo
- Orem
- Lehi
- Alpine
- Highland
- American Fork
- Pleasant Grove
- Saratoga Springs
- Eagle Mountain
- Spanish Fork
A mortgage above the applicable conforming threshold will generally require jumbo or another non-conforming financing option.
Washington County and St. George Jumbo Loan Limit
The 2026 one-unit conforming limit in Washington County is $832,750.
That includes properties in:
- St. George
- Washington
- Ivins
- Santa Clara
- Hurricane
- Surrounding Washington County communities
Higher-priced homes in Southern Utah can therefore require jumbo financing even when the purchase price itself is not dramatically above the conforming threshold.
Jumbo Loan Limit vs. Home Purchase Price
One of the most common misunderstandings about jumbo mortgages is assuming the loan limit is also a home-price limit.
It is not.
The conforming limit applies to the mortgage amount, not directly to the purchase price.
Example
Suppose you purchase a Salt Lake County home for $1,000,000 and make a $200,000 down payment.
Your mortgage would be:
$1,000,000 - $200,000 = $800,000
Because $800,000 is below Salt Lake County's 2026 one-unit conforming limit of $832,750, the purchase price alone would not force the mortgage into jumbo classification.
Now assume the same home is purchased with a $900,000 mortgage.
That loan exceeds the applicable $832,750 conforming threshold and would generally require jumbo or another non-conforming financing program.
What Changed With Utah Jumbo Loan Limits in 2026?
The national baseline one-unit conforming limit increased from $806,500 in 2025 to $832,750 in 2026.
That is an increase of $26,250, or approximately 3.26%.
FHFA adjusts the baseline conforming limit annually based on changes in its national house-price data.
Higher conforming limits can allow borrowers to finance larger balances while potentially remaining within conforming loan guidelines.
2026 Utah Jumbo vs. Conforming Loans
| Feature | Conforming Mortgage | Jumbo Mortgage |
|---|---|---|
| Loan amount | At or below applicable county limit | Above applicable county limit |
| Fannie/Freddie eligibility | Potentially eligible | Generally not eligible |
| Underwriting | Agency guidelines | Lender/investor guidelines |
| Reserves | Program dependent | Often more substantial |
| Down payment | Program dependent | Program dependent |
| Property types | Agency-eligible properties | Program dependent |
| Maximum loan size | County conforming limit | Can extend well above conforming limits |
Jumbo does not automatically mean a worse mortgage or a dramatically higher rate. Pricing depends on market conditions, credit profile, loan-to-value ratio, property type, occupancy, reserves and the specific jumbo investor.
How Much Can You Borrow With a Jumbo Loan in Utah?
There is no single universal maximum for Utah jumbo mortgages.
Available loan amounts depend on the lender or investor and the borrower's financial profile.
Utah Low Rate works with jumbo and super-jumbo mortgage programs for qualifying borrowers, including financing scenarios extending into multi-million-dollar loan amounts.
Potential options can include:
- Primary residences
- Second homes
- Investment properties
- Purchase financing
- Rate-and-term refinancing
- Cash-out refinancing
- Fixed-rate mortgages
- Adjustable-rate mortgages
- Interest-only structures on eligible programs
- Asset-based solutions
- Pledged-asset strategies
- Bridge financing
- Construction-to-permanent financing
Explore Utah super-jumbo mortgage options.
What Do Jumbo Lenders Look For?
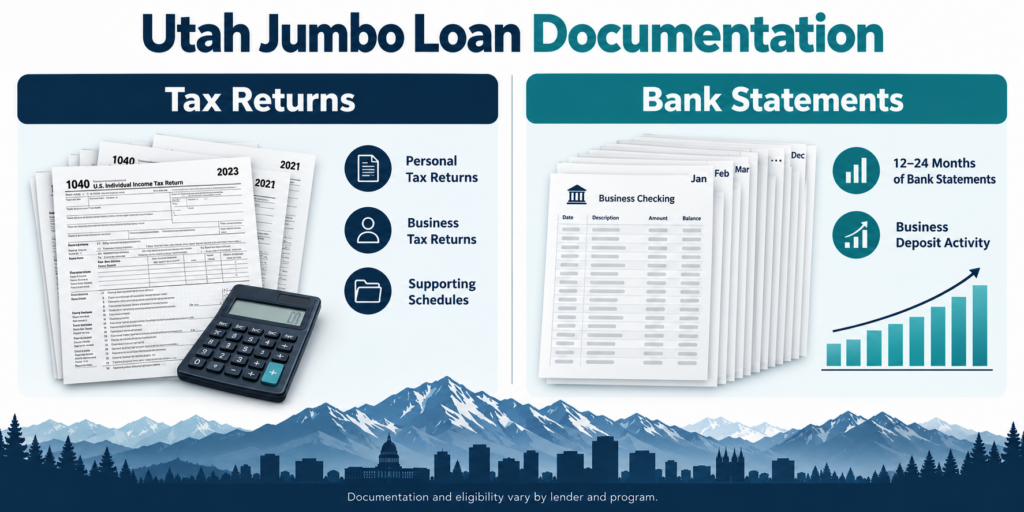
Jumbo mortgages are not governed by one universal underwriting standard.
Depending on the program, lenders may review:
Credit: Stronger credit can expand available pricing and program choices.
Loan-to-value ratio: The relationship between the loan amount and property value can materially affect jumbo eligibility.
Income: Borrowers generally need sufficient qualifying income under the selected program.
Assets: Jumbo loans may require verification of funds for down payment, closing costs and reserves.
Reserves: Some programs require borrowers to maintain several months of housing payments or other assets after closing.
Property: High-value, unique and luxury properties may receive additional appraisal or underwriting review.
Jumbo Loans for Self-Employed Utah Borrowers
Traditional tax-return underwriting is not the only potential route to jumbo financing.
Depending on the borrower's circumstances, alternative documentation programs may include:
- Bank statement mortgage loans
- 12- or 24-month bank statements
- Business bank statements
- Personal bank statements
- Profit-and-loss programs
- Asset-depletion programs
- DSCR financing for qualifying investment properties
- Other non-QM mortgage programs
These programs have their own underwriting requirements and should not be confused with standard Fannie Mae or Freddie Mac conforming financing.
Jumbo Loans in Park City and Deer Valley
Park City is one of Utah's most important markets for jumbo and super-jumbo financing.
Luxury homes, second homes and investment properties in areas such as Deer Valley, Empire Pass, Old Town, Canyons Village and surrounding communities can require financing well above standard conforming limits.
County location matters.
Properties within Summit County use the applicable Summit County conforming threshold, while properties in neighboring Wasatch County use the Wasatch County threshold.
For 2026, both counties have a $1,150,000 one-unit conforming limit.
Compare Park City jumbo mortgage programs.
What is the 2026 jumbo loan limit in Utah?
For most Utah counties, a one-unit loan generally becomes jumbo when it exceeds $832,750.
Does Park City have a higher limit?
Yes. Summit County's 2026 one-unit conforming limit is $1,150,000.
What is the Wasatch County limit?
The 2026 one-unit conforming limit is $1,150,000.
What is the Salt Lake County limit?
The 2026 one-unit conforming limit is $832,750.
Is the jumbo threshold based on purchase price?
No. The threshold applies to the loan amount.
Frequently Asked Questions About 2026 Utah Jumbo Loan Limits
What is considered a jumbo loan in Utah in 2026?
A conventional mortgage generally becomes a jumbo loan when its balance exceeds the applicable FHFA conforming loan limit for the property's county and number of units.
What is the 2026 jumbo loan threshold in Salt Lake County?
The one-unit conforming limit is $832,750. A conventional loan above that amount generally enters jumbo territory.
What is the 2026 jumbo loan threshold in Summit County?
Summit County has a $1,150,000 one-unit conforming limit for 2026.
What is the 2026 jumbo loan threshold in Wasatch County?
Wasatch County also has a $1,150,000 one-unit conforming limit for 2026.
Does a $900,000 Utah home automatically require a jumbo loan?
No. Jumbo classification is based primarily on the mortgage amount, not simply the property's purchase price. A sufficient down payment could reduce the mortgage below the applicable conforming threshold.
Can I get a jumbo loan with less than 20% down?
Potentially. Jumbo loan-to-value requirements vary considerably by lender, loan amount, occupancy, credit profile and program.
Are jumbo mortgage rates always higher?
No. Jumbo pricing is determined by market conditions and the individual loan scenario. In some market environments, jumbo pricing can be competitive with conforming financing.
Can self-employed borrowers qualify for jumbo mortgages?
Yes. Depending on the program, borrowers may qualify through traditional documentation or alternative documentation such as bank statements, profit-and-loss statements, asset depletion or other non-QM methods.
Are jumbo loans available for second homes in Utah?
Yes, qualifying jumbo programs can be available for second homes. This can be particularly relevant in Park City, Deer Valley, Heber City and other Utah resort markets.
Compare Your Utah Jumbo Mortgage Options
The county loan limit is only the starting point.
The right financing structure can depend on your loan amount, property location, down payment, credit profile, income documentation, reserves, occupancy and long-term financial goals.
Daniel Paris has more than 27 years of mortgage experience and works with conventional, jumbo, super-jumbo and alternative-documentation mortgage programs through UtahLowRate.com.
Get a scenario-specific review instead of relying only on a generic online mortgage calculator.
Daniel Paris
UtahLowRate.com
801-604-4949
Compare Jumbo Programs | Check My Jumbo Options | Ask a Mortgage Question
Mortgage programs, rates, loan limits and underwriting guidelines are subject to change. Loan approval is subject to applicable underwriting requirements. County and property eligibility should be verified for each transaction.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

