
Utah Self-Employed Jumbo Mortgage Guide: Documents, Income, and Loan Choices
By Daniel Paris, Utah Mortgage Broker, NMLS #243976, with more than 27 years of mortgage lending experience
Last updated: September 27, 2026
Quick answer: Self-employed borrowers can qualify for a Utah jumbo mortgage by documenting sufficient income or eligible assets and meeting the selected lender’s credit, down payment, reserve, and property requirements. Some programs analyze tax returns; others may use qualifying bank deposits or another approved method. Start by checking the loan limit for the property’s county, then compare the documentation methods that fit your finances.
A business owner’s revenue, taxable income, and available cash are three different numbers. That distinction matters when financing a higher-value home in Park City, Salt Lake City, Heber City, Lehi, or St. George. The lender must determine which income it can use, whether the business remains viable, and whether the borrower has enough funds for closing and reserves.
Daniel Paris of UtahLowRate.com helps self-employed borrowers across Utah compare jumbo programs available through wholesale mortgage sources. This guide explains what to gather, which questions to ask, and how to compare the results.
Step 1: Check whether the proposed loan is jumbo
A jumbo loan generally exceeds the conforming limit that applies to the property. The loan amount matters—not just the purchase price. Subtract the planned down payment from the purchase price to estimate the loan amount, then check the county’s limit for that property type.
The Federal Housing Finance Agency’s 2026 one-unit limit is $832,750 in Salt Lake, Utah, and Washington counties, while Wasatch County’s is $1,150,000. County limits can differ, so a loan that is jumbo for a home in St. George may fall within the conforming limit for a similarly priced home in Heber City. Verify the applicable county and current limit before selecting a program. See FHFA’s 2026 county limits.
For example, a $1.4 million purchase with a $350,000 down payment produces a proposed $1.05 million loan. The property’s county and number of units determine how that amount compares with its conforming limit. A conforming option, if otherwise eligible, is worth comparing with jumbo financing.
Step 2: Choose an income-documentation route to evaluate
The best starting point is the method that accurately documents your finances and fits the lender’s rules. Ask for more than one calculation when your business records support it.
Traditional tax-return underwriting
A traditional lender may analyze personal returns, applicable business returns, ownership, income trends, and current business activity. Strong gross sales alone do not establish qualifying income. The lender examines the income available under its underwriting method and may ask about significant changes or losses.
Fannie Mae’s self-employment guidance explains common concepts in reviewing self-employed income. It provides useful context, although an individual jumbo lender sets its own nonconforming loan requirements.
Bank statement underwriting
Certain jumbo programs may use eligible deposits in personal or business bank statements to calculate income. Many programs examine 12 or 24 months of statements. They may exclude transfers, loan proceeds, and other deposits that do not represent business earnings. Business-statement programs also account for expenses under the investor’s rules.
A bank statement mortgage still involves documented income and full underwriting. It does not turn total deposits into qualifying income dollar for dollar. For program-specific details, see jumbo bank statement loans in Utah.
Other lender-approved methods
Depending on the borrower and lender, a profit-and-loss or asset-based program may deserve review. These options can differ substantially in documentation, loan amount, pricing, and eligible occupancy. Have the broker confirm that a particular program is available for the proposed property and transaction before relying on it.
Step 3: Build a clean document package
Prepare the records that explain both the business and the mortgage transaction. A complete package lets a lender calculate income sooner and identify issues before a purchase deadline.
Start with:
- The target purchase price or estimated current property value
- Proposed down payment, loan amount, and whether the home will be a primary residence, second home, or investment property
- Recent personal asset statements showing funds for closing and reserves
- A summary of your business structure, ownership, and time in business
- Personal and applicable business tax returns if evaluating traditional underwriting
- Complete personal or business bank statements for the period required by a bank statement program
- An explanation of large transfers, unusual deposits, or major changes in revenue
- Information about existing mortgages and other debts
The exact list depends on the lender. Keep original statements complete and avoid moving funds solely to make one account appear stronger without documenting their source. If business funds will pay closing costs, ask how the lender evaluates access to those funds and the effect on business operations.
UtahLowRate.com’s bank statement income calculator guide can help you prepare questions about eligible deposits. A lender’s actual calculation controls the application.
Step 4: Review credit, equity, and reserves together
Jumbo approval depends on the complete financial picture. A lender may approve one combination of loan amount, credit, down payment, and reserves while declining another. Requirements can also differ between tax-return and alternative-documentation programs.
Before requesting a quote, identify how much cash you can use for the down payment and how much you want to retain afterward. Reserves are funds remaining after closing that meet the lender’s rules. A borrower buying a Park City second home, for example, should not assume that every dollar in a business account counts toward required personal reserves.
Review the property early, too. A primary home in Salt Lake County, a Deer Valley second home, and an investment property in Washington County may have different eligibility and loan-to-value limits. For a broader view of loan purposes and property types, read Utah jumbo mortgage options.
Step 5: Compare loan choices using the same assumptions
Compare offers for the same property, loan amount, down payment, occupancy, and lock period. Otherwise, a lower advertised rate may reflect a different transaction.
Ask the mortgage broker to explain:
- Qualifying income: What amount does each program recognize, and how was it calculated?
- Cash needed: What are the down payment, closing costs, and required reserves?
- Rate and APR: Are discount points or other loan charges included?
- Payment structure: Is the rate fixed or adjustable? If adjustable, when can it change?
- Program restrictions: Are there occupancy, property, cash-out, or prepayment terms to review?
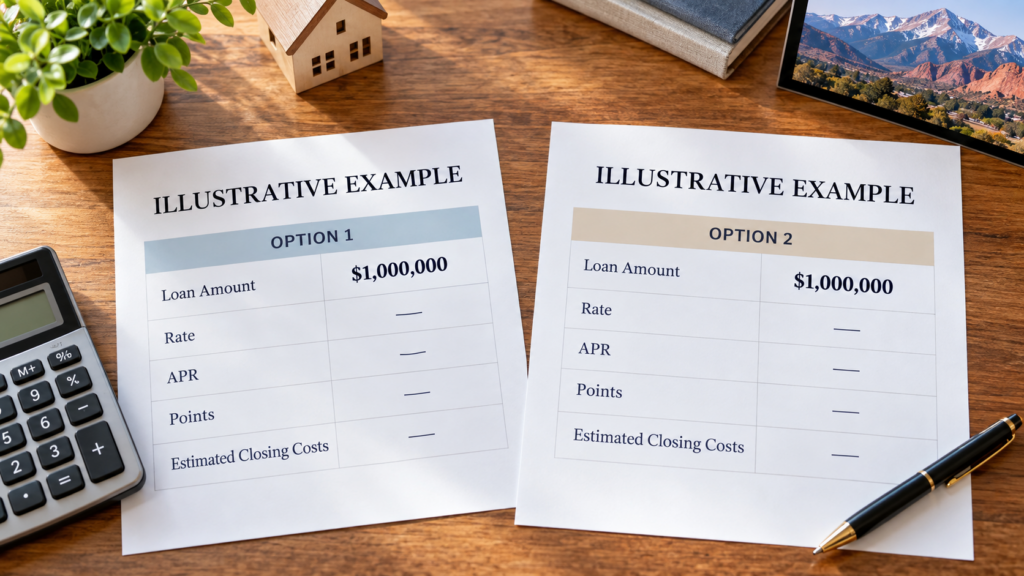
The Consumer Financial Protection Bureau explains how to compare Loan Estimates and why both interest rate and fees matter. Request a Loan Estimate when you reach the application stage, and compare written terms rather than relying on a verbal rate alone.
Consider a hypothetical Lehi business owner purchasing a home with a $1.1 million proposed mortgage. Tax returns may support one loan amount, while eligible bank deposits may support another. The bank statement option could require different equity, reserves, or pricing. A side-by-side review shows whether its income advantage improves the whole financing plan.
Step 6: Address local property and timing details
Tell the lender about property details as early as possible. In Park City and Deer Valley, a buyer may be considering a second home or a property with association rules. Around Heber City and Midway, the higher Wasatch County conforming limit makes an early loan-limit check useful. Along the Wasatch Front, business owners in Salt Lake City, Draper, and Sandy may have multiple income sources or business entities to document.
In Utah County, a Lehi or Alpine borrower with rapidly growing revenue should be ready to explain how current business activity compares with prior returns. In St. George and Ivins, borrowers considering a second home should clarify intended occupancy rather than assume it will be treated like a primary residence.
Do the initial income and asset review before making an offer when possible. A preliminary review cannot guarantee approval, but it can uncover missing statements, an income-calculation issue, or a reserve shortfall while there is still time to consider another eligible program.
Frequently asked questions
Can I get a jumbo mortgage in Utah if I own a business?
Yes. A business owner can qualify for a Utah jumbo mortgage by meeting a lender’s documented income or asset, credit, equity, reserve, and property requirements. The lender’s treatment of business income depends on the program.
Can I use bank statements to buy a home in Park City?
Potentially. Some jumbo bank statement programs allow qualified self-employed borrowers to document income with eligible deposits for a Park City purchase. The property, occupancy, loan amount, and borrower must meet the selected lender’s rules.
How many bank statements do I need for a self-employed jumbo loan?
Many bank statement programs review either 12 or 24 months of complete statements. The required period and eligible account type vary by lender and program.
Does every business deposit count as income for my mortgage?
No. A lender may remove transfers, borrowed funds, and other ineligible deposits and apply an expense calculation. Total deposits should not be treated as approved qualifying income.
How much cash should I keep after closing a jumbo loan?
Keep enough to meet the selected lender’s reserve requirement and your own financial needs. The required amount depends on the loan, occupancy, documentation method, and borrower profile.
Should I compare a conforming loan before choosing a jumbo loan?
Yes. Check the property county’s current conforming limit and compare any eligible conforming option with jumbo offers. Loan pricing and qualification rules can differ, especially in Utah counties with different limits.
Review your scenario with a Utah jumbo mortgage broker
Daniel Paris — UtahLowRate.com
Utah Mortgage Broker | NMLS #243976 | More than 27 years of mortgage lending experience
Phone: 801-604-4949
Website: UtahLowRate.com
Service area: Utah statewide, including Salt Lake City, Park City, Heber City, Lehi, and St. George
Specialties: Jumbo and super-jumbo financing, self-employed mortgages, and bank statement loans
Send Daniel your target property location, proposed loan amount, business structure, and available income documents to begin comparing eligible programs.
Mortgage program availability, rates, APRs, fees, documentation, and approval requirements can change. All financing is subject to lender review of the borrower and property.

