
How to Qualify for a DSCR Loan in Utah: A Rental Property Investor’s Guide
By Daniel Paris, Utah Mortgage Broker, UtahLowRate.com | More than 27 years of mortgage lending experience
Last updated: September 27, 2026
Quick answer: To qualify for a DSCR loan in Utah, an investor generally needs an eligible rental property, acceptable credit, sufficient down payment or equity, documented funds and a lender-approved rent analysis. The lender compares qualifying monthly rent with the property’s required monthly housing payment to calculate its debt service coverage ratio. Exact thresholds and documentation vary by program.
If you are purchasing a rental in Salt Lake City, refinancing a Park City investment property or reviewing a St. George acquisition, start with the numbers on the property. A DSCR loan may let you qualify primarily through eligible rental income rather than conventional employment-income calculations. It is still a fully underwritten mortgage. UtahLowRate.com mortgage broker Daniel Paris can compare available wholesale programs for qualified Utah investors.
What does a DSCR lender measure?
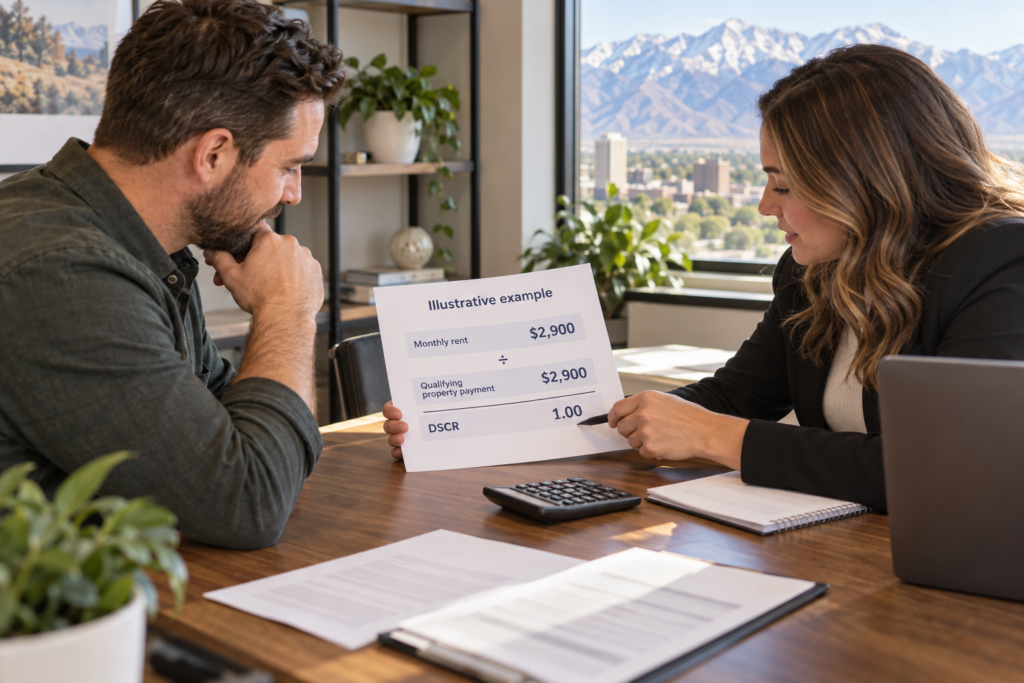
DSCR stands for debt service coverage ratio. In a common residential investor calculation, the lender divides eligible monthly rent by the required monthly property payment. That payment often includes principal, interest, property taxes, homeowners insurance and applicable association dues. Ask each lender exactly which payment items and rental-income adjustments it uses; program definitions differ.
Illustrative calculation: If a Salt Lake City rental has $2,900 in lender-accepted monthly rent and a $2,900 qualifying monthly payment, its estimated DSCR is 1.00 ($2,900 ÷ $2,900). If the payment is $3,223.75, the estimated ratio is 0.90. A ratio of 1.00 means the accepted rent equals the payment used in this calculation. It does not mean the property breaks even after repairs, vacancies, utilities, management or other operating costs.
An appraisal rent schedule, current lease or other lender-approved evidence may establish rent. An investor’s projected listing price alone may not qualify. For a vacant home in Utah County or a short-term rental in Park City, confirm the exact evidence the lender will accept before relying on a projected cash flow figure.
How to qualify for a DSCR loan in Utah, step by step
1. Confirm that the property and transaction fit
DSCR programs generally serve non-owner-occupied investment properties. Tell the broker whether you are buying, refinancing to change the rate or term, or seeking cash out. Share the property type, address, purchase price or estimated value, and whether the home is already rented. A second home used personally is not automatically an eligible DSCR rental.
A single-family rental in Draper, a condominium in Salt Lake City and a vacation rental near Park City may receive different treatment. Condo eligibility, acreage, property condition and short-term rental rules can differ by lender. Local permission to operate a short-term rental is a separate question from mortgage eligibility; check the applicable city, county and HOA rules before making an offer.
2. Establish lender-accepted rental income
For a leased property, gather the signed lease and payment history if available. For a purchase or vacant property, the lender may ask an appraiser for a market-rent schedule. Some programs consider short-term rental income, but they may require specific documentation, history or an approved market analysis. Do not assume a nightly-rate estimate from a booking site will be accepted as qualifying income.
This step matters in Park City and Heber City, where seasonal demand can make gross annual projections look stronger than stable monthly income. It also matters for long-term rentals in Salt Lake County and St. George. Ask how the selected program converts the documented rent into its qualifying monthly figure.
3. Calculate the ratio using the full required payment
Get a realistic estimate of principal and interest, taxes, insurance and HOA dues, where applicable. Divide the lender-accepted monthly rent by the payment it uses. Then stress-test the scenario with a lower rent or higher insurance bill. A small change can move a 1.00 ratio below the program’s threshold.
Some investors seek a program that permits a ratio below 1.00 or even a no-ratio scenario. Availability and pricing depend on the lender, credit, equity, reserves, loan size and property. A low or zero ratio does not create an automatic approval. Review the Utah DSCR mortgage overview for the broader program and use a broker quote for an actual property.
4. Review credit, down payment and cash reserves
Lenders evaluate credit and the loan-to-value ratio alongside DSCR. A higher down payment or more equity can change which programs are available and how a loan is priced. Funds needed at closing and post-closing reserves are separate: having enough for the down payment does not necessarily satisfy a reserve requirement.
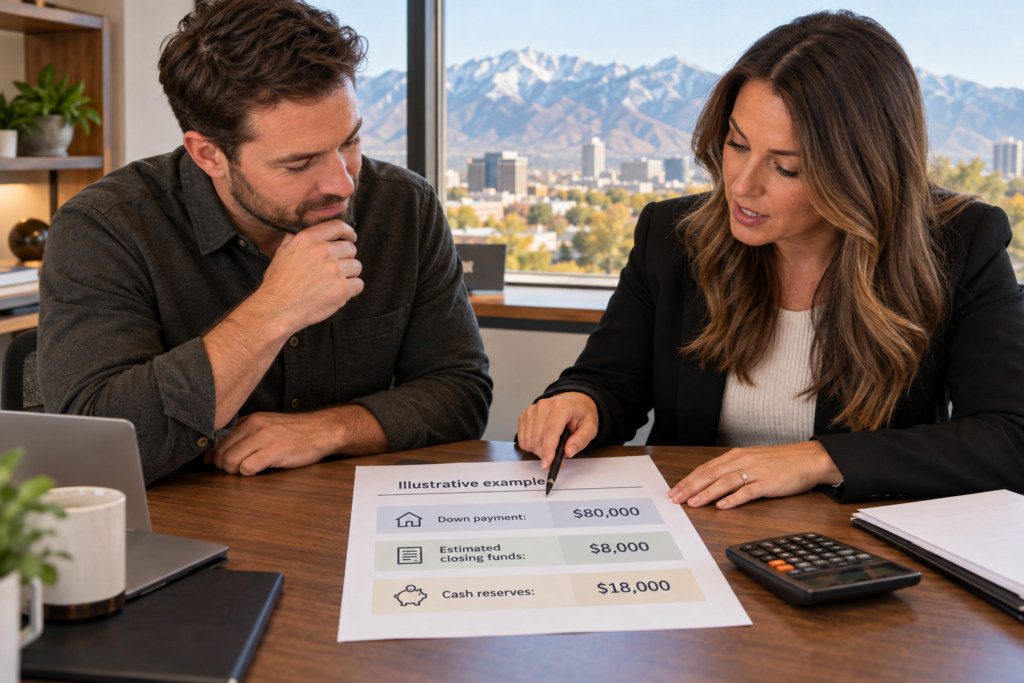
Have recent asset statements ready and explain any large deposits or funds held in an entity account. Ask whether gifts, business assets or proceeds from another property qualify under the chosen program. A St. George investor buying a first rental and a Park City investor refinancing a portfolio may face different reserve and documentation rules. Avoid treating a lender’s marketing grid as an approval commitment.
5. Assemble a clean property and borrower file
A typical initial package can include the purchase contract or mortgage statement, property address, lease and rent evidence, insurance estimate, tax and HOA figures, identification, entity documents if purchasing through an LLC, and statements showing closing funds and reserves. A cash-out refinance may also require a current mortgage payoff and information on how long you have owned the property.
DSCR financing often reduces reliance on personal W-2 or tax-return income for qualification, but the lender may still request information needed for identity, assets, property ownership and underwriting. Keep all figures consistent across the application, lease, insurance quote and appraisal documents. Send sensitive documents through the lender’s secure process, not a public form.
6. Compare complete offers before committing
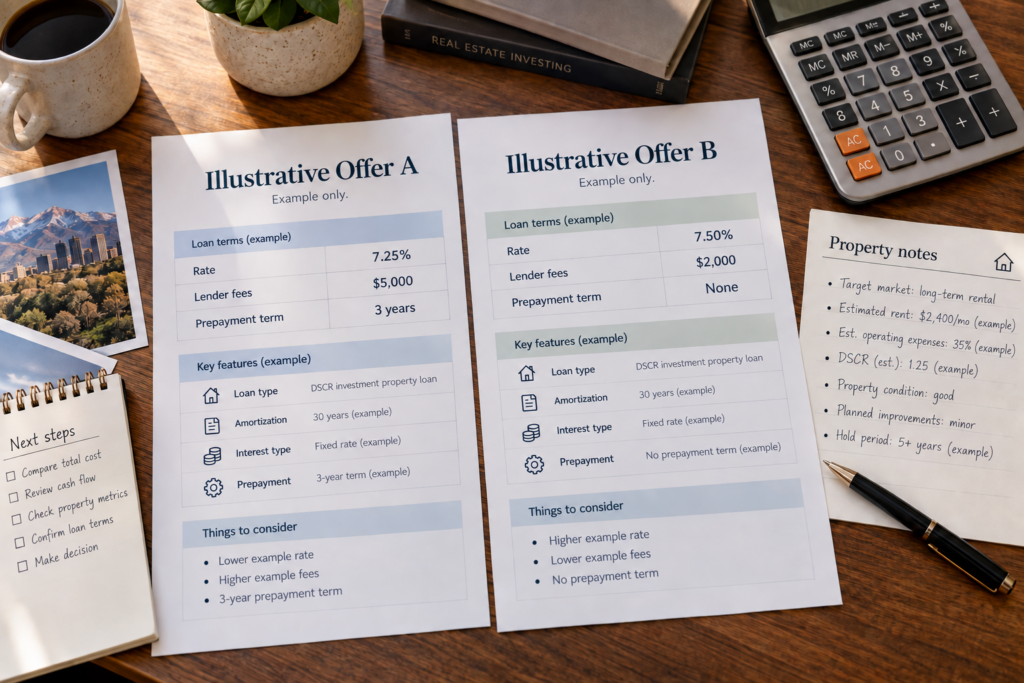
Ask for the note rate, APR when applicable, points, lender fees, cash needed to close, monthly payment, reserve requirement, rate-lock period and any prepayment penalty. Also ask whether the quote assumes a particular DSCR, credit score, LTV, property type or lease structure. An apparently lower rate can have higher upfront costs or less flexible payoff terms.
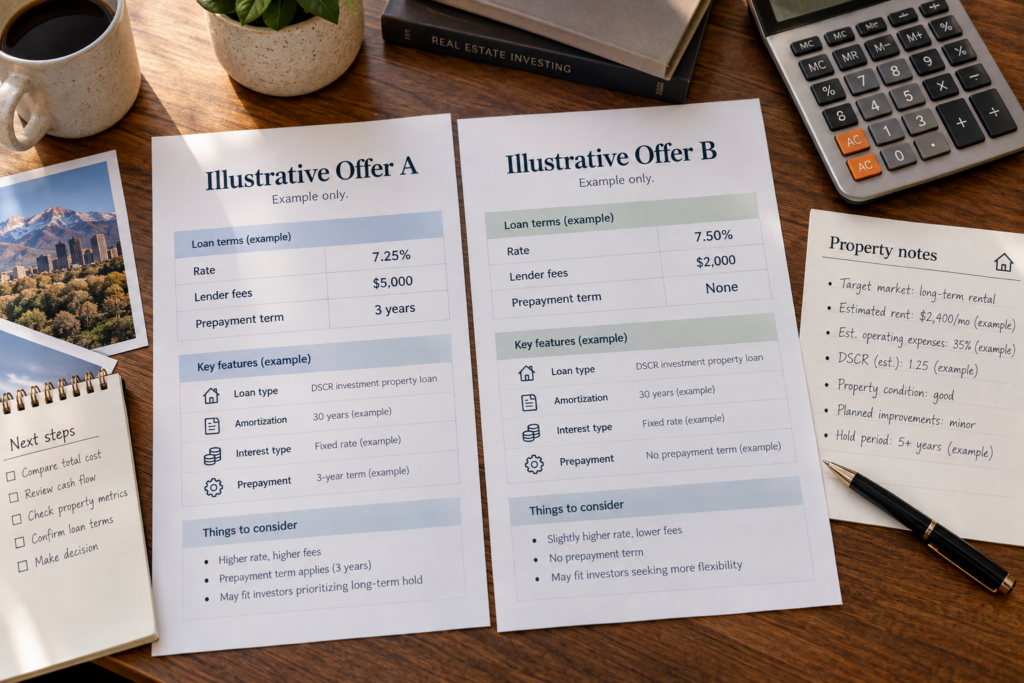
The Consumer Financial Protection Bureau’s Loan Estimate comparison guide explains how to compare mortgage offers, and its prepayment-penalty guidance identifies a term investors should check carefully. Ask which disclosure format applies to your particular business-purpose transaction. For context, Fannie Mae’s rental-income guidance governs agency lending; DSCR loans are lender-specific non-QM products rather than Fannie Mae DSCR loans.
When should a Utah investor compare DSCR with a conventional loan?
Compare both if you have stable personal income and the property is eligible for agency financing. Conventional underwriting analyzes the borrower’s income, liabilities and rental-income treatment under agency rules. A DSCR lender typically focuses more heavily on property rent relative to its required payment. Neither route is universally cheaper or easier.
For an investor with several financed rentals or complex self-employment income, a DSCR structure may be useful. For a borrower with strong documented income and a modest loan amount, conventional financing may compare well. Read UtahLowRate.com’s conventional mortgage options and its 2026 discussion of Fannie Mae rental-income guidelines to frame the comparison. For a self-employed investor also considering an owner-occupied purchase, Utah bank statement loans use a different income method.
Common Utah DSCR loan mistakes to avoid
- Using advertised rent instead of accepted rent. A listing estimate may differ from an appraisal rent schedule or documented lease.
- Leaving taxes, insurance or HOA dues out of the denominator. A partial payment makes the ratio look stronger than the lender’s calculation.
- Confusing DSCR with net operating income. A 1.00 ratio can still leave an investor short after maintenance, turnover and management costs.
- Assuming every short-term rental qualifies. Property, documentation and local operating rules must all be checked.
- Ignoring prepayment terms. This can matter if you expect to sell or refinance soon.
- Quoting a loan without a property scenario. Credit, equity, rent, occupancy and transaction purpose all affect available terms.
These checks are especially useful when comparing a long-term rental in Salt Lake County with a seasonal property in Summit or Wasatch County. Build a property-level budget as well as a lender-level qualification calculation.
Frequently asked questions about Utah DSCR loans
Can I get a DSCR loan in Utah without using my tax returns to qualify?
Some Utah DSCR programs qualify eligible investment properties primarily from lender-accepted rental income rather than the borrower’s personal tax-return income. The lender still verifies the borrower, assets, property and other program requirements.
What happens if my Utah rental property has a DSCR below 1.00?
A ratio below 1.00 means the accepted rent is less than the payment used for that calculation. Some lenders may consider a below-1.00 or no-ratio program, usually with different equity, credit, reserve or pricing requirements; eligibility is lender-specific.
Can I use a DSCR loan for a Park City short-term rental?
Possibly, if a lender accepts the property, the proposed rental-income evidence and the transaction. Verify local short-term rental rules and HOA restrictions separately before assuming the property can operate as planned.
Can I refinance a Salt Lake City rental property with a DSCR loan?
Many DSCR programs consider eligible rate-and-term or cash-out refinances of investment properties. Available cash out depends on value, existing liens, seasoning, credit, reserves and the lender’s current guidelines.
How much down payment do I need for a Utah DSCR loan?
There is no single down payment that applies to every DSCR lender. The required amount depends on credit, DSCR, property type, loan size and program; request a property-specific LTV quote before planning cash to close.
Discuss a Utah rental-property scenario
Daniel Paris | UtahLowRate.com | Utah mortgage broker
Phone: 801-604-4949
Website: UtahLowRate.com
Service area: Utah statewide, including Salt Lake City, Park City, Heber City, Utah County and St. George.
Specialty: Comparing wholesale mortgage options, including eligible DSCR and other non-QM investment-property financing.
Share the property address, estimated value or purchase price, expected rent, current payment if refinancing, credit range and available funds. Daniel can identify which lender questions matter for your scenario and help you compare current terms. Ask for a Utah DSCR loan review. All loans are subject to lender guidelines, property eligibility, underwriting and approval; illustrations above are not a rate or approval offer.

