
Content updated: September 29, 2026
Luxury, High-Balance and Super Jumbo Mortgage Financing in Southern Utah
Buying or refinancing a higher-value home in St. George, Utah may require financing beyond the limits of a standard conforming mortgage.
Check My Jumbo Options or call 801-604-4949.
A jumbo loan in St. George, Utah can provide financing for qualified borrowers purchasing luxury homes, custom residences, second homes and other eligible high-value properties throughout St. George, Washington County and Southern Utah.
Daniel Paris of UtahLowRate.com helps borrowers compare jumbo mortgage programs from multiple wholesale lending sources rather than relying on a single loan program.
Whether you are purchasing a primary residence in St. George, a second home near Entrada, a custom property in Ivins or refinancing a high-value Southern Utah residence, the goal is to identify a jumbo mortgage structure that fits the property, loan amount and your financial profile.
Daniel Paris
UtahLowRate.com
Call: 801-604-4949
NMLS #243976
Quick Answer: What Is a Jumbo Loan in St. George, Utah?
A jumbo loan in St. George, Utah is generally a mortgage that exceeds the applicable conforming loan limit for the property and therefore cannot be purchased as a standard conforming loan by Fannie Mae or Freddie Mac.
Jumbo mortgages can help qualified borrowers finance higher-priced primary residences, second homes, vacation properties and certain investment properties in St. George and throughout Southern Utah.
Because jumbo mortgages are not standard conforming loans, requirements for credit, down payment, reserves, income documentation and property eligibility can vary significantly between lenders.
St. George Jumbo Loan Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Jumbo Mortgage Feature | Potential Options |
|---|---|
| Property Location | St. George, Washington County and Southern Utah |
| Loan Purpose | Purchase, rate-and-term refinance or cash-out refinance |
| Occupancy | Primary, second home and eligible investment properties |
| Property Types | Luxury homes, custom homes and other eligible residences |
| Income Documentation | Traditional and select alternative-documentation programs |
| Self-Employed Borrowers | Multiple qualification methods may be available |
| Large Loan Amounts | Jumbo and super jumbo financing |
| Rate Options | Fixed and adjustable-rate programs may be available |
| Reserves | Requirements depend on loan size and program |
| Down Payment | Varies according to LTV, loan amount and borrower profile |
Important: Jumbo guidelines are lender- and program-specific. Availability and qualification are not guaranteed.
What Is a Jumbo Mortgage?
A jumbo mortgage is a home loan that is too large to qualify as a standard conforming mortgage based on the applicable conforming loan limit.
That distinction matters because jumbo mortgages are generally underwritten according to the requirements of the lender or investor providing the financing.
As a result, one jumbo lender's guidelines can differ substantially from another's.
Differences may involve:
- Maximum loan amount
- Credit requirements
- Loan-to-value ratio
- Down payment
- Debt-to-income ratio
- Cash reserves
- Income documentation
- Self-employment requirements
- Property type
- Occupancy
- Cash-out limits
- Appraisal requirements
This is one reason comparing multiple jumbo programs can be particularly valuable when financing a high-value Southern Utah property.
When does a St. George Mortgage Become a Jumbo Loan?
A mortgage generally becomes a jumbo loan when the loan amount exceeds the conforming loan limit applicable to the property.
Conforming loan limits can change annually and may differ depending on property characteristics and applicable federal guidelines.
The important distinction is between the purchase price and the loan amount.
A high-priced St. George home does not automatically require a jumbo mortgage.
For example, a buyer making a sufficiently large down payment could potentially keep the mortgage within conforming limits even when the home's purchase price exceeds those limits.
Conversely, a borrower seeking a larger loan amount may cross into jumbo financing.
For current limits, borrowers should verify the applicable conforming loan limit before deciding whether jumbo financing is necessary.
Jumbo Loan Requirements in St. George
Jumbo mortgages typically receive more detailed underwriting than many conventional conforming mortgages because of the larger amount of money being financed.
The lender may evaluate:
Credit Profile
Credit score is important, but lenders may also review the borrower's overall credit history, mortgage history and recent credit activity.
Down Payment and Equity
Required equity or down payment depends on the loan amount, property, occupancy and individual program.
Debt-to-Income Ratio
Traditional jumbo programs commonly evaluate monthly debt obligations relative to qualifying income.
Income
Income documentation could include:
- W-2 income
- Pay stubs
- Tax returns
- Business income
- Partnership or corporate income
- Retirement income
- Investment income
- Other eligible income sources
Assets
Borrowers may need to document funds required for the down payment, closing costs and reserves.
Cash Reserves
Some jumbo programs require borrowers to retain a specified amount of liquid or eligible assets after closing.
Property
The property itself must satisfy the lender's eligibility and appraisal requirements.
How Much Down Payment Is Required for a Jumbo Loan?
There is no single down payment requirement that applies to every St. George jumbo mortgage.
Required down payment is generally determined by the lender's maximum permitted loan-to-value ratio (LTV).
Factors affecting maximum LTV can include:
- Loan amount
- Credit score
- Property type
- Primary residence versus second home
- Investment-property status
- Purchase versus refinance
- Income documentation
- Reserve assets
- Overall borrower profile
Rather than assuming that every jumbo mortgage requires the same percentage down, borrowers should compare programs based on the specific transaction.
Jumbo Mortgage Rates in St. George
Jumbo mortgage rates do not necessarily move exactly like conforming mortgage rates.
Pricing can vary based on:
- Loan amount
- Credit score
- LTV
- Property type
- Occupancy
- Fixed versus adjustable rate
- Loan term
- Discount points
- Reserve assets
- Income documentation
- Market conditions
A lower advertised interest rate also does not automatically mean a mortgage has the lowest overall cost.
When comparing jumbo loans, consider the interest rate, APR, lender costs, discount points, loan structure and long-term financing objectives together.
Luxury Home Financing in St. George and Southern Utah
Southern Utah includes a diverse selection of higher-value properties, from established luxury communities to newer custom construction.
Jumbo financing may be appropriate for qualified borrowers purchasing:
- Luxury homes
- Custom-built residences
- Primary residences
- Second homes
- Vacation properties
- High-value new construction
- Certain eligible investment properties
Luxury-property financing can require additional analysis because unusual properties may have fewer comparable sales than standard homes.
That can make the appraisal and property-review process especially important.
Second-Home Jumbo Loans in St. George
St. George and Southern Utah attract buyers seeking second residences for recreation, seasonal living and long-term personal use.
Qualified borrowers may be able to use jumbo second-home financing for eligible Southern Utah properties.
Second-home guidelines can differ from primary-residence requirements.
A lender may consider:
- Intended occupancy
- Property characteristics
- Distance from the primary residence
- Loan amount
- LTV
- Credit
- Reserves
- Existing housing expenses
Borrowers should establish the correct occupancy classification before applying rather than assuming a property automatically qualifies as a second home.
Jumbo Loans for Self-Employed Borrowers in St. George
Business owners, entrepreneurs and independent professionals can have financial profiles that do not fit neatly into traditional W-2 underwriting.
Traditional jumbo qualification may still be available when tax returns adequately document qualifying income.
However, eligible borrowers may also have access to alternative-documentation jumbo programs.
Depending on current lender guidelines, potential approaches can include:
- Personal bank statements
- Business bank statements
- Profit-and-loss documentation
- Asset-based qualification
- Asset depletion
- Other eligible non-QM documentation methods
Alternative documentation does not mean underwriting is eliminated.
Credit, assets, reserves, property eligibility, loan amount and other requirements still apply.
Bank Statement Jumbo Loans in Southern Utah
A business owner may generate substantial cash flow while showing lower taxable income because of legitimate business deductions.
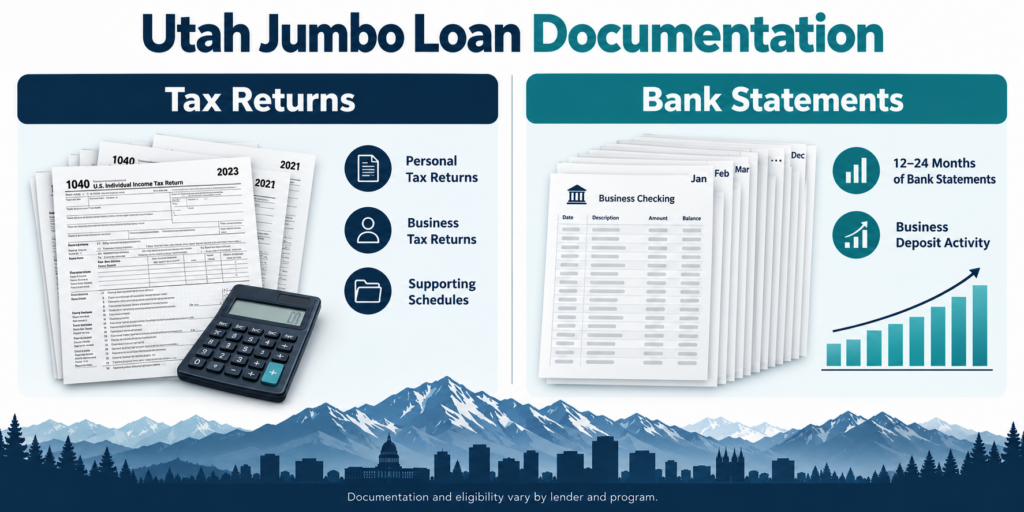
For qualifying borrowers, a bank statement jumbo mortgage may allow eligible deposits to be evaluated as part of the income-qualification process rather than relying exclusively on traditional tax-return calculations.
Programs can differ considerably in how deposits, business expenses, transfers and other transactions are treated.
Borrowers considering this option should have their statements evaluated before assuming a specific amount of qualifying income.
Super Jumbo Loans in St. George, Utah
Some luxury properties require financing well beyond ordinary jumbo loan amounts.
These mortgages are often described as super jumbo loans.
Super jumbo financing may be appropriate for qualified borrowers seeking multimillion-dollar financing for eligible luxury properties.
Depending on the program, underwriting may place increased emphasis on:
- Overall net worth
- Liquidity
- Post-closing reserves
- Credit history
- Income stability
- Property quality
- Appraisal support
- Loan-to-value ratio
Large mortgage transactions are highly program-specific, making lender selection and loan structure particularly important.
Jumbo Loans for Purchasing a St. George Home
A jumbo purchase mortgage can be used when the amount needed to finance a property exceeds the applicable conforming limit.
Before making an offer on a higher-priced home, consider establishing:
- Approximate maximum loan amount
- Available down payment
- Reserve requirements
- Income-documentation strategy
- Target monthly payment
- Appropriate loan structure
A jumbo pre-approval can also help identify documentation or property issues before a purchase contract is underway.
Jumbo Mortgage Refinancing
Qualified St. George homeowners may also use jumbo financing to refinance an existing high-balance mortgage.
Potential objectives include:
- Changing the interest rate
- Changing the loan term
- Moving between adjustable and fixed-rate financing
- Restructuring an existing mortgage
- Accessing equity through an eligible cash-out refinance
Whether refinancing makes financial sense depends on the new loan's costs, interest rate, monthly payment and the homeowner's expected time in the property.
Jumbo Cash-Out Refinance
Homeowners with substantial equity may consider a jumbo cash-out refinance when permitted by current program guidelines.
Potential uses of proceeds vary, but the lender will establish maximum LTV, loan amount and cash-out requirements.
Cash-out limits can be more restrictive than purchase or rate-and-term refinance guidelines, particularly at very large loan amounts.
Jumbo Financing Throughout St. George and Washington County
UtahLowRate.com works with borrowers financing eligible properties throughout St. George, Washington County and Southern Utah.
Areas may include:
- St. George
- Washington
- Ivins
- Santa Clara
- Hurricane
- Entrada-area communities
- Desert Color
- Little Valley
- Other communities throughout Washington County
Each property should be evaluated individually because property type, occupancy, appraisal characteristics and loan size can affect available financing.
St. George Jumbo Loan vs. Conventional Mortgage
| Feature | Conforming Mortgage | Jumbo Mortgage |
|---|---|---|
| Loan Amount | Within applicable conforming limits | Generally exceeds conforming limits |
| Guidelines | Agency/conforming standards | Lender/investor specific |
| Reserves | Program dependent | Often more significant |
| Appraisal | Standard requirements | May receive additional review |
| Income | Standard qualifying documentation | Traditional and select alternative options |
| Large Luxury Properties | May be limited by loan size | Designed for larger financing needs |
Neither option is automatically better.
The appropriate mortgage depends on the loan amount, property and borrower's financial circumstances.
How to Compare St. George Jumbo Mortgage Programs
Jumbo financing should generally be compared on more than the advertised interest rate.
Consider:
Interest Rate — The note rate used to calculate mortgage interest.
APR — A broader measurement that incorporates certain financing costs.
Points and Fees — A lower rate may require greater upfront cost.
Loan Structure — Compare fixed-rate and available adjustable-rate options.
LTV — Determine how much equity or down payment is required.
Reserves — Large loans may require significant assets after closing.
Income Documentation — Especially important for business owners and borrowers with complex income.
Prepayment Terms — Particularly relevant for certain non-owner-occupied or non-QM programs.
Long-Term Plans — Consider how long you expect to own the home or retain the mortgage.
Why Work with a Mortgage Broker for a Jumbo Loan?
Jumbo mortgage guidelines can differ significantly between lenders.
A borrower who does not fit one lender's guidelines may potentially fit another lender's program.
Working with a mortgage broker can provide access to multiple wholesale lending sources and make it possible to compare available programs based on the borrowers:
- Loan amount
- Credit profile
- Down payment
- Income structure
- Assets
- Occupancy
- Property
- Financing objectives
The objective should be to identify an appropriate mortgage structure—not simply to find a lender willing to make the loan.
Frequently Asked Questions About Jumbo Loans in St. George, Utah
What is considered a jumbo loan in St. George, Utah?
A mortgage is generally considered jumbo when its loan amount exceeds the applicable conforming loan limit for the property. Current conforming limits should be verified because they can change.
Can I get a jumbo loan for a second home in St. George?
Potentially. Qualified borrowers may have jumbo financing options for eligible second homes in St. George and Southern Utah. Down payment, reserves, credit and occupancy requirements vary by lender.
Are jumbo loans available for self-employed borrowers?
Yes, qualified self-employed borrowers may obtain jumbo financing. Depending on the program, income may be documented traditionally or through eligible alternative-documentation methods such as bank statements or profit-and-loss information.
Can bank statements be used for a St. George jumbo loan?
Certain non-QM jumbo programs may allow eligible self-employed borrowers to qualify using personal or business bank statements. Income-calculation rules vary between lenders.
Can I use a jumbo loan for a luxury home?
Yes. Jumbo mortgages are frequently used to finance luxury and higher-priced homes when the required mortgage exceeds conforming loan limits.
Can jumbo financing be used for an investment property?
Certain jumbo and non-QM programs permit eligible investment properties. Requirements may differ substantially from owner-occupied financing.
Are super jumbo mortgages available in St. George?
Qualified borrowers seeking very large mortgage amounts may have access to specialized super jumbo programs. Loan size, LTV, liquidity, reserves, income and property requirements depend on the lender.
Do jumbo loans require 20% down?
Not necessarily. Jumbo down-payment requirements vary according to the lender, loan amount, credit profile, property type, occupancy and other underwriting factors.
Do jumbo mortgages require large cash reserves?
Many jumbo lenders require post-closing reserves, particularly for larger loan amounts. The amount required varies by program and borrower profile.
Can I refinance a jumbo mortgage in St. George?
Yes. Eligible borrowers may have rate-and-term and cash-out jumbo refinance options. Maximum LTV, loan amount and cash-out limits depend on program guidelines.
Get a Jumbo Loan Quote in St. George, Utah
Financing a higher-value Southern Utah home does not have to mean relying on a single jumbo mortgage program.
Daniel Paris of UtahLowRate.com can help qualified borrowers compare available jumbo and super jumbo financing for properties in St. George, Washington, Ivins, Santa Clara, Hurricane and communities throughout Washington County and Southern Utah.
Whether you are purchasing a luxury primary residence, financing a second home, refinancing an existing jumbo mortgage or need a specialized solution for self-employed income, the first step is reviewing the complete financing scenario.
Talk With Daniel Paris
Daniel Paris
UtahLowRate.com
NMLS #243976
Phone: 801-604-4949
Request a personalized St. George jumbo mortgage comparison based on your loan amount, property, down payment, credit, income and financing goals.
Loan programs, rates, terms, LTV limits and underwriting requirements are subject to change. All loans are subject to borrower and property qualification.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

