
Content updated: September 29, 2026
$10 Million Mortgage Loans Utah are specialized super jumbo mortgage programs designed for qualified borrowers financing luxury homes, estates, second homes and other high-value residential properties. UtahLowRate.com helps borrowers compare super jumbo financing for $10 million mortgage amounts throughout Utah, including Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Heber City and other luxury real estate markets.
A mortgage of this size is not simply a larger version of a conventional home loan. Underwriting can focus heavily on liquidity, post-closing reserves, credit, income, assets, property value, occupancy and the overall strength of the borrower.
Check My Jumbo Options or call 801-604-4949.
Daniel Paris | Utah Mortgage Broker
UtahLowRate.com | 801-604-4949
NMLS #243976
Compare Utah Super Jumbo Mortgage Loans
Quick Answer: Can You Get a $10 Million Mortgage in Utah?
Yes. Qualified borrowers may be able to obtain a $10 million mortgage loan in Utah through specialized super jumbo lending programs.
Approval is not based on the loan amount alone. Lenders may evaluate credit, income, liquidity, net worth, reserves, down payment or equity, property type, occupancy and the overall financial profile.
For borrowers with complex income or substantial assets, alternative qualification methods may also be available depending on current lender guidelines.
$10 Million Mortgage Loans Utah — Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Mortgage Feature | Potential Options |
|---|---|
| Loan amount | $10 million |
| Loan category | Super jumbo / high-balance jumbo |
| Purchase | May be available |
| Rate-and-term refinance | May be available |
| Cash-out refinance | Select programs |
| Primary residence | May be eligible |
| Second home | May be eligible |
| Investment property | Select programs |
| Fixed-rate options | Program dependent |
| ARM options | May be available |
| Interest-only | Select programs |
| Asset-based qualification | Select programs |
| Bank statement qualification | Select programs |
| Pledged assets | Select programs |
| Maximum LTV | Program and borrower dependent |
| Reserves | Generally significant at this loan size |
| Property appraisal | Required under applicable guidelines |
Program availability and underwriting guidelines can change. A program's maximum loan amount does not mean every borrower or property will qualify.
What Is a $10 Million Mortgage?
A $10 million mortgage is generally considered a super jumbo mortgage because the loan amount is far beyond standard conforming mortgage limits and most traditional jumbo programs.
Super jumbo lending is a specialized part of the mortgage market.
Rather than evaluating the borrower using only standard agency underwriting rules, a super jumbo lender may examine the borrower's entire financial profile.
That can include:
- Employment and business income
- Investment income
- Liquid assets
- Retirement assets
- Brokerage accounts
- Business ownership
- Real estate holdings
- Existing mortgages
- Credit history
- Post-closing liquidity
- Net worth
- Property characteristics
- Occupancy
- Loan-to-value ratio
For a $10 million mortgage, choosing the right lender and structuring the transaction correctly can be particularly important.
Learn more about Jumbo Mortgage Loans in Utah and Super Jumbo Mortgage Loans.
Who May Need a $10 Million Mortgage Loan in Utah?
A $10 million mortgage can be appropriate for qualified borrowers purchasing or refinancing exceptionally high-value residential real estate.
Potential borrowers can include:
- Business owners
- Entrepreneurs
- Corporate executives
- Physicians
- Attorneys
- Professional investors
- Real estate developers
- High-net-worth families
- Borrowers with substantial investment portfolios
- Borrowers with concentrated stock positions
- Self-employed professionals
- Buyers relocating to Utah
- Second-home buyers
- Luxury-property investors where eligible
The borrower's profession does not determine eligibility. The lender evaluates the complete transaction.
Where Are $10 Million Mortgages Used in Utah?
High-balance and super jumbo financing can be particularly relevant in Utah's luxury real estate markets.
Park City and Deer Valley
Park City and Deer Valley contain some of Utah's highest-value residential properties.
Super jumbo financing may be used for eligible properties in areas such as:
- Deer Valley
- Empire Pass
- Old Town
- Canyons Village
- Promontory
- Glenwild
- The Colony
- Park Meadows
- Thaynes Canyon
- Prospector
- Jeremy Ranch
- Summit Park
A luxury property can involve additional appraisal and underwriting considerations because comparable sales may be limited.
Salt Lake City and Salt Lake County
Luxury financing may also be needed for high-value properties throughout:
- Salt Lake City
- Holladay
- Federal Heights
- Cottonwood Heights
- Millcreek
- Sandy
- Draper
Large custom homes, estates and properties with unique features may require specialized jumbo underwriting.
Alpine, Highland and Utah County
Northern Utah County includes luxury properties in communities such as:
- Alpine
- Highland
- Lehi
- American Fork
- Pleasant Grove
A borrower purchasing a large custom home or estate may need jumbo or super jumbo financing depending on the requested loan amount.
Heber City, Midway and the Wasatch Back
High-value residential development has also created super jumbo financing opportunities throughout:
- Heber City
- Midway
- Jordanelle
- Hideout
- Kamas
- surrounding Wasatch Back communities
St. George and Southern Utah
Luxury homes and second-home properties can also require jumbo financing in:
- St. George
- Ivins
- Santa Clara
- Washington
- Hurricane
- surrounding Southern Utah communities
How Much Down Payment Is Required on a $10 Million Mortgage?
There is no universal down-payment requirement for a $10 million mortgage.
Maximum loan-to-value ratios can change based on the lender, property, occupancy, credit profile, liquidity and requested loan amount.
For illustration:
| Maximum LTV | Equity / Down Payment | Approx. Property Value for $10M Loan |
|---|---|---|
| 70% | 30% | $14.29 million |
| 65% | 35% | $15.38 million |
| 60% | 40% | $16.67 million |
| 55% | 45% | $18.18 million |
| 50% | 50% | $20 million |
These figures are mathematical examples, not advertised lending terms or promises of available financing.
At very large loan amounts, maximum LTV frequently becomes an important part of lender selection.
Example: $10 Million Mortgage at 55% LTV
Suppose a borrower purchases an approximately $18.18 million Utah property and requests a $10 million mortgage.
The approximate calculation would be:
$10,000,000 ÷ $18,181,818 = 55% LTV
That leaves approximately $8.18 million of equity in the transaction before considering closing costs and other expenses.
Whether 55% LTV is available depends on the current lender program and complete borrower and property profile.
Credit Requirements for a $10 Million Mortgage
There is no single credit-score requirement that applies to every $10 million mortgage.
Lenders may consider:
- Credit score
- Mortgage payment history
- Credit depth
- Revolving debt
- Installment debt
- Recent credit inquiries
- Derogatory credit events
- Existing real estate obligations
- Overall leverage
Strong credit can improve the number of available options, but credit is only one part of super jumbo underwriting.
A borrower with excellent credit but insufficient liquidity may face a different underwriting challenge than a borrower with substantial liquid assets and a more complicated credit profile.
How Much Income Do You Need for a $10 Million Mortgage?
There is no universal income figure required for a $10 million mortgage.
The required income depends on factors such as:
- Interest rate
- Loan term
- Existing debt
- Property taxes
- Homeowners insurance
- HOA obligations
- Other financed properties
- Income documentation
- Assets
- Lender underwriting method
Traditional income documentation may work well for some borrowers.
Other high-net-worth borrowers may have substantial financial resources without receiving most of their income through a conventional W-2 salary.
That is where alternative qualification strategies can become important.
$10 Million Mortgage Loans for Self-Employed Borrowers
Self-employed borrowers can present unique underwriting challenges.
A successful business owner may generate substantial cash flow while reporting lower taxable income because of legitimate business deductions.
Depending on the available program, qualification options can potentially include:
- Traditional tax-return underwriting
- Bank statement income
- Profit-and-loss documentation
- Asset depletion
- Asset utilization
- Other alternative-documentation programs
Self-employed borrowers should have their income structure reviewed before assuming traditional tax-return underwriting is their only option.
See Jumbo Bank Statement Loans Utah for additional information.
Asset-Based $10 Million Mortgage Options
Some high-net-worth borrowers have significant assets but comparatively modest traditional earned income.
Depending on current lending guidelines, an asset-based or asset-depletion mortgage may allow eligible assets to contribute to the qualification calculation.
Potential assets can include eligible:
- Cash
- Savings
- Brokerage accounts
- Stocks
- Bonds
- Retirement accounts
- Other approved financial assets
The lender determines which assets are eligible, what percentage can be used and how those assets are converted into qualifying income.
Pledged-Asset Mortgage Strategies
Certain high-net-worth borrowers may prefer not to liquidate a large investment portfolio to make a larger down payment.
Selling securities can potentially create tax consequences, remove assets from the market or interfere with a broader investment strategy.
Depending on the available program, a pledged-asset relationship may provide another financing structure.
Pledged-asset strategies are specialized and involve investment and lending risks. Borrowers should review the structure with their mortgage, financial, legal and tax professionals before proceeding.
Fixed-Rate vs. ARM $10 Million Mortgage Loans
Super jumbo borrowers may have access to different rate structures depending on the lender.
Fixed-Rate Mortgage
A fixed-rate mortgage keeps the contractual interest rate unchanged during the fixed loan term.
This may appeal to borrowers who prioritize long-term payment predictability.
Adjustable-Rate Mortgage
An ARM may provide a fixed introductory period before becoming adjustable under the loan terms.
Potential structures can include:
- 5-year ARM
- 7-year ARM
- 10-year ARM
ARM availability and terms depend on the lender.
For a borrower who expects to sell, refinance or significantly reduce the mortgage balance within several years, comparing an ARM with fixed-rate financing can be worthwhile.
Interest-Only $10 Million Mortgage Options
Select super jumbo programs may provide interest-only payment structures for qualified borrowers.
An interest-only structure can reduce the required monthly payment during the interest-only period because scheduled principal amortization is deferred.
However, the principal balance does not decline through scheduled principal payments during that period.
Borrowers should understand:
- Length of the interest-only period
- Subsequent amortization
- Future payment changes
- ARM adjustment provisions when applicable
- Prepayment terms
- Total interest expense
Interest-only financing should be evaluated as part of a complete financial strategy rather than solely on the initial payment.
$10 Million Mortgage Purchase Loans
A $10 million purchase mortgage may be used by a qualified borrower purchasing a multimillion-dollar Utah residence.
Before making an offer, the borrower should ideally have the proposed financing structure reviewed.
A strong super jumbo pre-approval may require more than a basic online mortgage application.
The lender may want to review:
- Income documentation
- Asset statements
- Business ownership
- Credit
- Existing real estate
- Liquidity
- Proposed down payment
- Requested loan amount
- Property type
Identifying underwriting issues before the purchase contract can make the transaction more predictable.
$10 Million Mortgage Refinance Loans
Super jumbo financing may also be available for qualified homeowners refinancing an existing high-balance mortgage.
Potential objectives include:
- Changing the interest-rate structure
- Moving from an ARM to fixed financing
- Moving from fixed financing to an ARM
- Changing the loan term
- Consolidating eligible mortgage debt
- Restructuring a large mortgage
- Accessing equity when eligible
Visit the Utah Jumbo Mortgage resource to compare additional jumbo financing options.
$10 Million Cash-Out Refinance
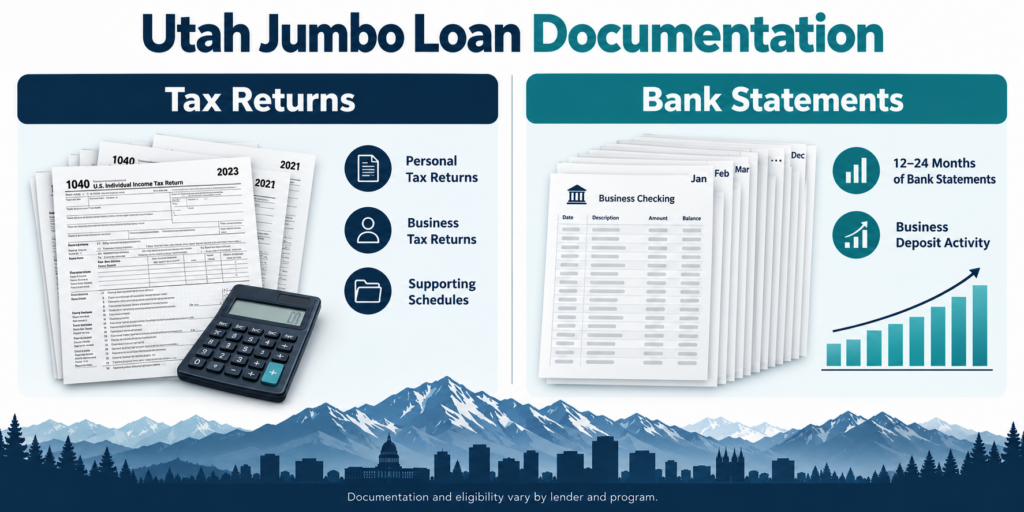
Certain super jumbo programs may permit cash-out refinancing for qualified borrowers.
Potential reasons for accessing equity can include:
- Investment opportunities
- Business liquidity
- Real estate acquisitions
- Portfolio restructuring
- Major capital expenditures
- Other financial objectives
Cash-out LTV limits can be lower than purchase or rate-and-term refinance limits.
The lender may also impose limits on the amount of cash that can be received at closing.
Reserve Requirements for $10 Million Mortgage Loans Utah
Liquidity is often a major component of super jumbo underwriting.
A lender may require the borrower to retain substantial eligible assets after closing.
These are commonly called post-closing reserves.
Reserve requirements can depend on:
- Loan amount
- Monthly housing expense
- Number of financed properties
- Occupancy
- Credit
- LTV
- Property type
- Borrower's financial profile
- Lender guidelines
For a $10 million mortgage, reserve requirements can represent a substantial dollar amount.
This is one reason borrowers should avoid moving or liquidating significant assets without first discussing the transaction with their mortgage professional.
Property Appraisals on a $10 Million Utah Home
Valuing an exceptionally high-end property can be more complicated than appraising a typical home.
A luxury property may contain unique characteristics such as:
- Large acreage
- Ski access
- Mountain or valley views
- Custom architecture
- Guest residences
- Extensive recreational facilities
- High-end construction
- Unique land characteristics
- Luxury amenities
- Limited comparable sales
Depending on the lender and transaction, additional appraisal review or multiple valuations may be required.
Documents You May Need
Documentation varies substantially by program.
A $10 million mortgage application may involve:
Income Documentation
Potential documents include W-2s, pay statements, tax returns, K-1s, business returns or alternative income documentation.
Asset Documentation
Lenders may request statements for:
- Bank accounts
- Brokerage accounts
- Retirement accounts
- Investment accounts
- Other eligible liquid assets
Business Documentation
Business owners may need ownership documentation and financial information.
Real Estate Schedule
Borrowers with multiple properties may need to document mortgages, taxes, insurance, rents and property values.
Property Documentation
The purchase contract, appraisal, title documentation and insurance information may also be required.
The exact documentation should be determined after the specific lending program has been identified.
$10 Million Mortgage vs. Standard Jumbo Mortgage
| Feature | Standard Jumbo | $10 Million Super Jumbo |
|---|---|---|
| Loan size | Above conforming limits | Exceptionally high |
| Lender availability | Broader | More specialized |
| Liquidity review | Important | Often critical |
| Reserve requirements | Common | Can be substantial |
| Appraisal complexity | Moderate to high | Can be extensive |
| Alternative documentation | Select programs | Specialized programs |
| Asset-based options | Available with some lenders | Can be important |
| Pledged assets | Less common | Select private-bank/specialty programs |
| Loan structuring | Important | Particularly important |
A borrower seeking $10 million should generally compare lenders based on the entire financing structure rather than interest rate alone.
Why Use a Mortgage Broker for a $10 Million Mortgage?
The super jumbo mortgage market is not standardized.
Different lending sources can have dramatically different requirements for:
- Maximum loan amount
- LTV
- Credit
- Reserves
- Income
- Asset depletion
- Self-employment
- Bank statement qualification
- Second homes
- Investment properties
- Cash-out
- Interest-only financing
- Property types
A borrower who does not meet one lender's guidelines may potentially fit another lender's program.
UtahLowRate.com works with multiple lending sources to evaluate jumbo and super jumbo financing rather than restricting the borrower to one institution's product menu.
$10 Million Mortgage Loans and Utah Investment Properties
A $10 million mortgage on an investment property requires a different analysis from a $10 million primary-residence mortgage.
Depending on the property and transaction, investors may need to compare:
- Jumbo investment-property financing
- Portfolio financing
- Non-QM financing
- Bank statement financing
- Asset-based financing
- DSCR financing
A DSCR loan generally evaluates the property's qualifying rental income relative to its applicable housing debt rather than relying primarily on the borrower's personal employment income.
Start with the Utah DSCR Mortgage Loans hub when the property is being acquired or refinanced as a rental investment.
Utah DSCR Loan Resource Center
Investors should also review the UtahLowRate.com DSCR cluster for detailed information about:
- DSCR loan requirements in Utah
- Current DSCR loan pricing factors
- Calculating a property's DSCR
- DSCR loan frequently asked questions
- Salt Lake City DSCR financing
- Park City DSCR loans
- St. George DSCR loans
- DSCR purchase financing
- DSCR refinance and cash-out strategies
Important: A $10 million super jumbo residential mortgage and a DSCR investment-property loan are not interchangeable products. The correct financing path depends on the property's occupancy, rental structure, borrower profile and current lender guidelines.
How to Prepare for a $10 Million Mortgage
1. Define the Transaction
Determine whether you are purchasing, refinancing or seeking cash out.
2. Establish the Loan Amount and LTV
Know the expected property value, requested loan amount and available equity or down payment.
3. Review Income
Determine whether traditional documentation or an alternative method is most appropriate.
4. Review Liquidity
Calculate the assets available for the down payment, closing costs and post-closing reserves.
5. Review Credit
Address potential credit issues before formal underwriting when possible.
6. Compare Super Jumbo Programs
Do not assume that one bank's guidelines represent the entire super jumbo market.
7. Obtain a Detailed Pre-Approval
For a purchase, complete as much financial review as practical before making an offer on a multimillion-dollar property.
Common Mistakes With $10 Million Mortgage Loans
Shopping Only for the Lowest Advertised Rate
The lowest quoted rate is irrelevant if the lender cannot approve the transaction.
Compare the complete structure.
Moving Large Amounts of Money Before Closing
Large transfers can complicate asset documentation.
Discuss significant asset movements before making them.
Assuming Every Jumbo Lender Goes to $10 Million
Many lenders cap their jumbo programs well below $10 million.
Ignoring Reserve Requirements
Having enough for the down payment does not necessarily mean you have sufficient post-closing liquidity.
Waiting Until After Making an Offer
Complex jumbo underwriting should ideally begin early.
Assuming Taxable Income Tells the Whole Story
Business owners and asset-rich borrowers may have alternative qualification options.
Related Utah Jumbo Mortgage Resources
Explore these UtahLowRate.com resources when comparing a $10 million mortgage:
- Jumbo Mortgage Utah
- Super Jumbo Mortgage Loans Utah & California
- Jumbo Bank Statement Loans Utah
- Conventional Mortgage Loans Utah
- Utah Mortgage Loans
- Utah Mortgage Broker — Daniel Paris
- Utah DSCR Mortgage Loans
Frequently Asked Questions About $10 Million Mortgage Loans Utah
Can I get a $10 million mortgage in Utah?
Yes. Qualified borrowers may have access to specialized super jumbo mortgage programs capable of financing a $10 million mortgage. Approval depends on the borrower, property, LTV, credit, income, assets, reserves and current lender guidelines.
How much down payment do I need for a $10 million mortgage?
There is no universal percentage. Maximum LTV depends on the lender and transaction. As a mathematical example, a $10 million mortgage at 55% LTV would require a property value of approximately $18.18 million.
Do I need tax returns for a $10 million mortgage?
Not necessarily under every program. Traditional jumbo loans may use tax returns, while select alternative-documentation programs may evaluate bank statements, assets or other qualifying documentation. Requirements depend on the lender.
Can a self-employed borrower get a $10 million mortgage?
Potentially. Qualified business owners may use traditional documentation or, where available, alternative methods such as bank statements, asset depletion or other specialized jumbo programs.
Are interest-only $10 million mortgages available?
Select super jumbo lenders may offer interest-only options to qualified borrowers. Terms, qualification requirements and availability vary.
Can I get a $10 million mortgage for a Park City or Deer Valley home?
Potentially. Park City and Deer Valley are Utah markets where jumbo and super jumbo financing may be relevant because of high-value luxury properties.
Can a $10 million mortgage be used for a second home?
Select super jumbo programs may permit qualified second-home transactions. LTV, reserves and underwriting requirements can differ from those for a primary residence.
Can I cash out of a multimillion-dollar Utah property?
Select lenders may offer super jumbo cash-out refinancing. Maximum LTV and maximum cash-out amounts depend on the specific program.
What is the largest mortgage available through UtahLowRate.com?
UtahLowRate.com works with specialized super jumbo lending sources offering financing that may extend to approximately $30 million or more for qualified borrowers and eligible properties, subject to current program guidelines.
Is a $10 million mortgage considered jumbo or super jumbo?
A $10 million residential mortgage would generally be described as a super jumbo mortgage because it substantially exceeds conventional conforming and typical jumbo loan sizes.
Compare $10 Million Mortgage Loans in Utah
Financing a $10 million mortgage requires more than finding a lender advertising jumbo loans.
The structure should be evaluated around your:
- Loan amount
- Property value
- Down payment
- Credit
- Income
- Business ownership
- Assets
- Liquidity
- Reserves
- Occupancy
- Long-term financial objectives
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified borrowers seeking specialized jumbo and super jumbo financing throughout Utah.
Whether you are financing a luxury residence in Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Heber City, Midway, St. George or another Utah community, UtahLowRate.com can help compare available financing structures.
Check Your $10 Million Mortgage Options
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
NMLS #243976
Ask about $10 Million Mortgage Loans Utah, Super Jumbo financing, luxury-home purchases, refinances, cash-out options, asset-based mortgages and self-employed jumbo financing.
Mortgage Disclaimer: Mortgage programs, interest rates, APRs, loan amounts, LTV limits, documentation requirements, reserve requirements and eligibility can change without notice. All loans are subject to borrower qualification, property eligibility, appraisal requirements, lender/investor guidelines and underwriting approval. Examples on this page are for educational purposes and are not commitments to lend, advertised terms or guarantees of approval.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

