
Get Pre-Approved for a Home Loan
Quick Answer: What Is a Utah Mortgage Pre-Approval?
A Utah mortgage pre-approval reviews your credit, income, employment, assets, debts, down payment and proposed home purchase to estimate the mortgage programs and loan amount you may qualify for. Getting pre-approved before seriously shopping for a home can help establish your price range and prepare you to make an offer.
Daniel Paris at UtahLowRate.com helps qualified homebuyers throughout Utah compare conventional, FHA, VA, jumbo, super jumbo and alternative-documentation mortgage options.
Ready to Start?
Get My Utah Mortgage Pre-Approval
Check My Home-Buying Budget
Compare My Mortgage Options
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
NMLS #243976
Utah Mortgage Pre-Approval: Quick Facts
| Question Quick Answer | |
|---|---|
| What is mortgage pre-approval? | A preliminary evaluation of your financial qualifications and proposed home purchase. |
| When should I get pre-approved? | Ideally before seriously shopping for Utah homes or submitting purchase offers. |
| Can I get pre-approved before finding a house? | Yes. A specific property is generally not required to begin the pre-approval process. |
| Does pre-approval guarantee a mortgage? | No. Final approval remains subject to underwriting, documentation, property eligibility and applicable loan conditions. |
| Can first-time buyers get pre-approved? | Yes. First-time homebuyers may have several financing options depending on their qualifications. |
| Can self-employed buyers get pre-approved? | Potentially. Traditional and alternative-documentation programs may be available. |
| Can I get pre-approved for a jumbo loan? | Potentially. Jumbo and super jumbo programs have their own underwriting requirements. |
| Does pre-approval involve credit? | A mortgage pre-approval commonly includes a credit review. |
| Who provides Utah mortgage pre-approval? | Contact Utah mortgage broker Daniel Paris at 801-604-4949. |
What Is Mortgage Pre-Approval?
Mortgage pre-approval is a preliminary review of your financial qualifications before you purchase a home.
Depending on the mortgage program, the review may consider:
- Income and employment
- Self-employment income
- Credit history
- Monthly debts
- Assets
- Down-payment funds
- Cash reserves
- Desired purchase price
- Estimated housing payment
- Property type
- Occupancy
- Mortgage program
- Requested loan amount
If your financial profile meets applicable preliminary requirements, you may be eligible to receive a mortgage pre-approval letter for use while shopping for a Utah home.
A pre-approval is not final mortgage approval or a commitment to lend. Final approval remains subject to underwriting, acceptable documentation, property eligibility, appraisal when required, title, insurance and satisfaction of applicable lender and investor conditions.
Why Get Pre-Approved Before Shopping for a Utah Home?
Getting your financing reviewed before becoming committed to a property can answer several important questions.
Understand Your Home-Buying Budget
Pre-approval can help estimate a potential purchase and financing range based on factors such as your qualifying income, debts, down payment, credit and proposed housing expenses.
Your total housing expense can include more than principal and interest.
Depending on the property and mortgage, also consider:
- Property taxes
- Homeowners insurance
- Mortgage insurance when applicable
- HOA dues
- Special assessments when applicable
Your maximum qualifying loan amount also does not have to become your personal spending limit.
Compare Mortgage Programs Before Making an Offer
Not every homebuyer should automatically use the same mortgage.
Depending on your qualifications, you may want to compare conventional mortgage loans, FHA loans, VA financing, jumbo mortgages, super jumbo mortgages and alternative-documentation mortgage programs.
Self-employed borrowers may also have options involving bank statement loans, 1099 mortgage programs, Profit & Loss mortgage loans or other eligible alternative-documentation methods.
Identify Potential Problems Early
A mortgage review may uncover issues involving credit, debt-to-income ratio, employment, income documentation, down payment, reserves or asset sourcing.
Discovering an issue before you have a property under contract can give you more time to evaluate your options.
Prepare to Make an Offer
When you find the right Utah property, you may need to move quickly.
Having your financing reviewed in advance can help you understand the mortgage amount you are considering and prepare you to provide a pre-approval letter with an offer when appropriate.
Mortgage Pre-Approval vs. Prequalification
The terms prequalification and pre-approval are sometimes used interchangeably, but the depth of the financial review may differ.
Mortgage Prequalification
A prequalification may be an early estimate based primarily on financial information provided by the borrower.
It can be useful when you are exploring whether homeownership may fit your budget but are not yet ready to make an offer.
Mortgage pre-approval
A pre-approval generally involves a more detailed evaluation and may include review of credit, income, employment, assets, debts and down-payment funds.
For buyers preparing to submit purchase offers, a more thoroughly reviewed pre-approval can provide a clearer picture of the proposed financing than a preliminary estimate alone.
How to Get Pre-Approved for a Mortgage in Utah
The process can generally be organized into seven steps.
Step 1: Discuss Your Home-Purchase Goals
Start with the basics:
- Where do you plan to buy?
- What price range are you considering?
- How much do you plan to put down?
- Will the property be your primary residence, second home or investment property?
- How do you earn your income?
- Are you eligible for VA financing?
- Are you considering a higher-priced or luxury property?
These details help identify mortgage programs worth evaluating.
Step 2: Complete a Mortgage Application
Your application provides information about your income, employment, assets, debts and proposed purchase.
Accurate information is important because your mortgage qualification is based on your actual financial circumstances.
Step 3: Review Credit
Credit can influence mortgage eligibility, loan pricing, down-payment requirements and available programs.
There is no single credit score requirement that applies to every mortgage program.
Step 4: Document Income and Employment
W-2 employees may provide pay stubs, W-2 forms and other income or employment documentation as required.
Self-employed borrowers may require tax returns or, for eligible alternative-documentation programs, different documentation.
Step 5: Review Assets and Down Payment
Your financial review may include funds needed for:
- Down payment
- Closing costs
- Required reserves
- Other applicable transaction expenses
Documentation and sourcing requirements vary by program.
Step 6: Compare Available Mortgage Programs
Once your financial profile is understood, available programs can be evaluated based on your qualifications, property plans and home-buying goals.
Step 7: Receive Your Pre-Approval Letter
If you satisfy applicable preliminary requirements, you may be eligible to receive a mortgage pre-approval letter to use during your home search.
Documents Needed for Mortgage Pre-Approval in Utah
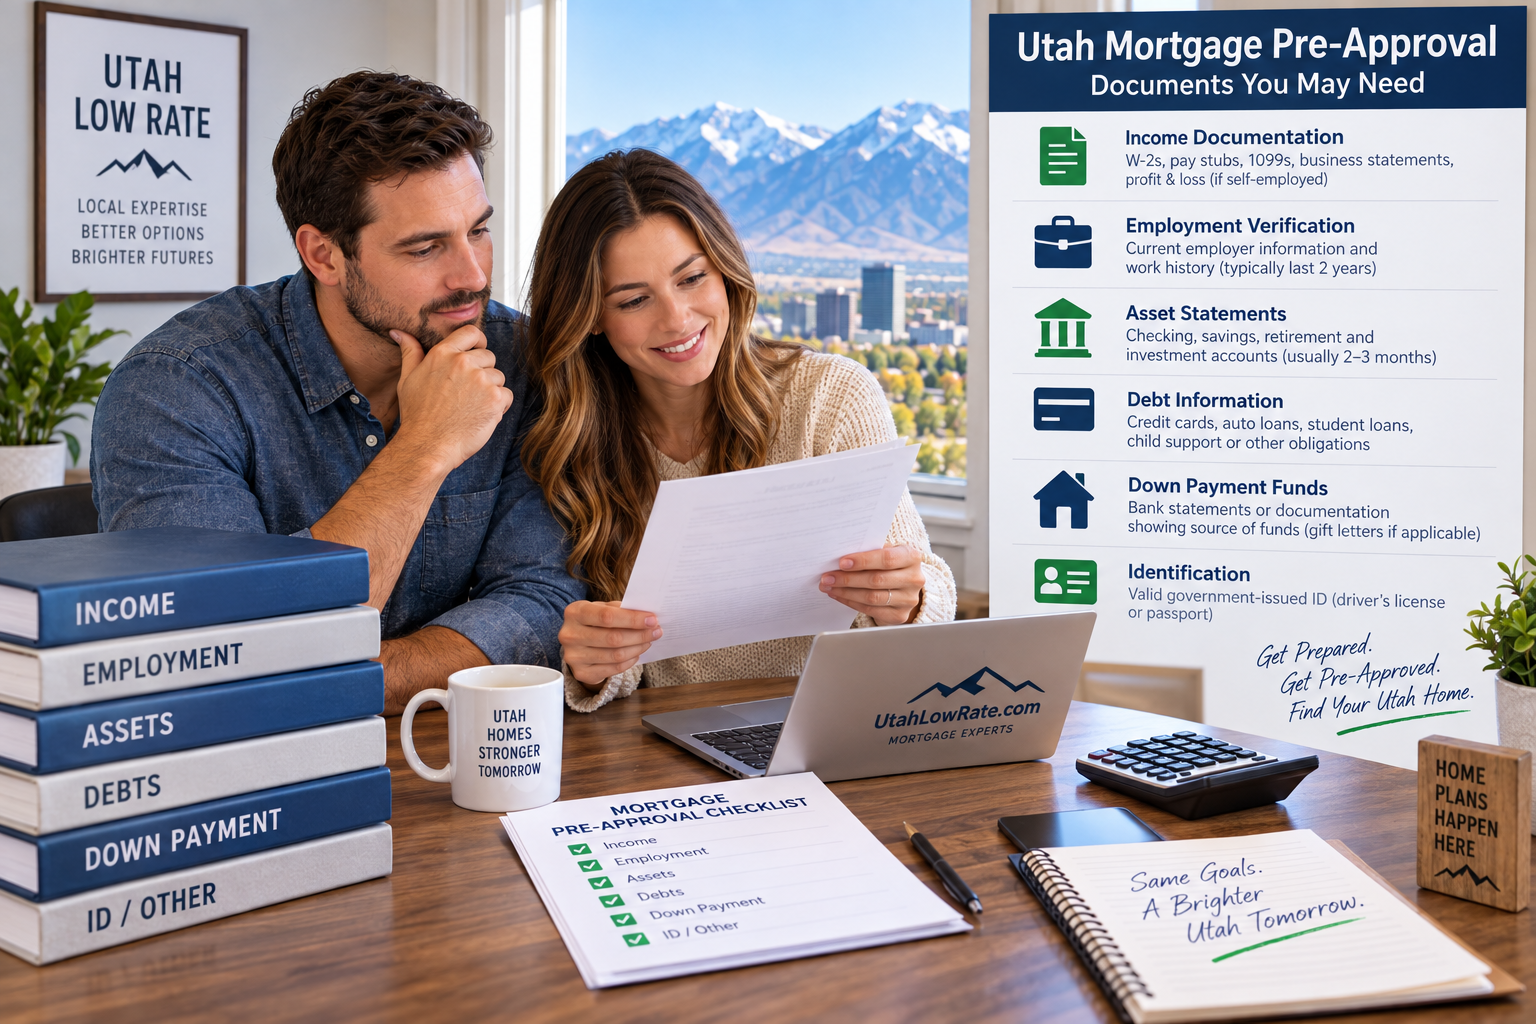
The documents required depend heavily on how you earn your income and which mortgage program you use.
| Borrower Type Documents Commonly Reviewed | |
|---|---|
| W-2 employee | Pay stubs, W-2s, bank or asset statements and employment information |
| Self-employed borrower | Tax returns and/or eligible alternative income documentation |
| Bank statement borrower | Eligible personal or business bank statements |
| 1099 borrower | 1099 income and other program-required documentation |
| P&L borrower | Eligible Profit & Loss documentation and supporting information |
| Jumbo borrower | Income, assets, reserves and additional documentation required by the program |
| VA borrower | Financial documentation plus applicable VA eligibility information |
Additional documentation may be required depending on your financial profile, property, loan program and lender.
CTA: See What Documents I Need for Pre-Approval
Utah Mortgage Programs Available for Pre-Approval
Conventional Mortgage Pre-Approval
Conventional mortgages are widely used by first-time and repeat homebuyers.
Qualification can depend on credit, qualifying income, debt-to-income ratio, down payment, assets, occupancy, property type and applicable underwriting requirements.
Related: Conventional Mortgage Loans Utah
FHA Mortgage Pre-Approval
FHA financing may be an option for borrowers whose credit, down payment and overall financial profile fit applicable FHA and lender requirements.
FHA financing can be available to eligible first-time and repeat homebuyers.
Related: FHA Loans Utah
VA Mortgage Pre-Approval
Eligible Veterans, active-duty service members and certain other qualified borrowers may have access to VA-backed purchase financing.
VA purchase loans can offer eligible borrowers no-down-payment financing and do not require monthly private mortgage insurance. VA eligibility, lender underwriting, occupancy and property requirements still apply.
Related: VA Loans Utah
Jumbo Mortgage Pre-Approval
Higher-priced Utah homes may require financing above applicable conforming loan limits.
Jumbo underwriting can place additional emphasis on:
- Credit
- Income
- Assets
- Cash reserves
- Loan-to-value ratio
- Property
- Occupancy
- Requested loan amount
A detailed jumbo pre-approval can be particularly important when purchasing higher-value properties in markets such as Park City, Deer Valley, Holladay, Cottonwood Heights, Draper, Alpine and other luxury-home areas.
Related: Jumbo Mortgage Loans Utah
Super Jumbo Mortgage Pre-Approval
Very high-value properties can require specialized financing beyond traditional jumbo programs.
UtahLowRate.com works with qualified borrowers seeking super jumbo financing, including high-net-worth borrowers with more complex income, asset and property profiles.
Related: Super Jumbo Mortgage Loans Utah & California
Non-QM Mortgage Pre-Approval
Alternative mortgage programs may be available for eligible business owners, independent contractors, real estate investors and borrowers with complex income profiles.
Depending on the program, options may include:
- Bank statement mortgages
- 1099 mortgage programs
- Profit & Loss mortgages
- Asset-depletion programs
- Other Non-QM financing
CTA: Compare My Mortgage Programs
Self-Employed Mortgage Pre-Approval in Utah
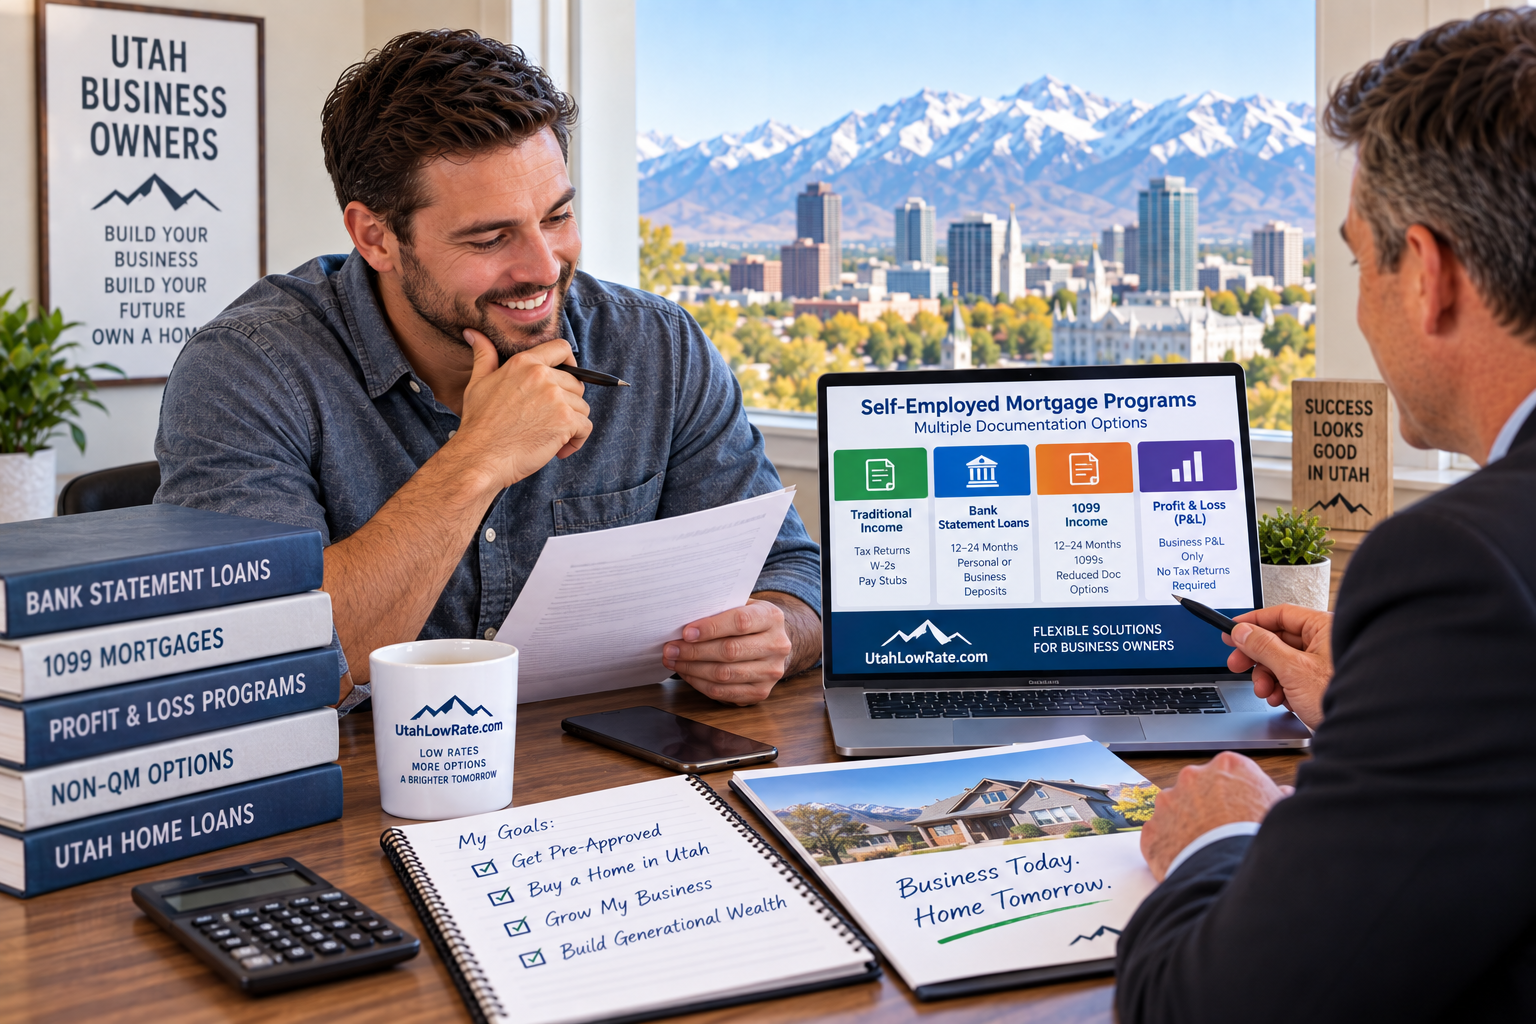
Being self-employed does not automatically prevent you from obtaining mortgage financing.
The key question is how your eligible qualifying income can be documented under the mortgage program being considered.
Traditional underwriting may calculate self-employed income using tax returns. Because business owners may have legitimate business deductions, taxable income and business cash flow can look very different.
Eligible borrowers may have alternative-documentation options.
Bank Statement Mortgage Pre-Approval
A qualifying bank statement program may use eligible personal or business bank deposits to evaluate income rather than relying exclusively on traditional tax-return calculations.
Related: Bank Statement Loans Utah
1099 Mortgage Pre-Approval
Independent contractors and other eligible borrowers receiving 1099 income may have mortgage programs that use qualifying 1099 earnings under applicable guidelines.
Related: 1099 Mortgage Loans Utah
Profit & Loss Mortgage Pre-Approval
Certain alternative-documentation programs may permit eligible self-employed borrowers to document qualifying income using a Profit & Loss statement under applicable lender requirements.
Related: Profit and Loss Mortgage Loans Utah
CTA: Estimate My Self-Employed Mortgage Options
First-Time Homebuyer Pre-Approval in Utah
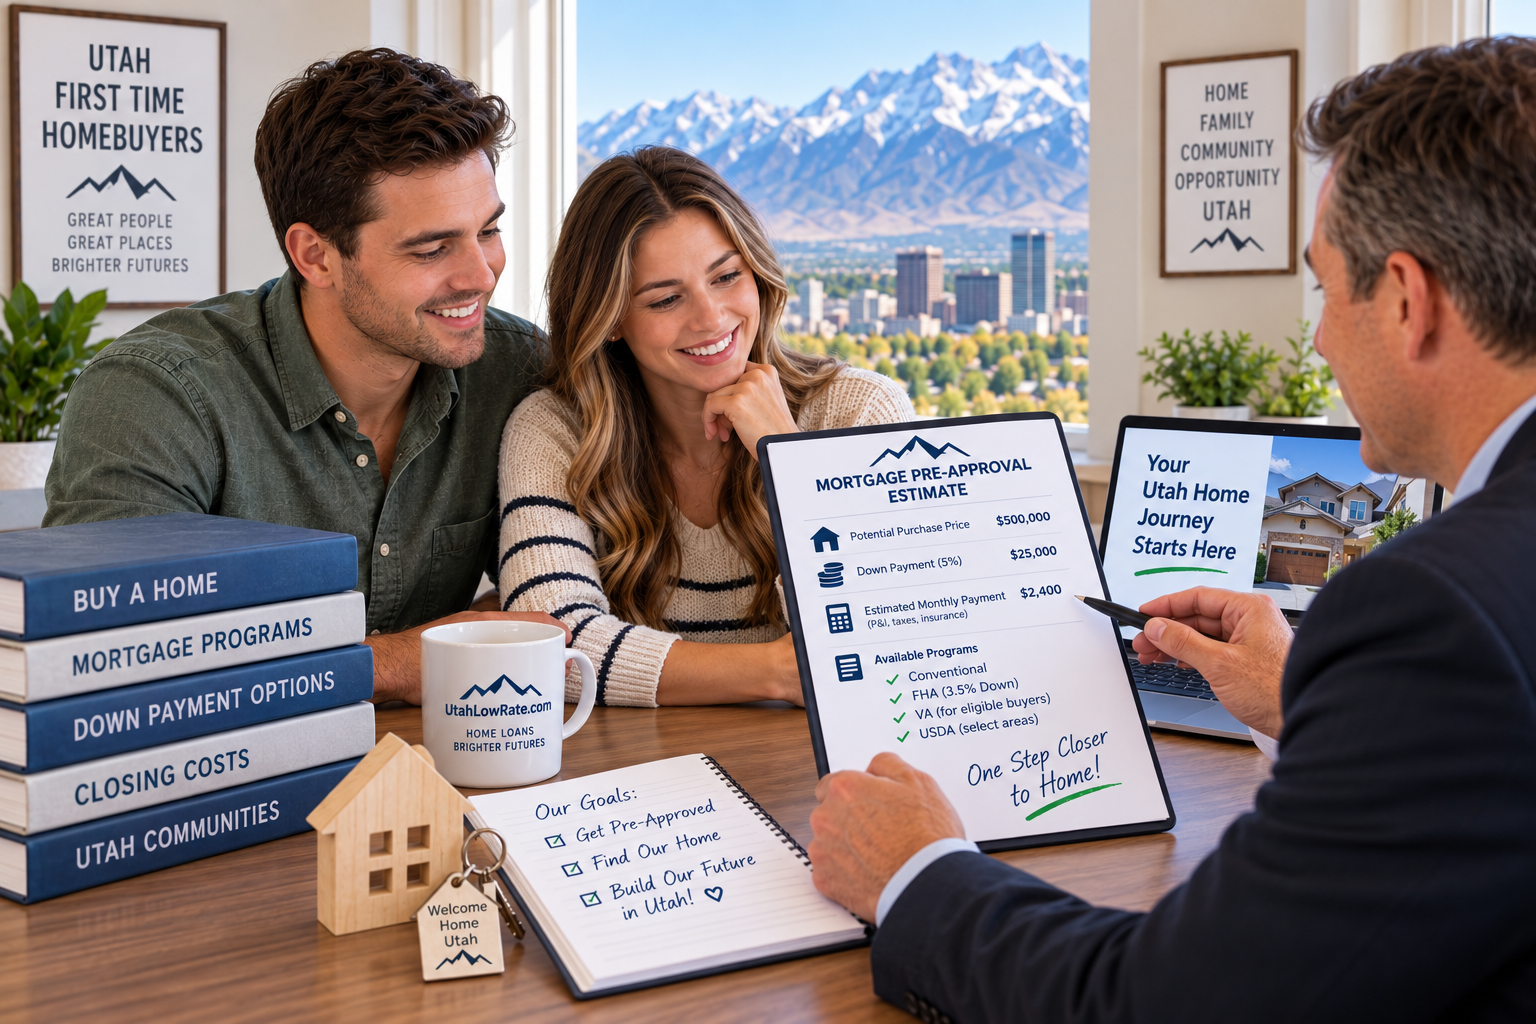
First-time buyers often have questions about down payment, monthly payment, credit and how much cash will be needed at closing.
A pre-approval can help you estimate:
- Potential purchase price
- Mortgage amount
- Down payment
- Estimated monthly housing payment
- Closing-cost considerations
- Available loan programs
- Credit considerations
- Reserve requirements when applicable
You do not necessarily need a 20% down payment to purchase a home.
Available down-payment options depend on the loan program, borrower qualifications, occupancy and transaction.
How Much House Can I Afford in Utah?
There is no universal home price or mortgage amount that applies to every buyer.
Your potential mortgage qualification can depend on:
- Qualifying gross income
- Monthly debts
- Credit profile
- Down payment
- Interest rate
- Loan term
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA dues
- Property type
- Occupancy
- Mortgage program
Qualification and personal affordability are also different.
A lender may determine that you meet guidelines for a particular mortgage amount, but your preferred budget may be lower after considering savings goals, transportation, childcare, travel, utilities, home maintenance and other priorities.
Use the Utah Mortgage Calculator to explore estimated payments, then request an individualized pre-approval for borrower-specific qualification.
How Long Does Mortgage Pre-Approval Take in Utah?
The amount of time required depends on the complexity of your financial profile, mortgage program and whether the requested documentation is readily available.
A straightforward W-2 borrower with complete documentation may require less review than a borrower with multiple businesses, complex tax returns, several properties or a large jumbo transaction.
For that reason, begin the process before you need to submit an offer whenever possible.
How Long Is a Mortgage Pre-Approval Good For?
Pre-approval letters are not permanent.
The Consumer Financial Protection Bureau notes that pre-approval letters can have expiration dates and says they are typically valid for approximately 30 to 60 days, although the actual period depends on the lender and circumstances.
If your letter expires while you are still shopping, updated credit, income, employment or asset information may be required.
Does Mortgage Pre-Approval Affect Your Credit?
A mortgage pre-approval commonly involves a credit check.
A lender's mortgage application credit inquiry is generally a hard inquiry, which can have a small effect on credit scores.
Credit scoring models may treat multiple mortgage inquiries made within an applicable rate-shopping period differently from unrelated credit applications.
If you are preparing for a mortgage, avoid assuming that every credit inquiry works the same way.
Can I Get Pre-Approved Before Finding a House?
Yes.
In fact, that is often the point of getting pre-approved.
You can begin with an estimated purchase price, down payment and property type before you have selected a specific address.
Once you find a property, the actual purchase price, taxes, homeowners insurance, HOA dues and other property-specific information can be incorporated into the financing analysis.
Can I Get Pre-Approved With Student Loans or Other Debt?
Potentially.
Student loans, auto loans, credit cards and other recurring obligations may affect the debt calculations used for mortgage qualification.
The effect depends on the type of debt, required payment, loan program and applicable underwriting guidelines.
Rather than assuming that a particular debt prevents you from buying, have your complete financial profile reviewed.
What Happens After I Get Pre-Approved?
Once you have a pre-approval, you can begin or continue shopping within a price range that reflects your financing analysis.
When you identify a property:
- Review the proposed purchase price.
- Update the estimated housing payment.
- Account for property taxes, insurance and HOA dues.
- Confirm your down-payment and closing-cost strategy.
- Update the pre-approval letter when appropriate.
- Submit your purchase offer.
- If your offer is accepted, proceed with processing, property review and underwriting.
Your financing will continue to be evaluated through the mortgage process.
What Should I Avoid After Getting Pre-Approved?
A pre-approval is based on your financial circumstances at the time of review.
Before closing, consider discussing significant financial changes with your mortgage professional before making them.
Changes that can potentially affect qualification include:
- Financing a vehicle
- Opening new credit accounts
- Increasing credit-card balances
- Changing jobs
- Changing compensation structure
- Becoming self-employed
- Co-signing another loan
- Taking on additional debt
- Moving significant amounts between accounts
- Receiving large deposits that require documentation
- Changing the source of your down payment
Keep your mortgage professional informed about significant changes to your employment, income, debts, credit or assets.
Mortgage Pre-Approval Throughout Utah
UtahLowRate.com works with qualified homebuyers throughout Utah, and local financing needs can differ considerably by market.
Salt Lake County
Buyers in Salt Lake City, Murray, Holladay, Millcreek, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman and surrounding communities can encounter a broad range of property values.
A useful pre-approval should reflect the actual neighborhood price range and financing scenario you are considering.
Utah County
Homebuyers in Lehi, Alpine, Highland, American Fork, Pleasant Grove, Orem, Provo, Saratoga Springs, Eagle Mountain and Spanish Fork may be considering everything from a first home to new construction or luxury financing.
Park City and the Wasatch Back
Higher property values in Park City, Deer Valley, Heber City, Midway, Jordanelle, Hideout and surrounding communities can make early jumbo and super jumbo planning especially useful.
Second homes, luxury properties and high-net-worth borrowers may also have different reserve, asset and underwriting considerations.
St. George and Southern Utah
Buyers in St. George, Washington, Ivins, Santa Clara and Hurricane may include local residents, retirees, relocation buyers and second-home purchasers.
Occupancy, income, assets and property type can affect the mortgage program being evaluated.
Northern Utah
Homebuyers in Ogden, Layton, Farmington, Bountiful and surrounding Davis and Weber County communities can also request pre-approval for conventional, FHA, VA, jumbo and other eligible mortgage programs.
Why Work with Utah Mortgage Broker Daniel Paris?
A mortgage pre-approval is more useful when it considers the programs that may fit your actual financial profile.
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified Utah borrowers seeking financing including:
- Conventional mortgages
- FHA loans
- VA loans
- Jumbo mortgages
- Super jumbo mortgages
- Bank statement mortgages
- 1099 mortgage programs
- Profit & Loss mortgages
- Asset-based mortgage programs
- Other non-QM financing
As a mortgage broker, UtahLowRate.com can evaluate Utah mortgage loan programs from wholesale mortgage lending sources rather than limiting the discussion to a single type of borrower or mortgage program.
The objective is straightforward: understand your financial profile, evaluate available mortgage options and help you prepare your financing before you make an offer.
Utah Mortgage Pre-Approval FAQ
How do I get pre-approved for a mortgage in Utah?
Start by completing a mortgage application and providing information about your income, employment, assets, debts, credit, down payment and proposed purchase. Available mortgage programs and preliminary qualification can then be evaluated.
When should I get pre-approved?
Consider getting pre-approved when you are preparing to seriously shop for homes. Starting early can also help identify financing issues before you are under contract.
How long does a Utah mortgage pre-approval take?
Timing depends on the borrower, documentation and program. Complex self-employed, jumbo and alternative-documentation scenarios may require additional review.
How long does a pre-approval letter last?
The period varies by lender. Pre-approval letters commonly have expiration dates, and updated financial information may be required if you continue shopping after expiration.
Does getting pre-approved hurt my credit?
A mortgage lender commonly checks credit during the pre-approval process. A hard mortgage inquiry can have a small effect on credit scores.
Can I get pre-approved before finding a house?
Yes. You can begin pre-approval using a proposed price range and update the financing once you select a specific property.
What credit score do I need for mortgage pre-approval?
There is no single credit score requirement for every mortgage. Requirements vary by loan program, lender and borrower profile.
Can I get pre-approved without 20% down?
Potentially. Some mortgage programs permit eligible borrowers to purchase with less than 20% down, subject to program and underwriting requirements.
Can self-employed borrowers get pre-approved?
Potentially. Self-employed borrowers may have traditional tax-return qualification or eligible alternative-documentation options such as bank statement, 1099 or Profit & Loss programs.
Can I get pre-approved for a jumbo mortgage?
Potentially. Jumbo qualification depends on factors including loan amount, credit, income, assets, reserves, property and loan-to-value ratio.
Can I get pre-approved for a VA loan?
Eligible borrowers may obtain VA mortgage pre-approval subject to VA eligibility and applicable lender requirements.
Does pre-approval guarantee that my mortgage will close?
No. A pre-approval is not final loan approval or a commitment to lend. Final approval depends on underwriting, acceptable documentation, property eligibility and satisfaction of applicable loan conditions.
Get Your Utah Mortgage Pre-Approval
Prepare your financing before making an offer on a Utah home.
Whether you are buying your first home in Salt Lake City, moving to Lehi, purchasing a luxury property in Park City, relocating to St. George or buying elsewhere in Utah, reviewing your financing early can help you approach your home search with better information.
Start Your Mortgage Pre-Approval
Get My Utah Mortgage Pre-Approval
Check My Home-Buying Budget
Compare My Mortgage Options
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
NMLS #243976
Helpful Mortgage Resources
For independent consumer information about mortgage pre-approval, credit and shopping for a mortgage, review resources from the Consumer Financial Protection Bureau.
Eligible Veterans and service members can review VA home-loan eligibility and Certificate of Eligibility information through the U.S. Department of Veterans Affairs.
Important Disclosure: This page is for educational and informational purposes and is not an offer, approval, guarantee or commitment to lend. Mortgage programs, rates, APRs, fees, terms, credit requirements, loan-to-value limits, documentation standards and availability can change. All financing is subject to applicable lender and investor guidelines, acceptable documentation, property eligibility, appraisal requirements when applicable, underwriting and final approval.

