
Profit and Loss Home Loan Questions and Answers Utah
By Daniel Paris, Utah Mortgage Broker | NMLS #243976 | Last reviewed: October 14, 2026
Profit and loss home loan questions and answers Utah business owners can use go beyond definitions. These examples explain how ownership, expenses, business changes, and property restrictions can affect a mortgage review.
Quick answer
A workable P&L mortgage scenario needs eligible income and an eligible property. When a question involves a specific number or home, obtain a current lender review rather than assuming a general description applies.
Request a scenario review • Apply online • Call 801-604-4949
My P&L shows $240,000 in sales. Is that $20,000 of monthly income?
No. Subtract eligible business expenses first. If expenses are $120,000, net profit is $120,000, or $10,000 monthly before ownership and lender adjustments. Use net profit under the lender’s method rather than gross receipts.
Next: Read the related guide.
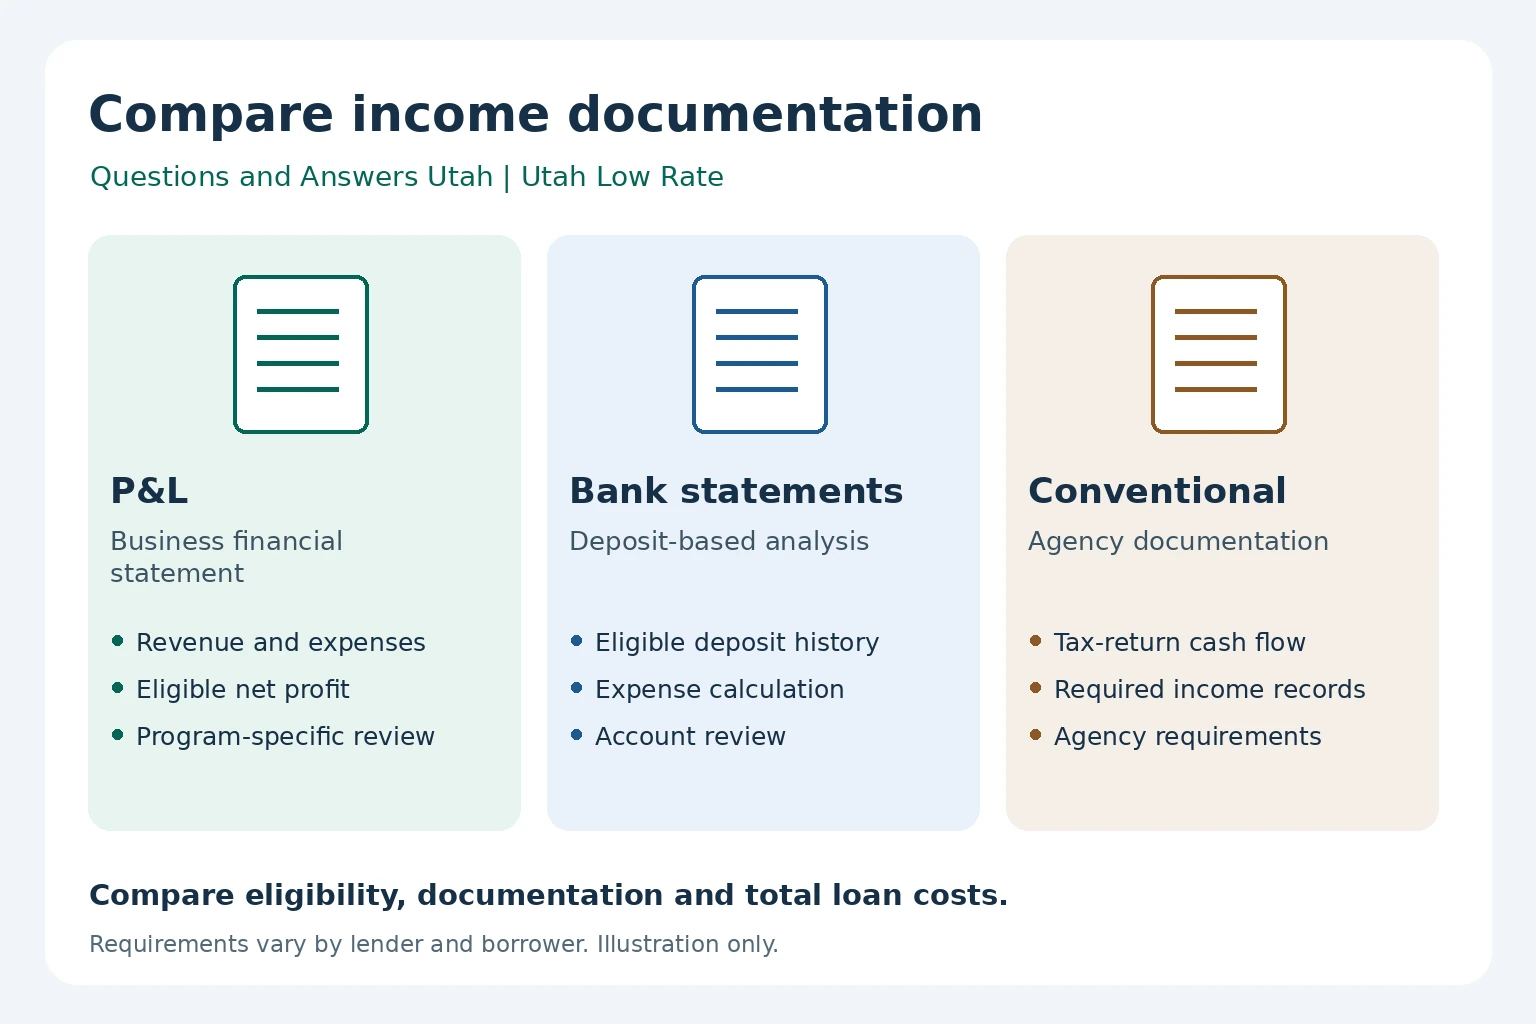
My tax returns show less income than my current P&L. Which loan should I choose?
Compare both methods. A P&L route may fit if the statement and supporting records meet its rules. Conventional financing may still work and should be compared on cost. Explain why the figures differ instead of assuming the higher number will be accepted.
Next: Read the related guide.
I own 50% of a business. Can I use all its profit?
Do not assume so. Ownership and access to income matter. If annual net profit is $180,000, a simple 50% share is $90,000, or $7,500 monthly before adjustments. The lender determines usable income.
Next: Read the related guide.
I have a year-end P&L but no year-to-date statement. Is that enough?
Ask the lender. It may require current figures and a prior full period. A dated statement can leave a gap in the review. Confirm coverage and preparation-date rules before paying for another version.
Next: Read the related guide.
My biggest client ended a contract. Should I disclose it?
Yes. Income stability and current operations matter. Provide accurate updated records and explain the change. A prior profitable period does not guarantee the lender can use the same income after a material change.
Next: Read the related guide.
I want a home on acreage. Can strong income solve the property issue?
No. A lender may exclude rural homes, substantial agricultural use, or certain acreage. Send the listing and parcel details for early review. Compare another program if the home is outside its rules.
Next: Read the related guide.
I want a Park City condo that can be rented nightly. Is it a second home?
The lender must evaluate actual use and project features. A rental pool or hotel services may change eligibility. Local rental permission and HOA rules are separate from the mortgage decision. Disclose your plan before applying.
Next: Read the related guide.
My spouse has a salary. Can we combine it with my P&L income?
Possibly under an available program. Each source needs its documents, and both borrowers’ debts matter. Ask for a calculation using the full household application rather than adding incomes informally.
Next: Read the related guide.
I need 10% down. Does a bank statement option prove a P&L option will allow it?
No. The programs have different matrices. Confirm the P&L lender’s LTV tier for your credit, amount, occupancy, and property. Compare a bank statement route if it better fits your cash available for closing.
Next: Read the related guide.
Can I move business cash into my personal account right before closing?
Ask first. The lender may need ownership, source-of-funds, and liquidity evidence. Keep a clear transfer trail. Review the effect on working capital before withdrawing funds.
Next: Read the related guide.
Can I refinance later if conventional rates improve?
You can explore refinancing later, but approval and savings are not guaranteed. Future documents, credit, value, equity, costs, and rates matter. Choose a loan affordable under its current terms.
Next: Read the related guide.
My monthly payment looks affordable. Why do reserves still matter?
Reserves are a separate eligibility condition and a cushion after closing. Funds spent on down payment or costs are no longer reserves. Ask which assets count and how required months are calculated.
Next: Read the related guide.
What to bring to a scenario review
Share business type, ownership, history, estimated net income, property location and use, loan amount, credit range, available funds, and existing documents. Use the secure application process for sensitive financial records.
Explore the Utah P&L cluster
Utah P&L home loan hub • Guidelines • FAQ • Scenario questions and answers
Request a scenario review • Apply online • Call 801-604-4949

