
Profit and Loss Home Loans Summit County Utah
By Daniel Paris, Utah Mortgage Broker | NMLS #243976 | Last reviewed: October 14, 2026
Profit and Loss Home Loans Summit County Utah may help eligible self-employed buyers and homeowners document income with an acceptable business P&L. Daniel Paris at Utah Low Rate helps compare this approach with other mortgage options. Approval depends on the borrower, property, and lender’s current rules.
Quick answer
A P&L home loan may use a professionally prepared profit-and-loss statement to establish qualifying business income. It may also require supporting bank statements. For Summit County Utah, review the property and intended occupancy before assuming a program fits.
Request a scenario review • Apply online • Call 801-604-4949
Profit and Loss Home Loans Summit County Utah: local considerations
This guide serves Park City, Coalville, Kamas, and surrounding Summit County communities.
Summit County buyers should consider loan amount, occupancy, and property type together. Resort condos can have rental-management features some lenders do not accept. Larger loans may require different documentation, LTV limits, or reserves. A P&L program’s maximum loan size is separate from whether the loan is classified as jumbo.
City and county names denote service areas, not different underwriting standards.
Larger loans, resort condos, and reserves
A Park City consultant wants a second-home condo. Review the project, occupancy, loan amount, and business income. Disclose any mandatory rental arrangement at the start. A condo marketed as a residence may not fit the selected program.
This is an illustrative situation, not an approval or quoted offer. Confirm the lender’s requirements before ordering a mortgage-specific P&L.
How P&L income is reviewed
Start with net profit after business expenses, rather than gross sales or total deposits. The lender applies its own averaging, ownership, and adjustment rules. A partial owner may not be able to use all business profit. Recent changes, losses, and inconsistent records affect the income accepted.
Example: $120,000 of eligible annual net profit divided by 12 is $10,000 monthly before lender adjustments. At 50% ownership, a proportional calculation would be $5,000. Actual qualifying income can differ. This arithmetic does not establish a maximum loan or approval.
Credit, down payment, and reserves
There is no single minimum score or down payment for every P&L loan. Credit, loan size, LTV, occupancy, housing history, debts, and property type matter together. Confirm the actual program rather than borrowing rules from a bank statement loan.
Reserves are eligible assets remaining after closing. They are separate from the down payment and closing costs. Ask which assets count and how many months of the lender-defined housing payment must remain.
Documents to prepare
- Profit-and-loss statement covering the required period, plus year-to-date figures if requested.
- Preparer contact information and acceptable professional qualifications.
- Business history, ownership, and evidence of current operations.
- Supporting business bank statements if required for income verification.
- Asset statements showing funds for closing and eligible reserves.
- Identification, debt details, current housing costs, and purchase contract or refinance information.
Purchase, refinance, and cash-out options
For a purchase, review income and property eligibility before making an offer. For a refinance, compare the current loan with the proposed rate, APR, fees, term, and payment. Cash-out can have separate equity, seasoning, and reserve rules. Taking equity out does not increase business profit.
Ask for a dated written estimate based on credit, property, occupancy, amount, and lock period. A general rate page is context rather than your P&L quote. Get Today’s Utah Rate.
Compare your documentation options
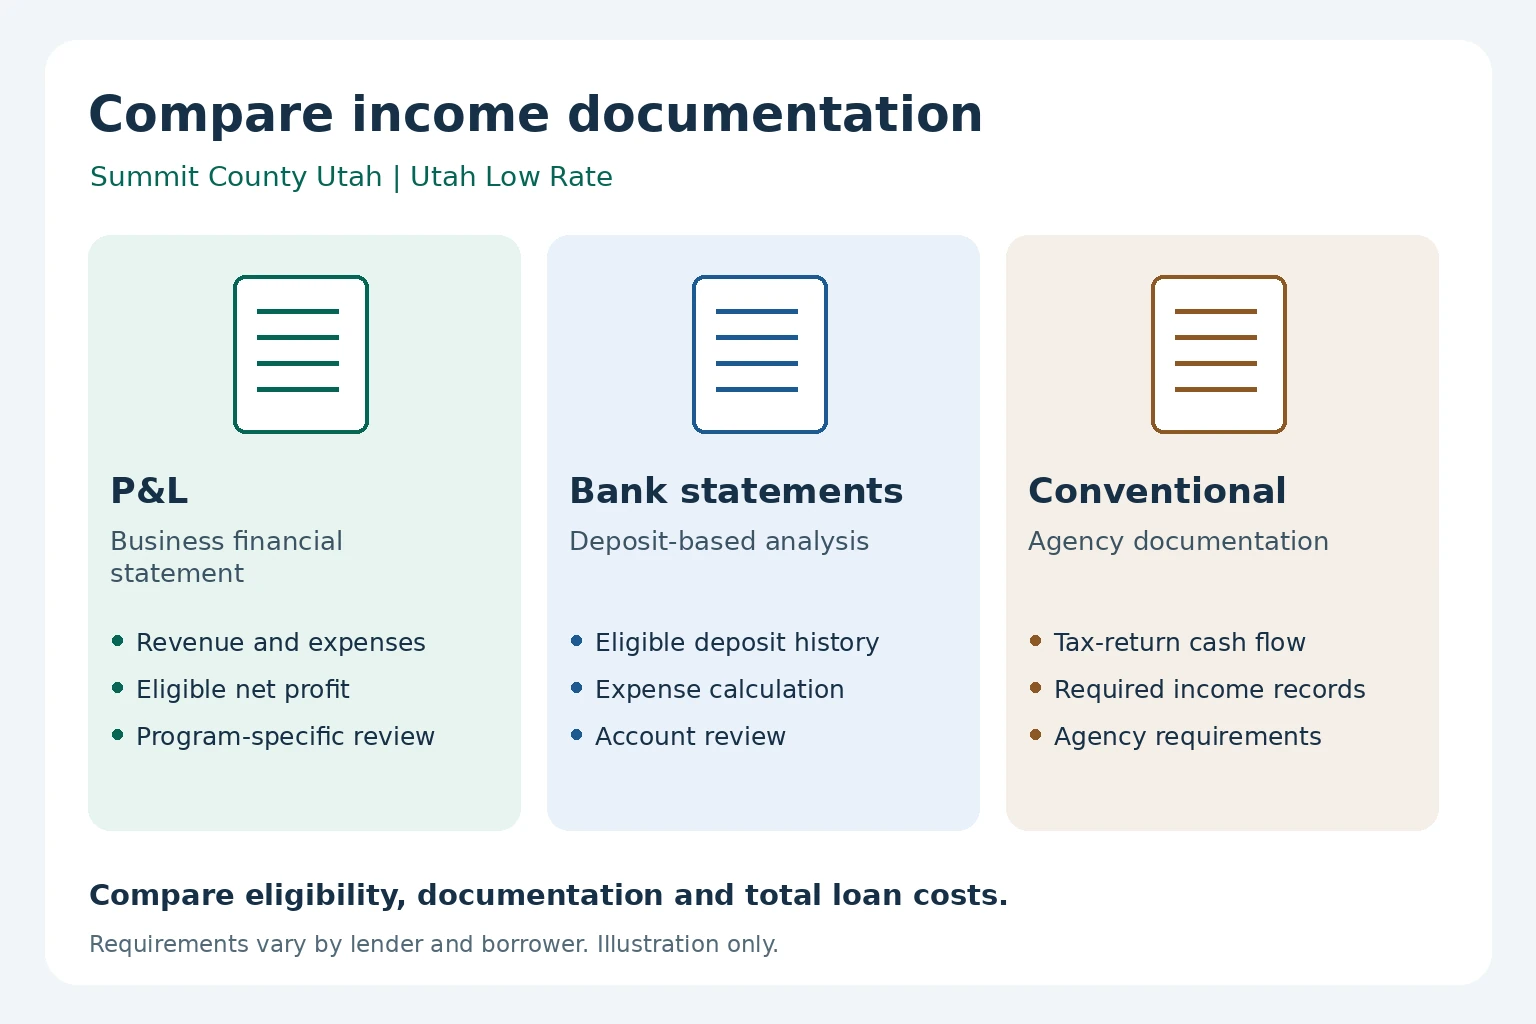
| Path | Income review | When to compare |
|---|---|---|
| P&L | Eligible business revenue, expenses, and net profit | Your financial statements support documented income |
| Bank statements | Eligible deposits and lender expense calculation | Deposit history may support another income method |
| Conventional | Agency documentation and cash-flow analysis | Traditional records may support qualification |
| 1099 | Eligible contractor income under program rules | You receive Form 1099 income |
| DSCR | Eligible rental-property cash flow | You are financing an investment property |
Compare bank statement loans, 1099 mortgages, conventional financing, and Utah jumbo mortgages.
Steps to a useful mortgage review
- Share the property address or target area, actual intended use, price or value, and loan amount.
- Describe your business, ownership, history, and available income records.
- Review credit, debts, closing funds, and reserves.
- Confirm the preparer and P&L-period rules before paying for new paperwork.
- Complete the application, appraisal, and underwriting requirements.
Avoid common mistakes
Do not equate sales with profit, omit real expenses, or treat transfers as revenue. Do not assume “P&L only” removes asset or property documents. Disclose business changes and unusual deposits early. Check property restrictions before relying on a program.
Frequently asked questions
Can a resort condo qualify?
Not always. Hotel services, rental pools, project finances, and other features affect acceptance. Request project review early.
Do I need tax returns for a P&L mortgage in Summit County Utah?
Some alternative-documentation programs do not use tax returns as the qualifying-income document. Confirm the selected lender’s rules. Other records and full underwriting still apply.
Explore the Utah P&L cluster
Utah P&L home loan hub • Guidelines • FAQ • Scenario questions and answers
Request a scenario review • Apply online • Call 801-604-4949

