
Content updated: September 29, 2026
Answers for Real Estate Investors
If you have questions about DSCR loans in Utah, this FAQ gives real estate investors clear, direct answers. Learn how DSCR loans work, how rental income is evaluated, whether tax returns are needed, how credit and down payment can affect financing, and whether DSCR loans may work for purchases, refinances, cash-out transactions, LLCs, and short-term rentals.
Check My DSCR Scenario or call 801-604-4949.
Daniel Paris with UtahLowRate.com helps real estate investors compare DSCR mortgage programs for qualifying rental properties throughout Utah.
Quick Answer: A DSCR loan is an investment-property mortgage that generally focuses on the rental property's qualifying income compared with its required housing or debt obligation. Unlike many traditional mortgages, personal employment income is generally not the primary qualification method. Credit, equity, reserves, property eligibility and lender guidelines still matter.
Important: DSCR programs are not standardized. Rates, credit requirements, DSCR calculations, LTV limits, reserves, property eligibility, prepayment provisions and documentation can vary by lender and can change.
DSCR Loan FAQ Utah: Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Question | Quick Answer |
|---|---|
| What does DSCR mean? | Debt Service Coverage Ratio |
| What is the main qualification focus? | Qualifying rental-property cash flow |
| Are DSCR loans for primary residences? | Generally no |
| Are they designed for investment properties? | Yes |
| Are personal tax returns always required for qualifying income? | Often no |
| Is W-2 income normally the main qualification method? | No |
| Can I purchase a rental property? | Potentially |
| Can I refinance a rental property? | Potentially |
| Can I take cash out? | Some programs permit it |
| Can an LLC be used? | Some programs permit eligible entities |
| Are short-term rentals eligible? | Some lenders permit them |
| Does credit still matter? | Yes |
| Does LTV matter? | Yes |
| Can reserves be required? | Yes |
| Can prepayment penalties apply? | Depending on program and applicable law |
| Are all lender guidelines the same? | No |
For detailed qualification standards, use the DSCR Loan Requirements Utah page. For payment and ratio calculations, use the DSCR Loan Calculator Utah page.
What Is a DSCR Loan in Utah?
A DSCR loan is a mortgage primarily designed for real estate investors.
DSCR stands for Debt Service Coverage Ratio. The lender generally compares qualifying rental income from the investment property with the property's applicable monthly debt or housing obligation.
That makes the property itself a major part of the qualification analysis.
This differs from a traditional owner-occupied mortgage, where employment income, personal debt-to-income ratio and tax-return income can play a much larger role.
For a complete overview, visit the DSCR Mortgage Loans in Utah hub:
How Is DSCR Calculated?
The basic formula is:
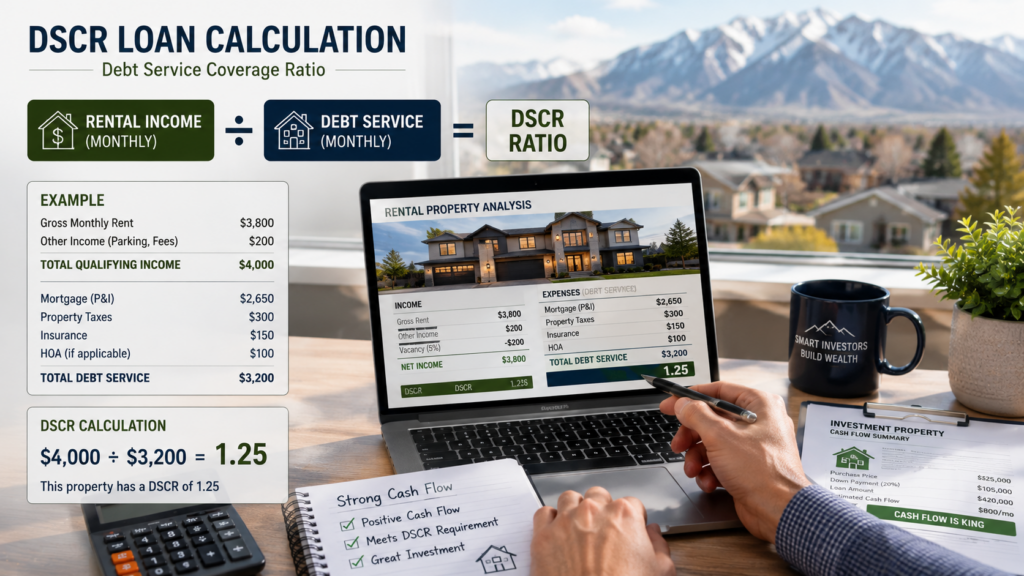
DSCR = Qualifying Rental Income ÷ Qualifying Property Debt Obligation
For example, if qualifying monthly rent is $4,000 and the applicable monthly obligation is $3,200:
$4,000 ÷ $3,200 = 1.25 DSCR
A 1.25 ratio means the qualifying rent is 125% of the debt obligation used in that calculation.
The simple formula is easy. Determining which rent and expenses a particular lender will use can be more complicated.
See DSCR Loan Calculator Utah for detailed examples:
What Does a 1.00 DSCR Mean?
A 1.00 DSCR generally means the qualifying rental income equals the applicable property debt obligation used in the calculation.
For example:
$3,000 qualifying rent ÷ $3,000 qualifying obligation = 1.00 DSCR
A ratio above 1.00 means qualifying rent exceeds that obligation. A ratio below 1.00 means qualifying rent is lower than it.
Individual lender requirements vary.
Is a Higher DSCR Better?
From a property cash-flow perspective, a higher ratio means there is more qualifying rental income relative to the debt obligation being measured.
For example, a property with a 1.30 DSCR has more qualifying rental-income coverage than the same property at 1.00.
However, DSCR is only one part of underwriting.
Credit score, LTV, reserves, loan amount, property type, transaction structure and lender guidelines can also affect eligibility and pricing.
Can I Get a Utah DSCR Loan With a Ratio Below 1.00?
Potentially.
Some lenders may consider lower-DSCR or no-ratio scenarios. Other lenders require the property to meet a specified minimum ratio.
A lower ratio may affect available LTV, pricing or other underwriting terms. Stronger credit, additional equity or reserves may also become more important depending on the program.
For a deeper discussion, see:
No-Ratio DSCR Loans Utah
Do DSCR Loans Require Tax Returns?
Personal tax returns are often not used to establish qualifying employment income for a DSCR mortgage.
The central concept is different: the lender generally evaluates the investment property's qualifying rental cash flow instead of qualifying primarily from the borrower's traditional employment income.
That does not mean there is no documentation.
A lender can still require credit, asset, reserve, entity, appraisal, title, insurance, property and transaction documentation.
Do I Need a Job to Qualify for a DSCR Loan?
Traditional employment income is generally not the primary qualification method for a DSCR mortgage.
That can make DSCR financing useful for real estate investors who are self-employed, own multiple businesses, have several rental properties or have complex tax returns.
The loan still requires underwriting. Property cash flow does not eliminate credit, asset, reserve, equity or property requirements.
Do DSCR Lenders Calculate Personal Debt-to-Income Ratio?
Traditional personal DTI is generally not the central qualification method for a DSCR loan.
Instead, the lender focuses heavily on the rental property's qualifying income relative to its applicable debt obligation.
That distinction is one of the main reasons DSCR financing can appeal to investors who already own several financed properties.
What Credit Score Do I Need for a DSCR Loan in Utah?
There is no single credit-score requirement that applies to every Utah DSCR lender.
Credit can affect:
- Eligibility
- Interest rate
- Loan-to-value limits
- Required equity
- Cash-out options
- Reserve requirements
- Available loan structures
Instead of publishing one minimum as though it applies universally, compare your actual credit profile against currently available programs.
See:
DSCR Loan Credit Score Utah
How Much Down Payment Do I Need for a Utah DSCR Loan?
There is no universal down-payment percentage for every DSCR program.
The required equity can depend on credit score, DSCR, property type, loan amount, transaction type and lender guidelines.
A borrower with a stronger overall scenario may have different options from an investor with weaker credit or a property with lower rental-income coverage.
See:
DSCR Loan Down Payment Utah
What Is the Maximum LTV for a DSCR Loan?
Maximum loan-to-value limits vary.
Purchase, rate-and-term refinance and cash-out transactions can have different LTV limits. Credit, DSCR, property type, loan amount and other risk factors may also change the maximum financing available.
See:
DSCR Loan LTV Utah
Are DSCR Mortgage Rates Higher Than Conventional Rates?
They can be, but comparing a DSCR loan directly with a conventional owner-occupied mortgage is not always an apples-to-apples comparison.
DSCR pricing can be affected by:
- Credit score
- DSCR
- LTV
- Loan amount
- Property type
- Purchase versus refinance
- Cash-out
- Fixed versus adjustable structure
- Interest-only features
- Discount points
- Prepayment provisions
- Market conditions
Compare the complete financing structure rather than rate alone.
See:
DSCR Loan Rates Utah
Can I Pay Points to Lower a DSCR Mortgage Rate?
Depending on the program and current pricing, discount points may be available.
The important question is whether the upfront cost produces enough interest or payment savings during the expected holding period to justify that cost.
An investor expecting to refinance or sell relatively soon may reach a different conclusion from an investor planning to hold the property for many years.
See DSCR Loan Rates Utah for the points and break-even discussion.
Are Interest-Only DSCR Loans Available?
Interest-only structures may be available through certain DSCR programs.
During the interest-only period, the scheduled payment generally does not include regular principal amortization.
That can change monthly cash flow, but it also changes how the loan balance behaves.
Compare the payment structure, interest-only period, subsequent amortization, rate, points and total financing strategy before selecting an interest-only option.
Do DSCR Loans Have Prepayment Penalties?
Some business-purpose DSCR loans may include prepayment provisions where permitted.
The exact structure can vary substantially.
An investor planning to sell or refinance should understand the prepayment terms before closing, not after.
Compare the prepayment structure with your expected property holding period and exit strategy.
Can I Use a DSCR Loan to Buy a Rental Property in Utah?
Yes, qualifying DSCR programs are designed for investment-property financing.
They may be used by qualified investors purchasing eligible long-term rental properties and, with certain programs, other eligible investment-property types.
The property, borrower and transaction still have to meet the selected lender's guidelines.
Can I Use a DSCR Loan for a Primary Residence?
Generally, no.
DSCR programs are primarily designed for business-purpose investment properties rather than owner-occupied primary residences. UtahLowRate's existing DSCR guidance likewise identifies investment property as the primary use.
If you need alternative income documentation for a primary residence, a bank statement, 1099, Profit & Loss, conventional, jumbo or another qualifying mortgage program may be more appropriate.
Related internal link: Bank Statement Loans Utah
Can I Use a DSCR Loan for a Second Home?
A DSCR loan is generally intended for investment-property financing rather than a property being financed as a true second home.
Occupancy must be represented accurately.
If a property is actually intended to operate as a rental investment, discuss the appropriate investment-property financing structure rather than attempting to classify it incorrectly as a second home.
Can First-Time Real Estate Investors Get DSCR Loans?
Potentially.
Some programs accept first-time investors, while others can impose different guidelines based on investor or housing history.
A first-time investor should have the complete scenario reviewed rather than assuming that prior landlord experience is universally required.
Can an LLC Get a DSCR Loan in Utah?
Potentially.
Certain DSCR lenders allow title or borrowing structures involving eligible LLCs or other entities.
Entity requirements can vary, and personal guarantees or other documentation may still be required.
Discuss the proposed ownership structure before closing or transferring title.
For legal and tax questions about entity ownership, consult qualified legal and tax professionals.
Can I Close a DSCR Loan in My Personal Name?
Depending on the program, individual ownership may be permitted.
Other investors may prefer or require particular entity structures.
The appropriate vesting arrangement depends on lender requirements and the investor's legal and tax strategy.
Do not change ownership solely for mortgage purposes without understanding the legal and tax consequences.
Can I Use a DSCR Loan for an Airbnb or VRBO Property in Utah?
Potentially.
Certain DSCR programs may consider eligible short-term rental properties. However, lender approval does not mean that short-term rentals are legally permitted at the property. UtahLowRate's existing DSCR guidance recommends independently verifying city and county rules, zoning, HOA restrictions, licensing and property-specific rental restrictions.
See:
DSCR Loans for Short-Term Rentals Utah
How Is Rent Determined for a DSCR Loan?
The answer depends on the transaction and lender.
A lender may consider acceptable lease information, appraisal-based market rent or other approved rental documentation.
The lender's method matters because the amount of qualifying rent directly affects the DSCR calculation.
Do not assume that your advertised rent, projected Airbnb revenue or personal rent estimate will automatically equal qualifying mortgage rent.
Can Projected Market Rent Be Used?
Potentially.
Certain transactions may rely on acceptable market-rent evidence instead of an established lease, subject to lender requirements.
The appraisal and applicable rental schedule can therefore become important parts of DSCR underwriting.
Ask how qualifying rent will be established before relying on a projected DSCR.
Can I Use Short-Term Rental Income to Calculate DSCR?
Possibly, but lender methodologies vary.
Some programs may have methods for evaluating eligible short-term rental properties, while others may use more conservative rental evidence.
Investors should verify both the mortgage lender's income method and whether short-term rental activity is permitted at the specific property.
Can I Get Cash Out With a DSCR Refinance?
Potentially.
DSCR cash-out refinance programs may allow qualified real estate investors to access equity from eligible investment properties.
Maximum LTV, credit, property seasoning, ownership history, DSCR, reserves and proceeds requirements can vary.
See:
DSCR Cash-Out Refinance Utah
Can I Refinance an Existing Rental Into a DSCR Loan?
Potentially.
A qualifying rental property may be eligible for a rate-and-term or cash-out DSCR refinance, depending on lender guidelines.
A refinance review should compare the existing loan with the proposed:
- Rate
- APR
- Payment
- Points
- Closing costs
- Prepayment terms
- Loan term
- Cash-out amount
- Break-even period
Refinancing should solve a financial or investment objective rather than simply replace one loan with another.
Can DSCR Cash-Out Proceeds Be Used to Buy Another Rental?
Potentially, subject to the lender's cash-out and funds requirements.
Real estate investors sometimes use available equity as part of a broader portfolio strategy.
Before proceeding, evaluate the cost of extracting equity from the existing property and the expected economics of the next investment.
Are Mortgage Reserves Required for DSCR Loans?
They may be.
Reserve requirements can depend on the lender, loan amount, credit profile, property, DSCR and transaction.
Having substantial liquidity can also strengthen an investor's overall financial position even when the minimum reserve requirement is lower.
See DSCR Loan Requirements Utah for a more detailed underwriting discussion.
Can Gift Funds Be Used on a DSCR Loan?
Gift-fund policies vary by lender.
Business-purpose investment-property programs do not necessarily follow the same gift-fund rules as conventional owner-occupied mortgages.
Verify acceptable sources of funds before moving money or making a purchase offer dependent on a particular funding structure.
Can Foreign Nationals Get DSCR Loans in Utah?
Certain investment-property lenders may offer financing for eligible foreign-national borrowers.
These programs can have specialized requirements involving identity documentation, assets, reserves, credit alternatives, entity structures and funds transfer.
Availability should be reviewed based on the borrower's specific status and transaction.
Can I Get a DSCR Loan with Multiple Rental Properties?
Potentially.
In fact, DSCR financing can be useful for investors with larger portfolios because qualification generally focuses heavily on the subject property's rental cash flow instead of relying primarily on a traditional personal DTI calculation.
Each financed property and transaction still must satisfy applicable lender guidelines.
Can I Have More Than One DSCR Loan?
Potentially.
There is not one universal DSCR rule limiting every investor to a single financed rental property.
Lender exposure limits, borrower liquidity, property count, credit and portfolio requirements can differ.
Investors building portfolios should discuss both the current transaction and future acquisition plans.
Are Condominiums Eligible for DSCR Loans?
Some condominiums may qualify.
Eligibility can depend on both borrowers underwriting and the condominium or project itself.
A property being a rental does not automatically make the project acceptable to every lender.
Can I Finance a 2–4 Unit Property with a DSCR Loan?
Certain DSCR programs may permit qualifying 2–4-unit residential investment properties.
Rental-income methodology and property analysis can differ from a single-family rental.
Have the exact property reviewed before relying on a particular financing structure.
Can I Finance a Rural Utah Rental Property With DSCR?
Potentially.
Rural properties can require additional review because property marketability, comparable sales, rent comparables, acreage and property characteristics may affect lender eligibility.
This can be especially relevant in smaller Utah markets where comparable rental data may be limited.
Can I Use DSCR Financing in Park City?
Potentially.
Qualified investors may use DSCR financing for eligible investment properties in Park City and surrounding Summit County markets.
Higher property values, condominium characteristics, short-term rental rules and HOA restrictions can make property-specific underwriting especially important.
Can I Get a DSCR Loan in Salt Lake City?
Potentially.
DSCR financing may be available for eligible investment properties throughout Salt Lake City and Salt Lake County, including surrounding rental markets such as Murray, Holladay, Millcreek, Sandy, Draper, South Jordan, West Jordan, Riverton and Herriman.
Are DSCR Loans Available in St. George?
Potentially.
Qualified investors may finance eligible rental properties in St. George and Washington County through available DSCR programs.
Short-term rental investors should separately verify local zoning, licensing, HOA and rental-use restrictions.
Are DSCR Loans Available Throughout Utah?
Yes, qualifying programs may be available for eligible investment properties throughout Utah.
UtahLowRate.com works with real estate investors in markets including:
Salt Lake County: Salt Lake City, Murray, Holladay, Sandy, Draper, South Jordan and surrounding communities.
Utah County: Lehi, American Fork, Alpine, Highland, Orem, Provo, Saratoga Springs and surrounding communities.
Summit County: Park City, Deer Valley, Canyons-area communities, Kimball Junction and surrounding markets.
Wasatch County: Heber City, Midway and surrounding communities.
Washington County: St. George, Washington, Ivins, Santa Clara, Hurricane and surrounding Southern Utah markets.
Davis, Weber, Cache and other Utah counties: Property and program eligibility should be reviewed individually.
DSCR Loan FAQ Utah: Questions to Ask Before Choosing a Lender
Do not compare DSCR lenders based only on an advertised interest rate.
Ask:
- How will qualifying rental income be determined?
- What DSCR does this specific program require?
- What LTV applies to my transaction?
- How does my credit affect pricing and LTV?
- What reserves are required?
- Are there discount points?
- Is there a prepayment penalty or similar provision?
- Is an interest-only option available?
- Is my property type eligible?
- Is an LLC permitted?
- How are short-term rentals evaluated?
- What are the cash-out seasoning requirements?
- What lender fees and third-party costs apply?
- What documentation is required before closing?
This type of comparison is more useful than asking only, “What is your DSCR rate?”
Explore the Utah DSCR Loan Resource Center
Use the UtahLowRate DSCR cluster to go deeper into the part of the loan that matters to your transaction.
DSCR Mortgage Loans in Utah — Main Guide
/dscr-mortgage-loans-in-utah/
DSCR Loan Requirements Utah
/dscr-loan-requirements-utah/
DSCR Loan Rates Utah
/dscr-loan-rates-utah/
DSCR Loan Calculator Utah
/dscr-loan-calculator-utah/
DSCR Loan FAQ Utah
/dscr-loan-faq-utah/
DSCR Cash-Out Refinance Utah
/dscr-cash-out-refinance-utah/
No-Ratio DSCR Loans Utah
/no-ratio-dscr-loans-utah/
DSCR Loans for Short-Term Rentals Utah
/dscr-loans-short-term-rentals-utah/
DSCR Loan Credit Score Utah
/dscr-loan-credit-score-utah/
DSCR Loan Down Payment Utah
/dscr-loan-down-payment-utah/
DSCR Loan LTV Utah
/dscr-loan-ltv-utah/
DSCR Loans Salt Lake City Utah
/dscr-loans-salt-lake-city-utah/
DSCR Loans Park City Utah
/dscr-loans-park-city-utah/
DSCR Loans St. George Utah
/dscr-loans-st-george-utah/
Publishing note: Keep the hub, Requirements, Rates and Calculator links near the top of this FAQ page. Put the complete cluster navigation near the bottom. As additional cluster pages go live, confirm their final WordPress slugs before publishing these links.
DSCR Loan vs. Bank Statement Loan: Which Question Should You Ask?
These programs solve different qualification problems.
A DSCR loan generally focuses on rental-property cash flow.
A bank statement mortgage generally focuses on eligible personal, or business bank deposits used to establish borrower income.
UtahLowRate's current bank-statement guidance makes this same distinction between the two programs.
If you are purchasing a rental property, ask whether DSCR financing fits the investment.
If you are self-employed and purchasing a primary residence, ask whether bank statement, 1099, P&L, conventional, jumbo or another alternative-documentation program fits your income.
Talk With Daniel Paris About a Utah DSCR Loan
Every investment property has different numbers.
A Park City short-term rental can present a very different financing scenario from a long-term rental in Salt Lake City, a duplex in Utah County or an investment property in St. George.
Daniel Paris can review:
- Property value or purchase price
- Expected or current rent
- Estimated housing expense
- DSCR
- Credit profile
- Down payment or equity
- Loan amount
- Property type
- Purchase or refinance
- Desired cash out
- Ownership structure
- Available reserves
Then available DSCR programs can be compared based on the actual transaction.
Get a Utah DSCR Loan Scenario Reviewed
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976-3138
27+ Years of Mortgage Lending Experience
Phone: 801-604-4949
CTA: Check My DSCR Scenario
CTA: Compare Utah DSCR Programs
CTA: Calculate My DSCR
Important DSCR Loan Disclosure
Mortgage programs, interest rates, APRs, fees, DSCR calculations, qualifying rental-income methods, credit requirements, loan-to-value limits, reserve requirements, prepayment provisions, loan amounts, property eligibility and underwriting guidelines can change.
Not every borrower or property will qualify.
This page is provided for general educational purposes and does not constitute tax, legal or investment advice, a commitment to lend, or a guarantee of financing. All loans are subject to lender and investor guidelines, underwriting approval, property eligibility and applicable laws and regulations.
Related guides: Utah DSCR loan guide · DSCR loan requirements · DSCR calculation guide · DSCR loan rates ·

