
Content updated: September 29, 2026
Primary Focus Keyword: DSCR loan calculator Utah
SEO Title: DSCR Loan Calculator Utah | Rent ÷ PITIA Formula
Check My DSCR Scenario or call 801-604-4949.
Meta Description: Use our DSCR loan calculator Utah guide to calculate rent ÷ PITIA, estimate DSCR, find break-even rent and compare Utah rental properties.
Recommended Slug: /dscr-loan-calculator-utah/
DSCR Loan Calculator Utah: Calculate Rent, PITIA and Break-Even DSCR
A DSCR loan calculator Utah rental property investors can use starts with two numbers. You need the property's qualifying monthly rent and its monthly housing expense.
The basic formula is simple:
DSCR = Qualifying Monthly Rent ÷ Monthly PITIA
For example, assume a Utah rental property has $4,000 in qualifying monthly rent and $3,200 in PITIA.
$4,000 ÷ $3,200 = 1.25 DSCR
A 1.25 DSCR means the qualifying rent equals 125% of the monthly property obligation used in the calculation.
This page explains how to calculate DSCR step by step. You will also learn how taxes, insurance, HOA dues, interest rates and loan amounts can change the result.
Quick Answer: A DSCR loan calculator Utah investors use divides qualifying monthly rent by the applicable monthly PITIA or other lender-defined property obligation. A 1.00 DSCR means rent equals that obligation. A 1.25 DSCR means rent equals 125% of it. The lender makes the final calculation under its current guidelines.
For a full overview of these loans, visit DSCR Mortgage Loans in Utah.
IMAGE — PLACE DIRECTLY BELOW QUICK ANSWER
Filename: dscr-loan-calculator-utah.webp
ALT: DSCR loan calculator Utah for rental property investors
Caption: Use a DSCR loan calculator to compare qualifying rental income with the monthly property obligation on a Utah investment property.
How Does a DSCR Loan Calculator Utah Investors Use Work?
A DSCR loan calculator Utah property investors use compares rental income with the property's monthly debt obligation.
For many residential DSCR programs, the basic calculation is:
DSCR = Qualifying Monthly Rental Income ÷ Qualifying Monthly Property Obligation
The denominator is often based on PITIA.
PITIA = Principal + Interest + Taxes + Insurance + Association Dues
The exact calculation can vary by lender and loan program.
That point matters.
Do not assume every DSCR lender will use the same rental income or the same expenses.
Simple DSCR Example
Assume a rental property has:
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Calculator Input | Amount |
|---|---|
| Qualifying monthly rent | $3,500 |
| Principal and interest | $2,300 |
| Property taxes | $300 |
| Insurance | $150 |
| HOA dues | $50 |
| Total PITIA | $2,800 |
Now divide rent by PITIA:
$3,500 ÷ $2,800 = 1.25
Estimated DSCR: 1.25
The qualifying rent equals 125% of the PITIA used in this example.
IMAGE — PLACE HERE
Filename: dscr-formula-rent-divided-by-pitia-utah.webp
ALT: DSCR formula rent divided by PITIA Utah
Caption: The basic residential DSCR formula divides qualifying monthly rental income by the applicable monthly property obligation.
DSCR Loan Calculator Utah PITIA Worksheet
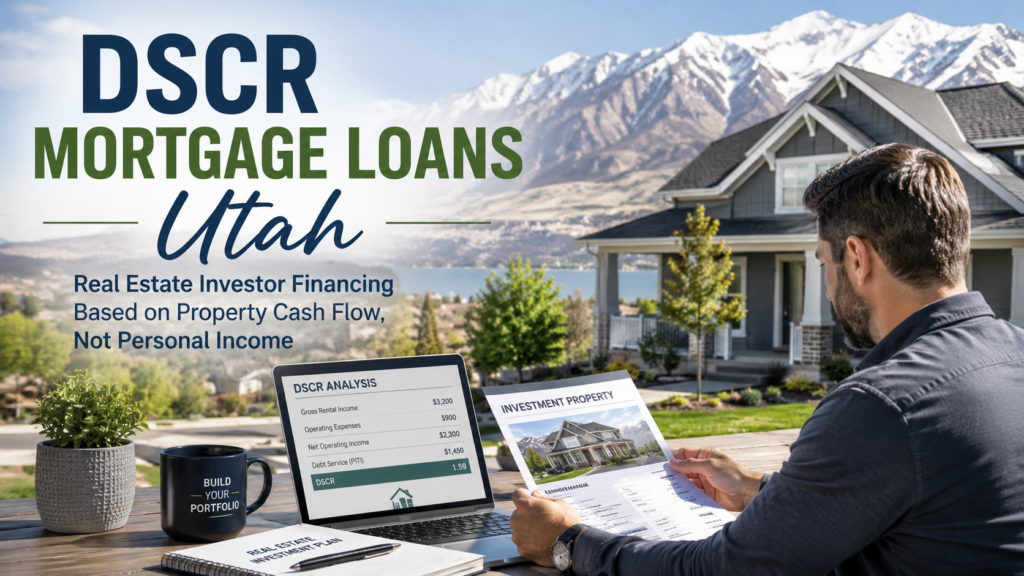
Use this simple DSCR loan calculator Utah worksheet to estimate the ratio before requesting a loan quote.
| DSCR Calculator Input | Your Property |
|---|---|
| Qualifying monthly rent | $________ |
| Monthly principal and interest | $________ |
| Monthly property taxes | $________ |
| Monthly insurance | $________ |
| Monthly HOA dues | $________ |
| Other applicable housing expense | $________ |
| Estimated PITIA | $________ |
| Estimated DSCR | ________ |
Step 1: Calculate PITIA
Add the applicable monthly property expenses.
Principal + Interest + Taxes + Insurance + Association Dues = PITIA
Step 2: Calculate DSCR
Divide the qualifying monthly rent by PITIA.
Qualifying Rent ÷ PITIA = Estimated DSCR
Step 3: Compare the Result With the Loan Program
The calculation gives you an estimate.
It does not determine loan approval.
The lender decides which rental income and expenses qualify. The lender also sets its minimum DSCR, credit, LTV, reserve and property rules.
See DSCR Loan Requirements Utah for a deeper look at qualification rules.
What Is PITIA in a Utah DSCR Calculation?
PITIA is one of the most important parts of a DSCR loan calculator Utah investors use.
It commonly includes:
Principal
This is the part of the mortgage payment that reduces the loan balance.
Interest
This is the interest charged on the mortgage.
Taxes
Property taxes can increase the monthly housing expense and lower the DSCR.
Insurance
Applicable property insurance can also be included in the monthly expense.
Association Dues
HOA or association dues may be included when they apply to the property.
Other expenses or adjustments may apply under a specific lender's guidelines.
IMAGE — PLACE HERE
Filename: pitia-dscr-calculation-utah.webp
ALT: PITIA calculation for DSCR loans in Utah
Caption: Principal, interest, taxes, insurance and applicable HOA dues can affect the DSCR calculation for a Utah rental property.
Why Should You Use PITIA Instead of Only Principal and Interest?
Using only principal and interest can make a property's DSCR look stronger than it really is.
Here is a simple example.
| Monthly Expense | Amount |
|---|---|
| Principal and interest | $2,250 |
| Property taxes | $400 |
| Insurance | $175 |
| HOA dues | $175 |
| Total PITIA | $3,000 |
Assume qualifying rent is $3,600.
If you use only principal and interest:
$3,600 ÷ $2,250 = 1.60
If you use full PITIA:
$3,600 ÷ $3,000 = 1.20
That is a large difference.
For a useful estimate, enter all applicable property expenses.
What Does Your DSCR Number Mean?
The ratio shows how qualifying rent compares with the property obligation used in the calculation.
| Estimated DSCR | Simple Meaning |
|---|---|
| 0.75 | Rent equals 75% of the obligation |
| 0.90 | Rent equals 90% |
| 1.00 | Rent equals 100% |
| 1.10 | Rent equals 110% |
| 1.20 | Rent equals 120% |
| 1.25 | Rent equals 125% |
| 1.50 | Rent equals 150% |
A higher ratio means there is more qualifying rent relative to the obligation being measured.
But DSCR is not the same as actual investment cash flow.
Your property may also have repairs, maintenance, vacancy, management fees, utilities and other expenses.
DSCR Loan Calculator Utah Break-Even Formula
For the simplified rent-to-PITIA calculation, a 1.00 DSCR is the mathematical break-even ratio.
At 1.00:
Qualifying Rent = PITIA
Suppose monthly rent is $2,900.
PITIA is also $2,900.
$2,900 ÷ $2,900 = 1.00
The property has a 1.00 DSCR.
This does not mean the investment itself has zero profit or loss.
It only means the qualifying rent equals the monthly obligation used in the DSCR calculation.
IMAGE — PLACE HERE
Filename: dscr-break-even-calculator-utah.webp
ALT: DSCR break even calculator Utah rental property
Caption: A 1.00 DSCR is the mathematical point where qualifying rent equals the monthly property obligation used in the calculation.
How Much Rent Do I Need for a 1.00 DSCR?
You can reverse the DSCR formula.
Use:
Required Rent = PITIA × Target DSCR
Assume PITIA is $3,000.
For a 1.00 DSCR:
$3,000 × 1.00 = $3,000
Required qualifying rent is $3,000 per month.
How Much Rent Do I Need for a 1.25 DSCR?
Use the same formula:
PITIA × Target DSCR = Required Rent
Suppose PITIA is $3,000.
$3,000 × 1.25 = $3,750
The property needs $3,750 in qualifying monthly rent to produce a 1.25 DSCR under these assumptions.
Here is another example.
PITIA: $4,000
Target DSCR: 1.25
$4,000 × 1.25 = $5,000
Required qualifying rent: $5,000
IMAGE — PLACE HERE
Filename: rent-needed-for-1-25-dscr-utah.webp
ALT: rent needed for 1.25 DSCR Utah
Caption: Multiply PITIA by the target DSCR to estimate how much qualifying monthly rent is needed for a selected ratio.
What Is the Maximum PITIA My Rent Can Support?
You can also solve the formula backward.
Use:
Maximum PITIA = Qualifying Rent ÷ Target DSCR
Assume qualifying monthly rent is $4,000.
Your target DSCR is 1.25.
$4,000 ÷ 1.25 = $3,200
The estimated maximum PITIA is $3,200 at a 1.25 target.
At a 1.00 target:
$4,000 ÷ 1.00 = $4,000
This formula is useful when comparing loan options.
DSCR Loan Calculator Utah Example: $2,900 Rent and $3,223.75 PITIA
Let's use a real-world style example.
Qualifying rent: $2,900
PITIA: $3,223.75
Calculation:
$2,900 ÷ $3,223.75 = approximately 0.90
Estimated DSCR: 0.90
The qualifying rent covers about 90% of the PITIA in this example.
A ratio below 1.00 may not meet the rules of many standard DSCR programs. However, specialized programs can differ.
Learn more about those scenarios on No-Ratio DSCR Loans Utah.
DSCR Example: $2,900 Rent and $2,900 PITIA
Qualifying rent: $2,900
PITIA: $2,900
Calculation:
$2,900 ÷ $2,900 = 1.00
Estimated DSCR: 1.00
The rent equals the PITIA.
DSCR Example: $2,900 Rent and $3,850 PITIA
Qualifying rent: $2,900
PITIA: $3,850
Calculation:
$2,900 ÷ $3,850 = approximately 0.75
Estimated DSCR: 0.75
The rent covers about 75% of the PITIA in this example.
DSCR Example: $2,900 Rent and $3,464.28 PITIA
Qualifying rent: $2,900
PITIA: $3,464.28
Calculation:
$2,900 ÷ $3,464.28 = approximately 0.84
Estimated DSCR: 0.84
The rent equals about 84% of the PITIA.
How Does a Larger Down Payment Affect DSCR?
A larger down payment usually means a smaller loan amount.
A smaller loan may have a lower principal-and-interest payment.
That can lower PITIA.
When rent stays the same, lower PITIA can increase the DSCR.
Consider this example.
Qualifying rent is $4,000.
Scenario A
PITIA: $3,500
$4,000 ÷ $3,500 = 1.14
Scenario B
PITIA: $3,200
$4,000 ÷ $3,200 = 1.25
The rent did not change.
The monthly property obligation did.
Learn more at DSCR Loan Down Payment Utah and DSCR Loan LTV Utah.
How Do Interest Rates Affect a DSCR Loan Calculator Utah Result?
Interest rates can affect the principal-and-interest payment.
If the payment goes up and rent stays the same, DSCR can fall.
For example:
Qualifying rent: $4,000
PITIA: $3,100
$4,000 ÷ $3,100 = 1.29
Now assume PITIA rises to $3,350.
$4,000 ÷ $3,350 = 1.19
The rent stayed at $4,000.
The higher payment lowered the estimated DSCR.
This is why rate, loan amount and DSCR should be reviewed together.
See DSCR Loan Rates Utah for pricing factors, points, credit, LTV and loan structure.
Can an Interest-Only Loan Improve the DSCR?
It can change the payment used in the calculation.
An interest-only structure may have a lower scheduled payment during the interest-only period than a fully amortizing loan.
A lower applicable payment may improve the calculated DSCR.
But interest-only financing has tradeoffs.
The principal balance generally does not decline through scheduled principal payments during the interest-only period. The payment may also change when that period ends.
See Interest-Only DSCR Loans Utah.
How Do Utah Property Taxes Affect DSCR?
Property taxes can change the result because they are commonly part of PITIA.
Assume two properties each generate $4,000 in qualifying monthly rent.
Property A
Principal and interest: $2,500
Taxes: $250
Insurance: $150
PITIA: $2,900
$4,000 ÷ $2,900 = 1.38
Property B
Principal and interest: $2,500
Taxes: $500
Insurance: $150
PITIA: $3,150
$4,000 ÷ $3,150 = 1.27
The rent is the same.
The higher property expense produces a lower DSCR.
How Does Insurance Affect DSCR?
Insurance can increase PITIA.
A higher PITIA can reduce the ratio when rent stays the same.
Before using a DSCR loan calculator Utah estimate, try to get reasonable figures for:
- Property taxes
- Property insurance
- HOA dues
- Loan payment
- Qualifying rental income
Better inputs produce a more useful estimate.
How Do HOA Dues Affect DSCR?
HOA dues can have a large impact on some Utah investment properties.
Assume rent is $3,500.
Principal, interest, taxes and insurance total $2,600.
Without an HOA:
$3,500 ÷ $2,600 = 1.35
Now add $300 in monthly HOA dues.
PITIA becomes $2,900.
$3,500 ÷ $2,900 = 1.21
That is a meaningful change.
This can be especially important when evaluating condos or planned communities.
What Rental Income Should I Enter Into a DSCR Loan Calculator Utah?
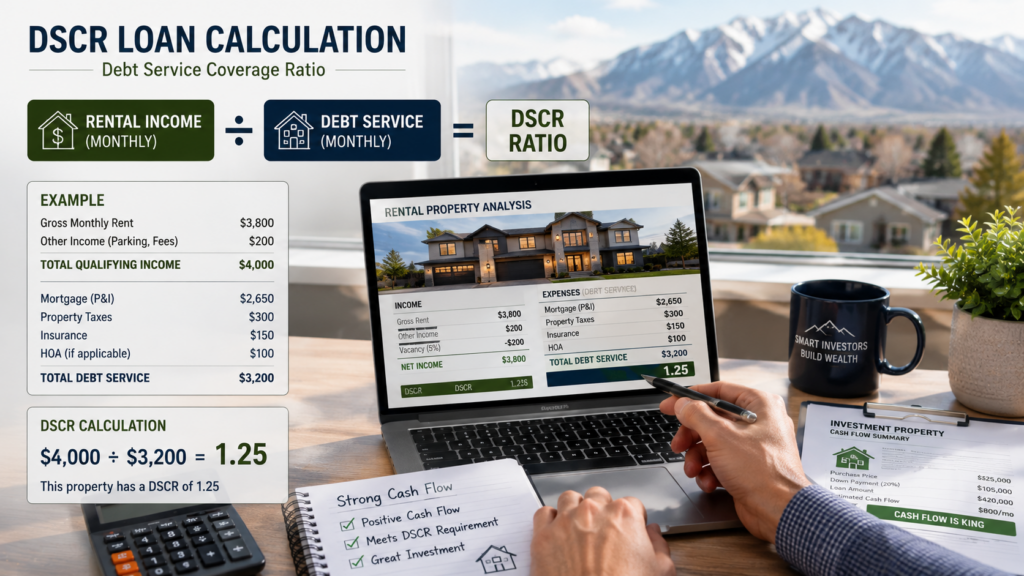
Use a reasonable and supportable rental figure.
Do not assume the rent you hope to receive will automatically be the rent the lender accepts.
Depending on the lender and property, rental income may be supported by items such as:
- An existing lease
- Appraiser-supported market rent
- A rent schedule
- Short-term rental documentation
- Other approved rental evidence
Rules vary by program.
For short-term rentals, see DSCR Loans for Short-Term Rentals Utah.
Is DSCR the Same as Rental Property Cash Flow?
No.
This is an important difference.
DSCR measures qualifying rental income against the property obligation defined by the lender.
Actual investment cash flow can include many more expenses.
Examples include:
- Vacancy
- Repairs
- Maintenance
- Property management
- Utilities
- Landscaping
- Capital improvements
- Furnishings
- Turnover costs
- Leasing expenses
A property can have a certain mortgage DSCR and still produce very different real-world cash flow.
DSCR vs. Debt-to-Income Ratio
DSCR and DTI are different calculations.
DSCR looks at the property's qualifying rental income compared with its applicable debt obligation.
DTI generally looks at a borrower's qualifying personal income compared with qualifying personal debts.
DSCR financing can therefore be useful for real estate investors whose personal tax returns do not tell the full story of their rental-property strategy.
Other underwriting rules still apply.
These may include credit, assets, reserves, LTV and property eligibility.
Can I Use a DSCR Loan Calculator Utah Before Making an Offer?
Yes.
This is one of the best times to run an estimate.
Start with:
- Purchase price
- Down payment
- Estimated loan amount
- Estimated interest rate
- Principal and interest
- Property taxes
- Insurance
- HOA dues
- Supportable monthly rent
Then calculate PITIA.
Finally, divide the qualifying rent by PITIA.
This gives you a starting point before you make an offer.
DSCR Break-Even Rent Table
Assume PITIA is $3,200 per month.
| Target DSCR | Required Monthly Rent |
|---|---|
| 0.75 | $2,400 |
| 0.80 | $2,560 |
| 0.90 | $2,880 |
| 1.00 | $3,200 |
| 1.10 | $3,520 |
| 1.20 | $3,840 |
| 1.25 | $4,000 |
| 1.50 | $4,800 |
These are mathematical examples.
They are not lender approval thresholds.
Minimum DSCR requirements can vary by lender and loan program.
Compare Three Utah DSCR Loan Scenarios
Suppose a Utah rental property produces $4,200 in qualifying monthly rent.
Loan Scenario 1
PITIA: $3,600
$4,200 ÷ $3,600 = 1.17
Loan Scenario 2
PITIA: $3,400
$4,200 ÷ $3,400 = 1.24
Loan Scenario 3
PITIA: $3,200
$4,200 ÷ $3,200 = 1.31
The property is the same.
The rent is the same.
The financing changes.
So does the DSCR.
IMAGE — PLACE HERE
Filename: dscr-loan-scenario-comparison-utah.webp
ALT: Utah DSCR loan scenario comparison
Caption: Compare how different monthly property obligations can change DSCR while the property's qualifying rental income stays the same.
Using a DSCR Loan Calculator Utah for Salt Lake City Rentals
Salt Lake City investors may use DSCR calculations when reviewing single-family homes, condos, townhomes and eligible 2–4 unit rental properties.
Property taxes, insurance, HOA dues and rent can vary from one property to another.
Calculate each property on its own numbers.
Visit DSCR Loans Salt Lake City Utah for local financing information.
Using a DSCR Calculator for Park City Investment Properties
Park City properties can have very different financing profiles.
Property values may be higher. HOA dues can also be significant for some condos and resort properties.
Short-term rental income can add another layer to the analysis.
A property with strong gross rent can still have a lower DSCR if its monthly housing expense is high.
See DSCR Loans Park City Utah.
Using a DSCR Calculator for St. George Rental Properties
St. George and Washington County investors may evaluate long-term rentals, newer investment homes and eligible short-term rentals.
Use the property's actual estimated taxes, insurance, HOA dues and financing structure.
See DSCR Loans St. George Utah.
How Can I Improve My DSCR?
There are two basic ways to improve the mathematical ratio.
Increase Qualifying Rent
A higher qualifying rent increases the top number in the formula.
Reduce the Monthly Property Obligation
A lower PITIA reduces the bottom number.
Depending on the property and loan, investors may compare:
- Larger down payments
- Smaller loan amounts
- Different loan structures
- Lower HOA properties
- Different financing options
- Properties with stronger supportable rents
The lender decides which figures qualify.
What If My DSCR Is Below 1.00?
A DSCR below 1.00 means qualifying rent is less than the monthly obligation used in the calculation.
That does not automatically answer whether financing is available.
Programs differ.
Some lenders may require a minimum ratio. Other specialized programs may allow lower ratios or no-ratio structures.
Factors can include:
- Credit score
- LTV
- Loan amount
- Property type
- Reserves
- Transaction type
- Purchase or refinance
- Cash-out amount
- Prepayment terms
Visit No-Ratio DSCR Loans Utah for more information.
Does Credit Score Change the DSCR Formula?
No.
Credit score does not change this formula:
Rent ÷ PITIA
But credit may affect available pricing, LTV and loan programs.
Those factors can change the loan structure.
The loan structure can change the payment.
The payment can change DSCR.
See DSCR Loan Credit Score Utah.
Does LTV Affect the DSCR Loan Calculator Utah Result?
LTV does not change the formula itself.
It can still affect the result.
Here is the connection:
Down Payment → Loan Amount → Mortgage Payment → PITIA → DSCR
A larger loan may produce a larger payment.
A larger payment may increase PITIA.
If rent stays the same, the DSCR can fall.
Read DSCR Loan LTV Utah for more information.
How Does a DSCR Cash-Out Refinance Affect the Calculation?
A cash-out refinance can increase the new loan balance.
That may increase the payment.
If PITIA rises while rent stays the same, DSCR can fall.
Example:
Qualifying rent: $4,000
Original PITIA: $2,900
$4,000 ÷ $2,900 = 1.38
New PITIA after a hypothetical cash-out refinance: $3,400
$4,000 ÷ $3,400 = 1.18
Investors should calculate the proposed new DSCR before deciding how much equity to access.
See DSCR Cash-Out Refinance Utah.
DSCR Loan Calculator Utah FAQ
How do you calculate DSCR for a Utah rental property?
Divide the qualifying monthly rental income by the monthly property obligation required by the lender. Many residential DSCR programs use PITIA as part of this calculation.
What is the basic DSCR formula?
The simplified formula is:
DSCR = Qualifying Monthly Rent ÷ Monthly PITIA
The exact lender calculation can vary.
What does a 1.00 DSCR mean?
A 1.00 DSCR means qualifying rent equals the monthly property obligation used in the calculation.
For example:
$3,000 ÷ $3,000 = 1.00
What does a 1.25 DSCR mean?
A 1.25 DSCR means qualifying rent equals 125% of the property obligation being measured.
Example:
$4,000 ÷ $3,200 = 1.25
How much rent do I need for a 1.25 DSCR?
Multiply PITIA by 1.25.
If PITIA is $3,200:
$3,200 × 1.25 = $4,000
The property would need $4,000 in qualifying monthly rent under those assumptions.
How much PITIA can $3,000 in rent support at a 1.25 DSCR?
Divide rent by the target ratio:
$3,000 ÷ 1.25 = $2,400
The maximum PITIA would be $2,400 for a mathematical 1.25 ratio.
Do HOA dues count in a DSCR calculation?
They may. Applicable association dues are commonly included in the property obligation used by residential DSCR programs. Check the specific lender's rules.
Do property taxes count in DSCR?
Property taxes are commonly part of PITIA and can affect the calculated ratio.
Does homeowners insurance count in DSCR?
Applicable property insurance is commonly included in the housing expense used for the calculation.
Can I get a DSCR loan below 1.00?
Some specialized programs may consider lower-DSCR or no-ratio scenarios. LTV, credit, pricing and other rules can be different.
Is DSCR the same as rental cash flow?
No. Mortgage DSCR does not necessarily include every operating expense associated with owning a rental property.
Can I use this calculator for a Utah Airbnb or short-term rental?
You can estimate the mathematical ratio. However, lenders can have different rules for qualifying short-term-rental income. Review the applicable program before relying on projected rental income.
Utah DSCR Loan Resource Center
Use the DSCR loan calculator Utah guide together with the rest of the UtahLowRate DSCR resource cluster:
- DSCR Mortgage Loans Utah — statewide DSCR hub
- DSCR Loan Requirements Utah — qualification and underwriting
- DSCR Loan Rates Utah — pricing, points and rate factors
- DSCR Loan Calculator Utah — formula, PITIA and break-even calculations
- DSCR Loan FAQ Utah — common investor questions
- DSCR Cash-Out Refinance Utah — investment-property equity
- No-Ratio DSCR Loans Utah — below-1.00 and no-ratio programs
- DSCR Loans for Short-Term Rentals Utah — short-term rental financing
- DSCR Loan Credit Score Utah — credit requirements and pricing
- DSCR Loan Down Payment Utah — down payment and equity
- DSCR Loan LTV Utah — loan-to-value considerations
- Interest-Only DSCR Loans Utah — interest-only payment structures
- DSCR Prepayment Penalty Utah — prepayment structures
- DSCR Loans Salt Lake City Utah — Salt Lake City investors
- DSCR Loans Park City Utah — Park City and Summit County
- DSCR Loans St. George Utah — St. George and Southern Utah
Get Your Utah DSCR Scenario Reviewed
A DSCR loan calculator Utah investors use online is a good starting point.
But an online calculation cannot determine final loan approval.
For a DSCR scenario review, provide:
- Property address
- Purchase price or estimated value
- Requested loan amount
- Current or expected monthly rent
- Property taxes
- Insurance
- HOA dues
- Credit-score range
- Purchase, refinance or cash-out transaction
Daniel Paris
UtahLowRate.com
Utah Mortgage Broker
NMLS #243976-3138
801-604-4949
CTA: Check My DSCR Scenario
DSCR Calculator Disclosure
This DSCR loan calculator Utah guide is for general education and illustration.
The calculations are estimates.
They are not a loan approval, pre-approval, rate quote, commitment to lend or guarantee of eligibility.
The lender determines qualifying rental income, applicable property expenses, DSCR, credit requirements, LTV, reserves, pricing and property eligibility.
Loan programs, guidelines, rates and availability can change.
Related guides: Utah DSCR loan guide · DSCR loan requirements · DSCR loan rates · DSCR questions and answers ·

