
Content updated: September 29, 2026
DSCR loans Park City Utah investors use can provide an alternative way to finance qualifying rental properties without relying primarily on traditional personal-income calculations. Instead, a Debt Service Coverage Ratio loan focuses heavily on the rental income of the investment property compared with its qualifying monthly housing obligation.
For investors buying or refinancing properties in Park City, Deer Valley, Old Town, Canyons Village, Prospector, Kimball Junction and surrounding Summit County communities, DSCR financing can be particularly useful when the investment property's cash flow tells a clearer story than the borrower's personal tax returns.
Check My DSCR Scenario or call 801-604-4949.
Daniel Paris with UtahLowRate.com helps Utah real estate investors compare DSCR mortgage programs for eligible rental properties throughout Park City and the Wasatch Back.
Quick Answer: A Park City DSCR loan may allow a qualified real estate investor to finance an investment property using its qualifying rental income as a central part of underwriting rather than qualifying primarily through W-2 income, tax returns and traditional debt-to-income calculations. Credit, LTV, reserves, property type, rental documentation and lender guidelines still apply.
Park City DSCR Loan Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | General DSCR Guideline |
|---|---|
| Primary use | Investment properties |
| Main qualification factor | Property rental cash flow |
| Personal tax returns | Often not used for DSCR income qualification |
| Traditional DTI | Generally not the primary qualification method |
| Purchase | Available through qualifying programs |
| Rate-and-term refinance | Available through qualifying programs |
| Cash-out refinance | Available through qualifying programs |
| Long-term rentals | Common DSCR property type |
| Short-term rentals | May qualify with certain lenders |
| LLC ownership | May be available |
| Interest-only | Select programs |
| Higher-balance properties | Select jumbo/non-QM programs |
| Credit requirements | Lender and program specific |
| Reserves | Frequently required |
| Prepayment provisions | May apply |
| Final approval | Subject to underwriting |
Program availability, rates, LTV limits, DSCR requirements, credit requirements, reserves, prepayment provisions and documentation vary by lender and investor.
What Is a DSCR Loan in Park City?
A Debt Service Coverage Ratio mortgage is generally a business-purpose investment-property loan.
Instead of primarily asking how much personal income the investor earns, DSCR underwriting focuses on whether the property's qualifying rental income adequately supports the housing expense used by the lender.
The basic calculation is:
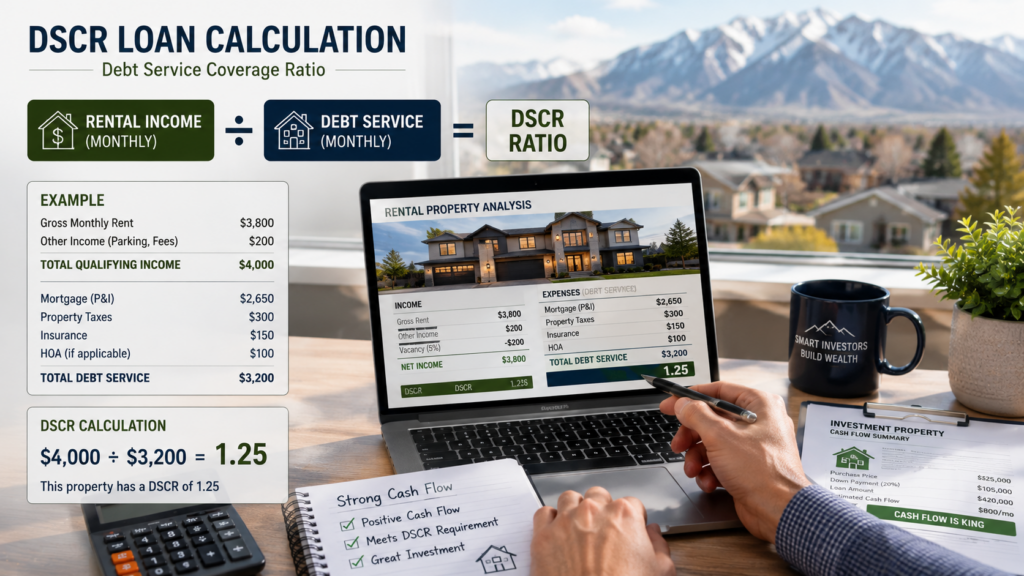
DSCR = Qualifying Monthly Rental Income ÷ Qualifying Monthly Property Debt Obligation
For a broader explanation of these loans throughout Utah, visit the DSCR Mortgage Loans Utah guide.
How Is DSCR Calculated on a Park City Rental Property?
Consider a simplified example.
Suppose a qualifying Park City rental property has:
Qualifying monthly rent: $8,000
Qualifying monthly housing obligation: $6,400
The calculation is:
$8,000 ÷ $6,400 = 1.25 DSCR
A 1.25 ratio means qualifying rent equals approximately 125% of the housing obligation included in that calculation.
If qualifying rent were $6,400 and the applicable housing obligation were also $6,400:
$6,400 ÷ $6,400 = 1.00 DSCR
The property is at the simplified break-even point.
Actual lender calculations can differ. Investors should not assume that every dollar of projected vacation-rental revenue or gross rental income will be accepted for qualification.
Use the DSCR Loan Calculator Utah to understand the calculation in greater detail.
Why Park City DSCR Loans Require a Local Investment Analysis
Park City is not a typical rental-property market.
Investors can encounter luxury condominiums, ski properties, resort-area units, single-family rentals, properties with substantial HOA dues and homes designed around seasonal or nightly rental demand.
Those characteristics can affect the financing analysis.
A DSCR calculation may be influenced by:
- Qualifying rental income
- Principal and interest
- Property taxes
- Homeowners insurance
- HOA dues when applicable
- Credit score
- Loan-to-value ratio
- Property type
- Loan amount
- Purchase versus refinance
- Interest-only versus amortizing payments
- Long-term versus short-term rental use
For a detailed underwriting checklist, review DSCR Loan Requirements Utah.
DSCR Loans Park City Utah for Short-Term Rentals
Short-term rentals can be an important part of the Park City investment market, but financing eligibility and legal rental eligibility are two separate questions.
Certain DSCR lenders may finance qualifying short-term or vacation-rental properties. The method used to establish qualifying rental income varies by lender.
Investors should separately verify whether the property can legally operate as a nightly rental.
Park City defines a nightly rental as renting a dwelling unit or portion of one for less than 30 days, and the city states that properties offered for lodging for periods under 30 days require a Nightly Rental License when the use is allowed by zoning.
Local restrictions can also be property-specific. For example, Park City has adopted restrictions prohibiting nightly rentals in certain residential subdivisions.
Before purchasing a property based on expected vacation-rental revenue, independently verify:
- Park City or Summit County zoning
- Nightly-rental eligibility
- Business-license requirements
- HOA restrictions
- Condominium declarations
- Property management rules
- Rental licensing
- Applicable tax requirements
Mortgage approval does not establish that a property is legally permitted to operate as a short-term rental.
For a deeper financing discussion, visit DSCR Loans for Short-Term Rentals Utah.
Park City Neighborhoods and Areas Where Investors May Consider DSCR Financing
DSCR financing may be considered for eligible investment properties throughout the greater Park City area, including properties in or around:
Old Town — Condominiums, homes and properties near historic Main Street and Park City Mountain.
Deer Valley — Luxury resort properties can involve larger loan balances, HOA expenses and specialized rental considerations.
Canyons Village — Condominium and resort-oriented properties may require careful analysis of property type, HOA structure and qualifying rental income.
Prospector — Investors may encounter condominiums and other rental-property opportunities.
Kimball Junction — Properties around the Snyderville Basin can have different characteristics from properties inside Park City municipal boundaries.
Promontory and surrounding luxury communities — Higher property values may require comparing DSCR financing with jumbo or specialized investment-property financing.
The best program depends on the individual property rather than simply its Park City address.
Park City DSCR Loan Requirements
There is no universal set of requirements that applies to every DSCR lender.
Underwriters can evaluate several factors together.
DSCR Ratio
A stronger ratio generally indicates more rental-income coverage relative to the property's qualifying housing obligation.
Some programs may accept ratios around or below 1.00, while others may require stronger coverage.
Read about lower-ratio scenarios at No-Ratio DSCR Loans Utah.
Credit Score
Credit can affect eligibility, interest rate, points, maximum LTV and other program terms.
A stronger DSCR does not automatically eliminate credit requirements.
See DSCR Loan Credit Score Utah.
Down Payment
Required equity depends on the lender, credit profile, DSCR, property type and transaction.
Learn how these factors interact in the DSCR Loan Down Payment Utah guide.
Loan-to-Value
Maximum LTV can differ between purchases, rate-and-term refinances and cash-out transactions.
See DSCR Loan LTV Utah.
Reserves
Many lenders require eligible assets remaining after closing.
The required amount can depend on the loan balance, number of financed properties, credit, DSCR and overall transaction.
HOA Dues Can Matter on Park City DSCR Loans
HOA expenses deserve particular attention when analyzing Park City condominiums and resort properties.
A property can generate substantial gross rent but still produce a weaker DSCR when the applicable housing obligation is high.
For example, investors should evaluate the combined effect of:
- Mortgage principal and interest
- Property taxes
- Insurance
- HOA assessments
- Other expenses included under the lender's DSCR methodology
Do not evaluate a potential Park City investment based solely on gross rental revenue.
DSCR Purchase Loans in Park City
A DSCR purchase loan can be useful when acquiring a qualifying Park City investment property.
Before making an offer, consider estimating:
- Purchase price
- Expected loan amount
- Down payment
- Qualifying market or lease rent
- Taxes
- Insurance
- HOA dues
- Estimated mortgage payment
- Resulting DSCR
- Required reserves
See the complete DSCR Purchase Loans Utah guide before structuring a purchase.
Refinancing a Park City DSCR Property
Investors with existing Park City rental properties may also consider DSCR refinancing.
A rate-and-term refinance may be used to restructure existing financing, subject to lender guidelines.
Read DSCR Refinance Loans Utah for the statewide refinance process.
DSCR Cash-Out Refinance Park City
A qualifying investor may be able to access equity from an existing rental property through a DSCR cash-out refinance.
Maximum proceeds can depend on:
- Property value
- Current mortgage balance
- Maximum permitted LTV
- Credit
- DSCR
- Property type
- Ownership history
- Seasoning
- Lender guidelines
Park City's higher-value properties can make the interaction between appraised value and maximum LTV particularly important.
Review DSCR Cash-Out Refinance Utah for more information.
Interest-Only DSCR Loans Park City
Some investors consider interest-only financing because the scheduled payment during the interest-only period may be lower than the payment on a fully amortizing structure.
A lower qualifying payment can affect the DSCR calculation when permitted by the selected program.
However, interest-only financing has important tradeoffs. Principal is generally not reduced through the scheduled interest-only payment during that period, and future payments can increase.
Compare the mechanics at Interest-Only DSCR Loans Utah.
Buying a Park City Rental Property Through an LLC
Certain DSCR programs permit eligible borrowers to close in an LLC or other approved entity.
Requirements can include organizational documents and personal guarantees.
Entity vesting does not automatically eliminate borrower underwriting requirements, and investors should consult qualified legal and tax professionals about the consequences of holding real estate through an entity.
Park City DSCR Loan Rates
There is no single Park City DSCR mortgage rate.
Pricing can be influenced by:
- Credit score
- DSCR
- LTV
- Loan amount
- Property type
- Purchase or refinance
- Cash-out
- Interest-only structure
- Points
- Prepayment provisions
- Market conditions
- Lender and investor
The lowest advertised rate is not automatically the best loan.
Compare rate, APR when applicable, lender fees, points, prepayment provisions and the overall financing strategy.
For a detailed explanation, visit DSCR Loan Rates Utah.
DSCR vs Conventional Investment Loans in Park City
DSCR and conventional investment-property mortgages qualify borrowers differently.
| Feature | DSCR Loan | Conventional Investment Loan |
|---|---|---|
| Main income focus | Property rental cash flow | Borrower qualifying income |
| Traditional DTI | Usually not primary method | Generally required |
| Tax-return income | Often not used for DSCR calculation | Commonly required |
| LLC closing | May be available | More restrictive |
| Property use | Investment | Investment |
| Short-term rental | Program specific | Program specific |
| Prepayment provision | May apply | Typically different structure |
Investors who qualify for both should compare the complete economics rather than assuming one option is automatically better.
See DSCR vs Conventional Investment Loan Utah.
How to Get a DSCR Loan in Park City Utah
Step 1 — Identify the Property
Provide the property address, purchase price or estimated value and intended rental strategy.
Step 2 — Determine Qualifying Rent
Review the lease, market-rent documentation, appraisal information or other rental evidence permitted by the lender.
Step 3 — Calculate DSCR
Compare qualifying rent with the housing obligation required under the selected program.
Step 4 — Review Credit and LTV
Credit and equity can materially affect available programs and pricing.
Step 5 — Review the Property
Park City condominiums, resort properties, HOA structures and short-term rentals can require additional analysis.
Step 6 — Compare Wholesale DSCR Programs
Compare available lenders based on the complete transaction rather than a single advertised rate.
Step 7 — Complete Underwriting
Final approval can include appraisal, title, assets, entity documents, insurance, property review and other lender requirements.
Frequently Asked Questions About DSCR Loans Park City Utah
Can I get a DSCR loan for a Park City vacation rental?
Potentially. Certain lenders permit qualifying short-term or vacation-rental properties. Mortgage eligibility does not establish legal short-term-rental eligibility, so zoning, licensing and HOA rules should be verified separately.
Do DSCR loans require personal tax returns?
DSCR loans generally focus primarily on property rental cash flow rather than traditional personal-income qualification. Exact documentation requirements vary by lender.
Can I finance a Deer Valley rental property with a DSCR loan?
Potentially. Eligibility depends on the specific property, loan amount, appraisal, rental-income methodology, HOA structure, credit, LTV and lender requirements.
Can I get a DSCR loan below a 1.00 ratio?
Some programs may permit lower DSCR or no-ratio scenarios. Availability and terms vary substantially, so the actual transaction should be reviewed.
Can an LLC obtain a Park City DSCR loan?
Certain DSCR lenders permit eligible LLC vesting. Entity documentation and a personal guarantee may be required.
Can I cash out equity from a Park City rental?
Potentially. DSCR cash-out refinancing may be available subject to property value, LTV, DSCR, credit, seasoning and lender guidelines.
Are Park City DSCR rates higher than conventional mortgage rates?
Pricing is program specific. DSCR rates depend on market conditions and factors such as credit, DSCR, LTV, property type, loan amount, points and prepayment terms. Compare actual available loan structures.
Does UtahLowRate.com offer DSCR loans outside Park City?
Yes. UtahLowRate.com evaluates DSCR financing for eligible investment properties throughout Utah.
For additional questions, visit DSCR Loan FAQ Utah.
Explore the Utah DSCR Loan Cluster
Continue researching your investment-property financing options:
Core DSCR resources: DSCR Mortgage Loans Utah • DSCR Loan Requirements Utah • DSCR Loan Rates Utah • DSCR Loan Calculator Utah • DSCR Loan FAQ Utah
Qualification and structure: DSCR Loan Credit Score Utah • DSCR Loan Down Payment Utah • DSCR Loan LTV Utah • No-Ratio DSCR Loans Utah
Transactions: DSCR Purchase Loans Utah • DSCR Refinance Loans Utah • DSCR Cash-Out Refinance Utah
Specialized DSCR programs: DSCR Loans for Short-Term Rentals Utah • DSCR Loans for LLCs Utah • Interest-Only DSCR Loans Utah • DSCR vs Conventional Investment Loan Utah
Get a Park City DSCR Loan Quote
If you are purchasing, refinancing or accessing equity from a Park City rental property, start with the property numbers.
Daniel Paris can review the proposed value or purchase price, rental income, mortgage structure, credit profile and LTV to help identify available DSCR programs.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
Ask about: Park City DSCR loans • Deer Valley investment-property loans • short-term-rental financing • DSCR cash-out refinancing • interest-only DSCR loans • LLC DSCR loans • jumbo investment-property financing
Mortgage programs, interest rates, loan amounts, DSCR calculations, credit requirements, LTV limits, reserve requirements, prepayment provisions and property eligibility vary by lender and are subject to change. All loans are subject to borrower qualification, appraisal, property eligibility, complete underwriting and applicable lender/investor guidelines. Information is educational and does not constitute a commitment to lend.
Related guides: Utah DSCR loan guide · DSCR loan requirements · DSCR calculation guide · DSCR loan rates · DSCR questions and answers ·

