
Content updated: September 29, 2026
Rental Property Financing for Salt Lake City Real Estate Investors
DSCR loans in Salt Lake City can help real estate investors finance qualifying rental properties based primarily on the property's rental income rather than traditional personal employment income.
Check My DSCR Scenario or call 801-604-4949.
For investors buying, refinancing or accessing equity from rental properties in Salt Lake City and throughout Salt Lake County, a DSCR loan can provide an alternative to conventional investment-property financing.
Daniel Paris with UtahLowRate.com helps Utah real estate investors compare DSCR mortgage programs for eligible rental properties.
Call Daniel Paris: 801-604-4949
Get a DSCR Loan Quote | Explore Utah DSCR Loans
Quick Answer: A DSCR loan in Salt Lake City is an investment-property mortgage that generally qualifies the property using its eligible rental income compared with its qualifying monthly property debt obligation. Personal tax returns or W-2 income often are not used to establish qualifying income. Credit, LTV, reserves, property type, appraisal, rental income and lender guidelines still apply.
Key Facts About DSCR Loans in Salt Lake City
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Typical DSCR Approach |
|---|---|
| Primary purpose | Investment-property financing |
| Primary residence | Generally not eligible |
| Income approach | Qualifying rental income |
| Personal tax returns | Often not used to establish qualifying income |
| Purchase | Available under eligible programs |
| Rate-and-term refinance | Available |
| Cash-out refinance | Available under eligible programs |
| LLC ownership | May be permitted |
| Long-term rentals | May be eligible |
| Short-term rentals | May be eligible depending on program/property |
| Interest-only | Available through certain programs |
| DSCR below 1.00 | Some lender programs may allow it |
| Credit requirements | Vary by lender |
| LTV | Varies by credit, DSCR, transaction and property |
| Reserves | Investor-specific |
| Prepayment provisions | May apply |
Program availability, rates, LTV limits, credit requirements, DSCR calculations and underwriting guidelines vary by lender and can change.
What Is a DSCR Loan in Salt Lake City?
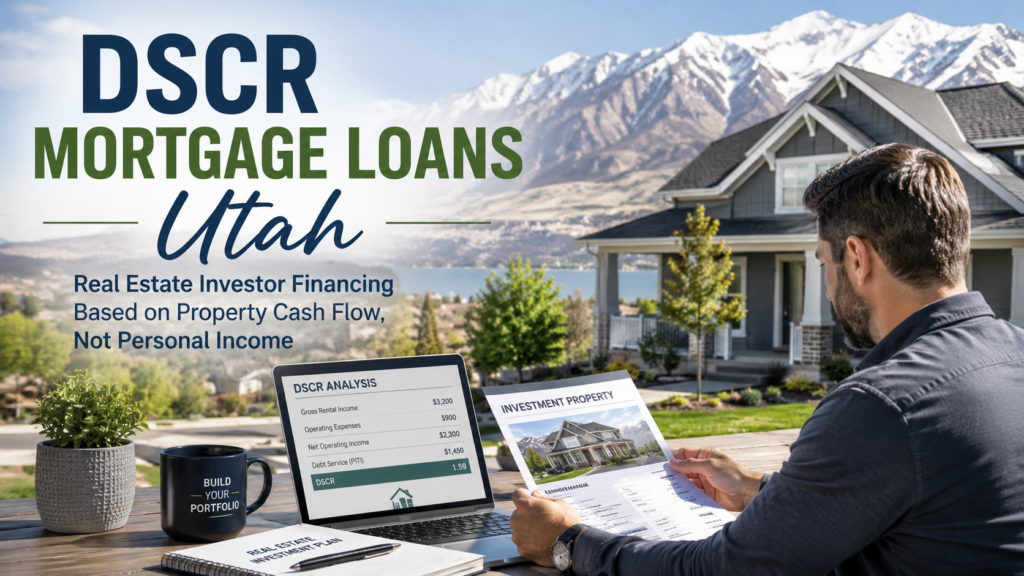
DSCR stands for Debt Service Coverage Ratio.
A DSCR mortgage is designed primarily for real estate investors. Instead of qualifying primarily from salary, W-2 income or self-employment tax returns, the lender evaluates the rental property's qualifying income relative to the debt obligation used in its DSCR calculation.
The basic concept is:
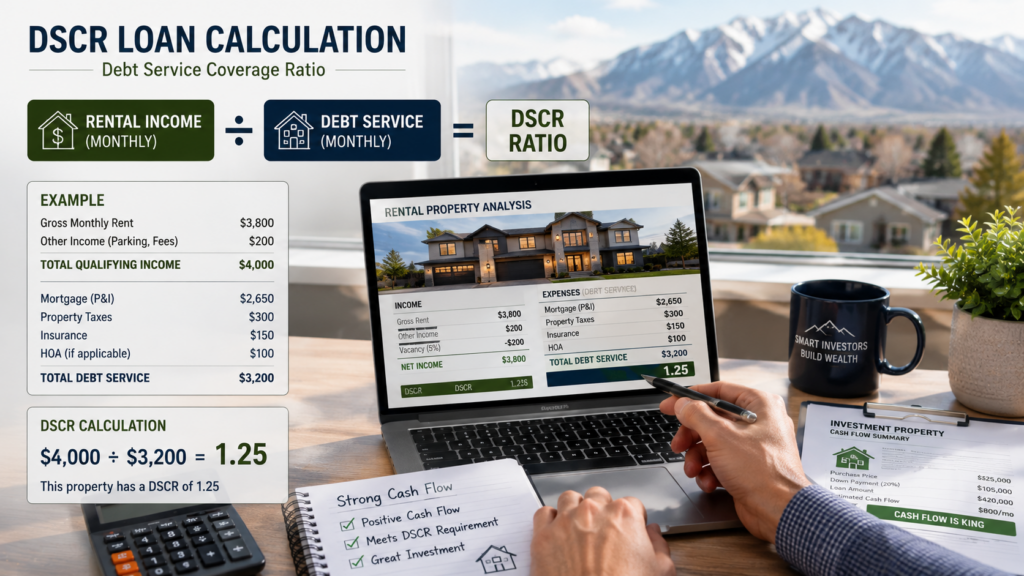
DSCR = Qualifying Monthly Rental Income ÷ Qualifying Monthly Property Debt Obligation
For example, assume a Salt Lake City rental property has:
- Qualifying monthly rent: $4,000
- Qualifying monthly property obligation: $3,200
The estimated DSCR would be:
$4,000 ÷ $3,200 = 1.25 DSCR
That means qualifying rent equals approximately 125% of the debt obligation used in this simplified example.
Want to test another property? Visit the DSCR Loan Calculator Utah.
What Does a 1.00 DSCR Mean?
A 1.00 DSCR generally means the qualifying rental income equals the qualifying property debt obligation used by the lender.
A ratio above 1.00 means qualifying rent exceeds that obligation.
For example:
- $3,000 rent ÷ $3,000 obligation = 1.00 DSCR
- $3,600 rent ÷ $3,000 obligation = 1.20 DSCR
- $3,900 rent ÷ $3,000 obligation = 1.30 DSCR
A higher DSCR can strengthen a transaction, but it does not automatically guarantee approval or the lowest available rate.
Learn more about qualification on the DSCR Loan Requirements Utah page.
Can You Get a Salt Lake City DSCR Loan Below 1.00?
Potentially.
Some lenders offer programs for properties with a DSCR below 1.00 or other reduced-DSCR structures. Availability can vary substantially.
Lower ratios may affect:
- Maximum LTV
- Required equity
- Interest rate
- Points
- Credit requirements
- Reserves
- Loan amount
- Property eligibility
- Other underwriting conditions
Investors with a property that does not reach a 1.00 DSCR should review No-Ratio DSCR Loans Utah rather than assuming the property cannot qualify.
DSCR Loans Salt Lake City: Why Investors Use Them
Salt Lake City investors can have substantial assets and rental-property cash flow while showing personal taxable income that does not fit conventional mortgage underwriting.
That can occur when an investor has:
- Multiple rental properties
- Depreciation
- Business deductions
- Schedule E properties
- LLC ownership
- Partnership interests
- Self-employment income
- Multiple business entities
- Complex federal tax returns
A qualifying DSCR program takes a different approach.
Instead of reconstructing every personal income source, the lender can focus primarily on whether the subject investment property generates sufficient qualifying rent for the proposed financing.
DSCR loans are still fully underwritten loans. Credit, assets, reserves, property eligibility, appraisal, title and other requirements can apply.
Do Salt Lake City DSCR Loans Require Tax Returns?
Many DSCR programs do not require personal tax returns to establish qualifying income because the underwriting is primarily based on the investment property's qualifying rental income.
That does not mean DSCR is a "no-document" mortgage.
Depending on the program, investors may still need documentation for:
- Identity
- Credit
- Assets
- Down payment
- Closing funds
- Reserves
- Entity formation
- Property ownership
- Insurance
- Appraisal
- Lease or rental income
- Title
- Other underwriting requirements
Investors buying a primary residence rather than a rental property should compare Bank Statement Loans Utah and other alternative-income programs.
Salt Lake City DSCR Purchase Loans
A DSCR mortgage may be used to acquire an eligible Salt Lake City investment property.
The lender may review:
- Purchase price
- Property value
- Expected or documented rent
- DSCR
- Credit profile
- Down payment
- LTV
- Reserves
- Property type
- Investor experience when required
- Entity structure
- Applicable loan terms
Visit DSCR Purchase Loans Utah for a more detailed purchase-financing guide.
How Much Down Payment Is Required?
There is no single down-payment requirement for every DSCR lender.
The available LTV can depend on the complete transaction, including:
- Credit score
- DSCR
- Property type
- Purchase price
- Loan amount
- Investor experience
- Loan purpose
- Rental characteristics
- Marketability
- Interest-only selection
- Other lender risk factors
A borrower with stronger credit, more equity and a stronger property DSCR may have access to different programs than an investor with higher leverage or a weaker ratio.
Compare DSCR Loan Down Payment Utah and DSCR Loan LTV Utah before deciding how much equity to put into a transaction.
What Credit Score Do You Need for a Salt Lake City DSCR Loan?
There is no universal minimum credit score that applies to every DSCR lender.
Credit can influence both eligibility and pricing.
A lower credit score may result in:
- Lower maximum LTV
- Higher rate
- Additional points
- Higher reserve requirements
- Fewer lender choices
- Additional underwriting restrictions
A stronger DSCR or additional equity may help certain transactions, but compensating factors do not override a lender's minimum program requirements.
See DSCR Loan Credit Score Utah for a deeper explanation.
DSCR Loan Rates in Salt Lake City
DSCR mortgage rates are generally risk-based.
Pricing can be affected by:
- Credit score
- DSCR
- LTV
- Loan amount
- Property type
- Purchase versus refinance
- Cash-out versus rate-and-term refinance
- Interest-only versus amortizing payment
- Prepayment structure
- Investor experience
- Rental type
- Current capital-market conditions
Because these variables interact, two Salt Lake City investment properties may receive different DSCR pricing even when their loan amounts are similar.
Visit DSCR Loan Rates Utah for a detailed explanation of DSCR pricing.
DSCR Refinance Loans in Salt Lake City
Investors who already own a Salt Lake City rental property may use DSCR financing to restructure existing investment-property debt.
Potential reasons include:
- Replacing short-term financing
- Refinancing an adjustable-rate loan
- Changing loan terms
- Moving into longer-term financing
- Changing an amortization structure
- Restructuring portfolio debt
See DSCR Refinance Loans Utah for more information.
DSCR Cash-Out Refinance Salt Lake City
A qualified investor may also be able to use a DSCR cash-out refinance to access equity from a Salt Lake City rental property.
Potential business or investment uses could include:
- Purchasing another rental
- Renovating an investment property
- Building liquidity
- Creating investment reserves
- Repositioning portfolio capital
- Paying eligible investment-related obligations
Maximum cash-out and LTV can depend on credit, property value, seasoning, DSCR and lender guidelines.
Review DSCR Cash-Out Refinance Utah for more details.
DSCR Loans for Salt Lake City LLCs
Some real estate investors prefer to hold investment property in a limited liability company.
Certain DSCR programs permit eligible LLC vesting, although entity and guarantor requirements vary.
The lender may request documents such as:
- Articles of Organization
- Operating Agreement
- EIN documentation
- Certificate of Good Standing when applicable
- Borrowing authorization
- Ownership information
- Personal guarantee from eligible members
LLC ownership can have legal and tax consequences. Investors should discuss those issues with qualified legal and tax professionals.
Read DSCR Loans for LLCs Utah before structuring the financing.
Interest-Only DSCR Loans in Salt Lake City
Some DSCR lenders offer interest-only payment structures.
During the interest-only period, the scheduled principal-and-interest payment can be lower than the payment on a fully amortizing loan with otherwise comparable terms.
That can potentially affect the property's DSCR calculation, depending on the lender's underwriting methodology.
However, interest-only financing also changes the long-term economics of the loan because scheduled principal reduction generally does not occur during the interest-only period.
Compare Interest-Only DSCR Loans Utah before choosing an IO structure.
DSCR Loans for Salt Lake City Short-Term Rentals
Certain DSCR programs may finance eligible short-term rental properties.
However, loan eligibility and legal short-term-rental eligibility are separate issues.
Before relying on projected short-term rental revenue, an investor should independently investigate:
- Salt Lake City requirements
- Applicable municipal rules
- Zoning
- Licensing
- HOA restrictions
- Condominium restrictions
- Property-specific restrictions
- Applicable county or state requirements
Lender methods for determining short-term-rental qualifying income can also vary.
See DSCR Loans for Short-Term Rentals Utah for the financing side of the analysis.
DSCR Loans Throughout Salt Lake City and Salt Lake County
Rental-property financing needs can vary considerably across the Salt Lake Valley.
UtahLowRate.com can help qualified investors evaluate properties in communities including:
Salt Lake City • Sugar House • The Avenues • Downtown Salt Lake City • Liberty Wells • Central City • Rose Park • Glendale • Millcreek • Holladay • Murray • Cottonwood Heights • Sandy • Draper • South Jordan • West Jordan • Midvale • Riverton • Herriman • Bluffdale
Location alone does not determine whether a DSCR loan will qualify.
The lender still evaluates the specific property, rental-income documentation, value, DSCR, credit, LTV and complete transaction.
DSCR Loan vs Conventional Investment Loan
DSCR and conventional investment-property mortgages solve different qualification problems.
| Feature | DSCR Loan | Conventional Investment Loan |
|---|---|---|
| Main income focus | Property rental cash flow | Borrower qualifying income |
| Personal DTI | Often not primary qualification method | Generally important |
| Tax-return income | Often not used for DSCR qualification | May be required |
| Rental-property purpose | Core use | Available |
| LLC closing | Often possible depending on program | More restrictive |
| Pricing | Non-QM/investor pricing | Agency/conventional pricing when eligible |
| Guidelines | Lender/investor specific | Agency/investor requirements |
Investors who qualify conventionally should not automatically assume DSCR financing is better.
Compare both structures when possible.
See DSCR vs Conventional Investment Loan Utah for a detailed comparison.
How to Get a DSCR Loan in Salt Lake City
Step 1: Provide the Property Information
Start with the Salt Lake City property address, estimated purchase price or value and transaction type.
Step 2: Determine Qualifying Rent
Review the existing lease, proposed rent, appraisal rent schedule or other rental-income documentation permitted by the selected lender.
Step 3: Estimate the DSCR
Compare qualifying monthly rent with the debt obligation required by that lender.
Step 4: Review Credit and Equity
Credit and LTV can materially change the available programs and pricing.
Step 5: Compare Lenders
Compare more than the rate.
Review:
- Interest rate
- APR when applicable
- Points
- Lender fees
- DSCR requirement
- Maximum LTV
- Reserves
- Prepayment provisions
- Interest-only options
- Entity requirements
- Cash-out restrictions
- Property eligibility
Step 6: Complete Appraisal and Underwriting
The lender evaluates the complete transaction under its applicable program requirements.
Step 7: Close the Investment Property Loan
After final underwriting approval and satisfaction of closing conditions, the DSCR transaction can proceed to closing.
Frequently Asked Questions About DSCR Loans Salt Lake City
Can I get a DSCR loan in Salt Lake City without W-2 income?
Potentially. DSCR programs generally focus primarily on qualifying rental-property income rather than W-2 employment income. Other borrower and property requirements still apply.
Can I get a Salt Lake City DSCR loan without personal tax returns?
Many DSCR programs do not use personal tax returns to establish qualifying income. The lender can still require other documentation necessary to underwrite the borrower, entity and property.
What DSCR is needed for a Salt Lake City rental property?
There is no universal minimum. Requirements vary among lenders. Some programs prefer or require ratios at or above 1.00, while certain programs may consider lower ratios.
Can an LLC get a DSCR loan in Salt Lake City?
Potentially. Many DSCR programs permit eligible business-entity vesting, subject to lender entity documentation and guarantor requirements.
Can I use a DSCR loan for an Airbnb in Salt Lake City?
Certain lenders may finance eligible short-term rental properties, but investors must separately verify local zoning, licensing, HOA and rental restrictions. Financing approval does not establish legal permission to operate a short-term rental.
Can I cash out a Salt Lake City rental property with a DSCR loan?
Potentially. DSCR cash-out refinance programs are available from certain lenders. Maximum leverage, seasoning, credit, DSCR and other requirements vary.
Can first-time real estate investors qualify?
Certain DSCR programs permit first-time investors, while others may have additional restrictions or pricing adjustments. Program selection is important.
Are DSCR loans only for Salt Lake City?
No. DSCR investment-property financing may be available for eligible rental properties throughout Utah.
Explore the Complete Utah DSCR Loan Resource Center
Continue researching the part of DSCR financing that applies to your transaction:
- DSCR Mortgage Loans Utah — Main Guide
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Cash-Out Refinance Utah
- No-Ratio DSCR Loans Utah
- DSCR Loans for Short-Term Rentals Utah
- DSCR Loan Credit Score Utah
- DSCR Loan Down Payment Utah
- DSCR Loan LTV Utah
- DSCR Loans for LLCs Utah
- Interest-Only DSCR Loans Utah
- DSCR Purchase Loans Utah
- DSCR Refinance Loans Utah
- DSCR vs Conventional Investment Loan Utah
- DSCR Loans Park City
- DSCR Loans St. George
- DSCR Loans Salt Lake City
Compare DSCR Loan Options in Salt Lake City
The best DSCR structure is not necessarily the loan with the lowest advertised rate.
A Salt Lake City investor should compare the entire transaction, including DSCR, credit, LTV, cash required to close, points, lender fees, reserves, prepayment terms, interest-only options and long-term investment strategy.
As a mortgage broker, Daniel Paris can compare available wholesale DSCR programs rather than limiting an investor to a single lender's guidelines.
Daniel Paris
Utah Mortgage Broker | UtahLowRate.com
27+ Years of Mortgage Lending Experience
NMLS #243976-3138
801-604-4949
Provide the property value or purchase price, expected monthly rent, requested loan amount, estimated credit score and whether the transaction is a purchase, refinance or cash-out refinance.
Loan programs, rates, pricing, DSCR calculations, credit requirements, LTV limits, reserves, prepayment provisions and property eligibility are subject to change and lender underwriting. This information is educational and does not constitute a commitment to lend or guarantee of approval. Equal Housing Opportunity.
Related guides: Utah DSCR loan guide · DSCR loan requirements · DSCR calculation guide · DSCR loan rates · DSCR questions and answers ·

