
Content updated: September 29, 2026
High-Balance Mortgage Financing in Ogden, Ogden Valley and Northern Utah
Buying or refinancing a higher-priced home in Weber County can require a mortgage that exceeds standard conforming loan limits.
Check My Jumbo Options or call 801-604-4949.
Jumbo loans in Weber County, Utah provide financing options for qualified borrowers who need larger mortgage amounts for primary residences, second homes, luxury properties and other eligible real estate.
Daniel Paris of UtahLowRate.com helps borrowers compare jumbo and super jumbo mortgage programs from multiple lending sources for properties throughout Ogden, South Ogden, North Ogden, Pleasant View, Huntsville, Eden, Liberty and surrounding Weber County communities.
Call Daniel Paris: 801-604-4949
NMLS #243976
Quick Answer: What Is a Jumbo Loan in Weber County, Utah?
A jumbo loan in Weber County is generally a mortgage with a loan amount above the applicable conforming loan limit established for the county.
For 2026, the conforming loan limit for a one-unit property in Weber County is $832,750. A mortgage above that amount is generally considered jumbo for conforming-limit purposes.
Jumbo mortgages can have different requirements for credit, down payment, income, assets, cash reserves and property eligibility than standard conforming loans.
Weber County Jumbo Loan Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Jumbo Mortgage Topic | What Weber County Borrowers Should Know |
|---|---|
| 2026 one-unit conforming limit | $832,750 |
| Loans above the applicable limit | Generally considered jumbo |
| Primary residences | Available with qualifying programs |
| Second homes | Available through selected jumbo lenders |
| Investment properties | Certain programs may be available |
| Self-employed borrowers | Traditional and alternative documentation may be available |
| Purchase transactions | Available |
| Rate-and-term refinance | Available |
| Cash-out refinance | Available with qualifying programs |
| Fixed-rate mortgages | Available depending on lender |
| Adjustable-rate mortgages | Available depending on program |
| Super jumbo financing | Available for qualified high-value transactions |
| Property appraisal | Required by most programs |
| Reserves | Frequently required and program-specific |
Program availability, rates, LTV limits, credit requirements and underwriting guidelines vary by lender and borrower qualifications.
2026 Jumbo Loan Limit for Weber County
For a one-unit property in Weber County, Utah, the 2026 conforming loan limit is:
$832,750
That distinction is important because whether a mortgage is considered jumbo is based primarily on the loan amount, rather than simply the purchase price of the home.
For example, someone purchasing a $1 million property with a large enough down payment could potentially keep the requested mortgage at or below the applicable conforming limit.
Another borrower purchasing a similarly priced property with a smaller down payment could require a mortgage above the limit and therefore need jumbo financing.
The Federal Housing Finance Agency establishes conforming loan limits for mortgages eligible for acquisition by Fannie Mae and Freddie Mac.
Where Are Jumbo Loans Used in Weber County?
Jumbo financing may be appropriate for qualified borrowers purchasing or refinancing properties throughout Weber County, including:
- Ogden
- South Ogden
- North Ogden
- Pleasant View
- Washington Terrace
- Riverdale
- Roy
- Uintah
- Farr West
- Marriott-Slaterville
- Harrisville
- Plain City
- Huntsville
- Eden
- Liberty
- Ogden Valley
- Powder Mountain-area communities
- Pineview Reservoir-area properties
The correct mortgage program depends on the property itself as well as the borrower's financial qualifications.
Jumbo Loans in Ogden, Utah
Higher-priced properties in Ogden and surrounding communities can sometimes require loan amounts beyond conventional conforming limits.
A jumbo loan in Ogden, Utah may be appropriate for buyers who need additional borrowing capacity while purchasing an eligible higher-value home.
Borrowers may have access to several types of jumbo financing depending on qualifications, including:
- Fixed-rate jumbo mortgages
- Adjustable-rate jumbo mortgages
- Purchase loans
- Rate-and-term refinances
- Cash-out refinances
- Second-home jumbo loans
- Self-employed jumbo programs
- Alternative-documentation jumbo loans
- Super jumbo mortgages
Because jumbo lenders establish their own underwriting guidelines, comparing programs can be particularly important.
Jumbo Loans for Ogden Valley Homes
Ogden Valley includes a mix of primary residences, second homes, recreational properties, custom homes and higher-value mountain real estate.
Properties around Huntsville, Eden and Liberty can present underwriting considerations that differ from a typical suburban residence.
Depending on the property and lender, underwriting may evaluate:
- Property location
- Property type
- Acreage
- Unique construction
- Comparable sales
- Appraised value
- Marketability
- Primary or second-home occupancy
- Access
- HOA characteristics
- Other property-specific factors
A unique property does not automatically prevent jumbo financing, but selecting a lender familiar with the appropriate property type can become especially important.
Jumbo Loans in Huntsville, Eden and Liberty
Buyers considering homes around Huntsville, Eden or Liberty may need financing structured around both the borrower and the property.
Potential transactions may include:
Huntsville Jumbo Loans
Jumbo financing may be used by qualified borrowers purchasing or refinancing higher-value homes around Huntsville, Pineview Reservoir and surrounding Ogden Valley communities.
Eden Jumbo Loans
Eden contains primary residences, vacation homes and properties associated with the broader mountain recreation market.
Eligible borrowers may have jumbo financing options for primary residences and qualifying second homes.
Liberty Jumbo Loans
Custom homes and larger residential properties around Liberty can sometimes require high-balance financing.
Property characteristics and appraisal support can be particularly important with unique homes.
What Can a Weber County Jumbo Loan Be Used For?
Depending on lender guidelines, jumbo mortgages may be available for several different purposes.
Purchase a Home
A jumbo purchase loan can help finance an eligible Weber County property when the desired mortgage exceeds the applicable conforming limit.
Refinance an Existing Jumbo Mortgage
Borrowers may consider refinancing to change the mortgage rate, term or overall loan structure.
Jumbo Cash-Out Refinance
Qualified homeowners may be able to access a portion of accumulated home equity through a jumbo cash-out refinance.
Maximum LTV and cash-out limits depend on the lender and requested loan amount.
Second-Home Financing
Certain jumbo programs allow financing for eligible second homes.
Investment Properties
Selected jumbo and non-QM programs may permit eligible investment properties.
Occupancy classification needs to accurately reflect how the property will actually be used.
Weber County Jumbo Loan Requirements
There is no single universal set of jumbo mortgage requirements.
Unlike standard conforming underwriting, jumbo loan guidelines can vary considerably between lenders.
A lender may evaluate:
- Credit score
- Credit history
- Loan amount
- Down payment
- Loan-to-value ratio
- Debt-to-income ratio
- Income
- Employment
- Self-employment
- Assets
- Cash reserves
- Property type
- Appraised value
- Occupancy
- Number of financed properties
- Overall borrower risk profile
This is one reason comparing more than one jumbo lending source can be valuable.
What Credit Score Is Needed for a Jumbo Loan?
There isn't one credit score requirement that applies to every Weber County jumbo mortgage.
Required credit depends on the lender and may change according to:
- Loan amount
- LTV
- Property type
- Occupancy
- Income documentation
- Reserves
- Overall financial profile
In general, stronger credit can provide access to a wider range of jumbo programs.
However, a borrower should not assume that failing to satisfy one bank's credit requirement means every jumbo lender will reach the same conclusion.
How Much Down Payment Is Required for a Jumbo Loan?
There is no universal jumbo mortgage down payment requirement.
Required equity is normally tied to the lender's permitted loan-to-value ratio (LTV).
For example:
Home Value – Loan Amount = Borrower Equity
A lower LTV generally means the borrower has more equity in the property.
Maximum LTV can change according to:
- Credit profile
- Loan amount
- Occupancy
- Property type
- Documentation method
- Purchase versus refinance
- Lender guidelines
Larger jumbo and super jumbo transactions may require more borrower equity.
Do Jumbo Loans Require Cash Reserves?
Many jumbo mortgage programs require borrowers to maintain financial reserves after closing.
Reserves generally represent funds available after the mortgage transaction is completed.
A lender may calculate reserves in terms of a certain number of months of the property's qualifying housing payment.
Reserve requirements can vary according to:
- Loan amount
- LTV
- Primary versus second-home occupancy
- Number of financed properties
- Credit profile
- Income documentation
- Overall financial strength
Some borrowers with substantial liquid assets may fit lender programs differently than borrowers with limited post-closing liquidity.
Income Requirements for a Weber County Jumbo Mortgage
Traditional jumbo underwriting generally requires sufficient verified income to support the proposed mortgage and other qualifying obligations.
Depending on the borrower, documentation can include:
- Pay stubs
- W-2 forms
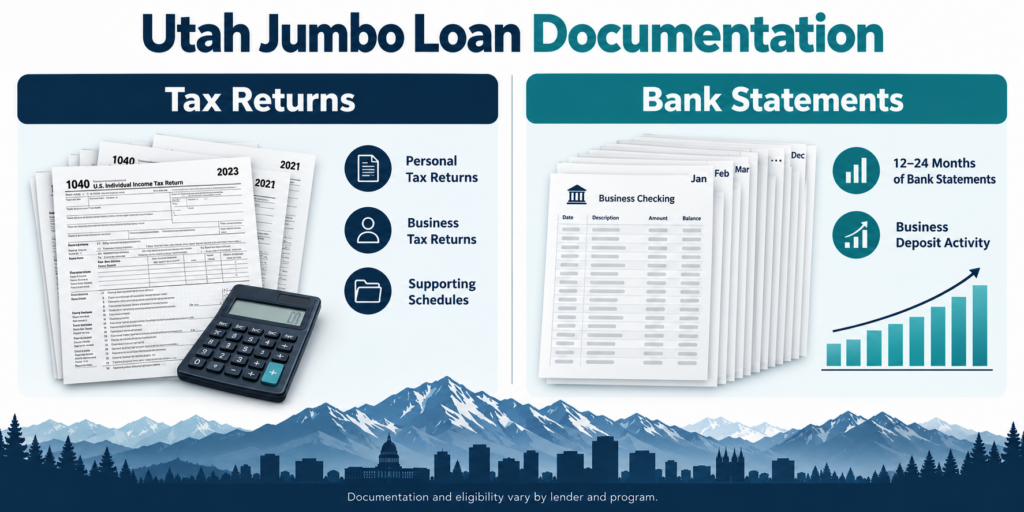
- Personal tax returns
- Business tax returns
- Employment verification
- Bank statements
- Brokerage statements
- Retirement assets
- Other qualifying financial documentation
The required documentation depends on how the borrower earns income and which jumbo program is selected.
Jumbo Loans for Self-Employed Borrowers in Weber County
Self-employed borrowers can have strong income and substantial assets while still having complicated tax returns.
Business deductions, depreciation and other legitimate tax strategies can cause taxable income to look different from actual business cash flow.
Depending on borrower qualifications and lender guidelines, potential jumbo mortgage options may include:
Full-Documentation Jumbo Loans
Tax returns and other conventional income documents are used to determine qualifying income.
Jumbo Bank Statement Loans
Eligible self-employed borrowers may be able to use qualifying deposits from personal or business bank statements to document income.
Profit-and-Loss Programs
Certain lending programs may allow qualifying income to be evaluated using eligible profit-and-loss documentation.
Asset Depletion Programs
Borrowers with substantial eligible assets may have programs available that convert qualifying assets into an income calculation.
Other Non-QM Jumbo Programs
Additional alternative-documentation options may be available depending on the borrower and property.
Alternative documentation does not mean there is no underwriting. Credit, assets, property, ability to repay and other lender requirements still apply.
Jumbo Loans for Business Owners and Entrepreneurs
Northern Utah has many borrowers whose income does not come entirely from a traditional W-2 paycheck.
Potential jumbo borrowers can include:
- Business owners
- Independent contractors
- Entrepreneurs
- Real estate investors
- Commission-based professionals
- Executives
- Medical professionals
- Retirees with substantial assets
- Borrowers with multiple income sources
The correct jumbo program depends heavily on how income and assets can be documented.
Jumbo Loans for Second Homes in Ogden Valley
Ogden Valley's recreation and mountain-home market means some borrowers purchase properties as second residences.
Certain jumbo lenders permit financing for a qualifying second home in Weber County.
Second-home underwriting can differ from primary-residence financing in areas such as:
- Maximum LTV
- Required reserves
- Pricing
- Property eligibility
- Minimum credit
- Occupancy requirements
A second home should not be represented as a primary residence simply to obtain different loan terms.
Accurate occupancy classification is essential.
Jumbo Loans for Investment Properties
Certain lenders may offer jumbo or non-QM programs for qualifying investment properties.
Investment-property underwriting can differ significantly from primary-residence jumbo lending.
Depending on the program, qualification might involve:
- Traditional borrower income
- Rental income
- Lease documentation
- Property cash flow
- DSCR qualification
- Assets
- Other approved documentation
Borrowers purchasing rental properties should compare jumbo financing with applicable investment-property and DSCR programs rather than assuming one loan type is automatically best.
Jumbo Mortgage Appraisals in Weber County
The appraisal can be especially important with high-value or unusual homes.
A jumbo appraisal generally evaluates the property's value using available comparable sales and relevant market characteristics.
Underwriters may pay particular attention to:
- Location
- Square footage
- Lot size
- Construction quality
- Condition
- Views
- Acreage
- Property amenities
- Recent comparable sales
- Marketability
For unique Ogden Valley properties, finding closely comparable sales may be more difficult than for homes in large subdivisions.
Depending on loan size and lender requirements, additional appraisal review or valuation documentation may sometimes be required.
Jumbo vs. Conventional Mortgage in Weber County
The primary distinction begins with whether the mortgage falls within the applicable conforming loan limit.
| Feature | Conforming Mortgage | Jumbo Mortgage |
|---|---|---|
| Loan amount | Within applicable conforming limits | Above applicable conforming limit |
| Fannie/Freddie eligibility | May qualify | Generally outside standard conforming acquisition limits |
| Underwriting | More standardized | Often lender-specific |
| Reserves | Program-dependent | Frequently more substantial |
| Large loan flexibility | Limited by conforming limits | Designed for larger mortgages |
| Unique borrower situations | Program-dependent | Broader lender variation may exist |
The best option depends on the requested loan amount and borrower profile.
Jumbo vs. Super Jumbo Loans
A jumbo mortgage exceeds the applicable conforming loan limit.
A super jumbo loan generally describes a substantially larger mortgage, often involving multimillion-dollar financing.
There isn't one universal dollar amount at which every lender begins using the term "super jumbo."
As mortgage balances increase, underwriting may become more specialized.
Potential considerations can include:
- Greater liquidity
- Higher reserve requirements
- Lower maximum LTV
- Multiple appraisals or valuation reviews
- Complex income
- Significant investment assets
- Multiple properties
- Customized loan structures
Daniel Paris can help qualified borrowers compare available jumbo and super jumbo programs based on the actual transaction.
Fixed-Rate vs. Adjustable-Rate Jumbo Mortgages
Depending on lender availability, Weber County borrowers may be able to compare fixed and adjustable jumbo mortgages.
Fixed-Rate Jumbo Mortgage
The mortgage interest rate remains fixed according to the terms of the loan.
This may appeal to borrowers who prioritize payment predictability.
Adjustable-Rate Jumbo Mortgage
An adjustable-rate mortgage generally has an initial rate structure followed by potential adjustments according to the specific loan terms.
ARMs can be worth evaluating for borrowers whose expected ownership or financing timeline differs from a traditional long-term fixed-rate strategy.
The appropriate choice depends on the borrower's objectives and risk tolerance.
Jumbo Purchase Loans in Weber County
When purchasing a higher-value Weber County home, it can help to evaluate financing before submitting an offer.
A jumbo mortgage review may examine:
- Purchase price
- Desired loan amount
- Down payment
- Credit profile
- Income type
- Assets and reserves
- Property type
- Intended occupancy
This provides a more complete picture than looking at the purchase price alone.
Jumbo Refinancing in Weber County
Homeowners with high-balance mortgages may consider refinancing for several reasons.
Rate-and-Term Refinance
A borrower may refinance to modify the mortgage rate, term or loan structure.
Cash-Out Refinance
Eligible borrowers may be able to access a portion of accumulated equity.
Adjustable-to-Fixed Refinance
Some borrowers with adjustable mortgages may evaluate a fixed-rate alternative.
Whether refinancing makes financial sense depends on the current loan, available rates, closing costs, expected holding period and borrower objectives.
How to Compare Jumbo Mortgage Offers
Looking only at the advertised interest rate can produce an incomplete comparison.
Consider evaluating:
- Interest rate
- APR
- Discount points
- Origination costs
- Lender fees
- Loan term
- Fixed versus adjustable rate
- Prepayment provisions when applicable
- Required reserves
- Maximum LTV
- Documentation requirements
- Closing timeline
A seemingly lower rate may involve higher upfront costs.
Why Work with a Mortgage Broker for a Jumbo Loan?
Jumbo mortgage lending is less standardized than conforming lending.
One lender may have:
- A different maximum LTV
- Different reserve requirements
- Different self-employed income calculations
- Different property restrictions
- Different loan amount limits
- Different credit requirements
A borrower can therefore fit one jumbo lender's guidelines better than another's.
Daniel Paris of UtahLowRate.com helps qualified borrowers compare available wholesale jumbo mortgage options based on the actual property, requested loan amount and financial profile.
How the Weber County Jumbo Mortgage Process Works
1. Review the Property and Loan Amount
Start with the approximate purchase price or current property value and desired mortgage balance.
2. Determine Whether the Loan Is Jumbo
Compare the requested mortgage amount with the applicable Weber County conforming loan limit.
3. Review Borrower Qualifications
Evaluate credit, income, employment, assets, reserves and existing obligations.
4. Compare Jumbo Programs
Different lenders may offer different guidelines and pricing.
5. Complete the Application
Provide the documentation required for the selected program.
6. Appraisal and Underwriting
The lender evaluates both the borrower and the property.
7. Final Approval and Closing
Once applicable underwriting conditions are satisfied, the loan can proceed toward closing.
Documents to Prepare for a Jumbo Loan
Depending on your program, it may help to prepare:
- Government-issued identification
- Recent income documentation
- W-2s when applicable
- Tax returns when required
- Business documentation for self-employed borrowers
- Bank statements
- Investment account statements
- Retirement account statements
- Existing mortgage statements
- Homeowners insurance information
- Purchase contract for a purchase transaction
- Information about other financed properties
Alternative-documentation programs may require a different document set.
Frequently Asked Questions About Jumbo Loans in Weber County
What is the jumbo loan limit in Weber County, Utah for 2026?
For 2026, the conforming loan limit for a one-unit property in Weber County is $832,750. A mortgage amount above the applicable conforming limit is generally considered jumbo.
Is a $900,000 mortgage a jumbo loan in Weber County?
For a one-unit property in 2026, a $900,000 mortgage exceeds Weber County's $832,750 conforming loan limit and would generally fall into jumbo territory.
Is a $900,000 home automatically a jumbo loan?
No.
The classification is based on the mortgage amount, not simply the home's purchase price.
A buyer purchasing a $900,000 property with enough money down could potentially have a conforming loan amount.
Can I get a jumbo loan in Ogden, Utah?
Yes. Qualified borrowers may have jumbo financing options for eligible properties throughout Ogden and Weber County.
Are jumbo loans available in Huntsville and Eden?
Yes. Jumbo financing may be available for eligible properties in Huntsville, Eden, Liberty and other Ogden Valley communities, subject to borrower and property qualifications.
Can I finance an Ogden Valley second home with a jumbo mortgage?
Certain jumbo lenders permit qualifying second homes. LTV, reserve and occupancy requirements may differ from primary-residence financing.
Can self-employed borrowers get jumbo loans?
Yes. Qualified self-employed borrowers may use traditional documentation or eligible alternative-documentation programs depending on lender guidelines.
Can I use bank statements to qualify for a jumbo loan?
Certain programs allow qualifying self-employed borrowers to use eligible personal or business bank statements instead of relying entirely on traditional tax-return income.
Do jumbo loans require 20% down?
Not necessarily. There isn't one universal down-payment requirement for every jumbo mortgage. Maximum LTV varies according to the lender, loan amount, credit profile, occupancy and property.
Do jumbo mortgages require reserves?
Many do. Reserve requirements vary significantly by lender, loan size and borrower profile.
Can I refinance a jumbo loan?
Yes. Eligible borrowers may have both rate-and-term and cash-out jumbo refinance options.
Are super jumbo loans available in Weber County?
Potentially. Qualified borrowers seeking substantially larger mortgage amounts may have access to specialized super jumbo programs.
Are jumbo rates always higher than conventional mortgage rates?
No. Jumbo pricing depends on lender appetite, financial markets, credit, LTV, loan amount, occupancy and other factors. Jumbo rates can sometimes be competitive with conforming mortgage pricing.
Does UtahLowRate.com only handle Weber County?
No. Daniel Paris works with qualifying borrowers throughout Utah, including Weber County, Salt Lake County, Utah County, Summit County, Wasatch County, Washington County and other eligible Utah markets.
Explore Related Utah Jumbo Mortgage Resources
If you are researching a Weber County jumbo mortgage, these related resources may help:
- Jumbo Mortgage Utah — statewide jumbo mortgage guide
- Jumbo Loan Requirements Utah — credit, LTV, reserves and documentation
- Jumbo Mortgage Calculator Utah — estimate payments for different loan scenarios
- Jumbo Mortgage FAQ Utah — answers to common jumbo questions
- Jumbo Loans Park City Utah
- Jumbo Loans Heber City Utah
- Jumbo Loans Salt Lake City Utah
- Jumbo Loans St. George Utah
- Super Jumbo Loans Utah
- Bank Statement Loans Utah
These links help borrowers move from general research to the specific financing information most relevant to their situation.
Compare Jumbo Loans in Weber County, Utah
A jumbo mortgage should be structured around more than the size of the loan.
The right program depends on the interaction between:
property + loan amount + equity + credit + income + assets + occupancy + borrower objectives.
Daniel Paris of UtahLowRate.com helps qualified borrowers compare jumbo and super jumbo mortgage options from available lending sources for homes throughout Ogden, Ogden Valley and Weber County.
Talk With Daniel Paris
Daniel Paris
UtahLowRate.com
Phone: 801-604-4949
NMLS #243976
Serving jumbo mortgage borrowers throughout:
Ogden • South Ogden • North Ogden • Pleasant View • Huntsville • Eden • Liberty • Riverdale • Roy • Washington Terrace • Farr West • Plain City • Ogden Valley • Weber County • Northern Utah
Request a Jumbo Mortgage Comparison
When contacting Daniel, it helps to provide:
- Property location
- Purchase price or estimated value
- Desired loan amount
- Down payment or current equity
- Primary residence, second home or investment property
- Approximate credit profile
- Employment or self-employment status
That information can help identify jumbo programs that may fit the transaction.
Important Mortgage Disclosure
Mortgage programs, interest rates, loan-to-value limits, credit requirements, reserve requirements, loan amounts and underwriting guidelines are subject to change and may vary by lender. Not all borrowers or properties qualify for all programs. This page is for general educational purposes and is not a commitment to lend or a guarantee of approval.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

