
Physician Loans Utah: Down Payment, PMI & Student Loans
Physician loans Utah: Can doctors buy with little or no down payment?
Physician loans Utah lenders offer may let eligible doctors buy a primary home with 0% to 5% down. Some programs do not require monthly private mortgage insurance (PMI). Lender rules vary. Borrowers must meet the lender’s requirements.
Physician loans Utah lenders offer are not a government program. Each lender sets its own rules. Compare physician loans Utah buyers can access with conventional, VA or jumbo options when they fit. These examples do not promise approval or terms.
Who is a physician loan for, and who needs another option?
Physician loans are mainly for medical doctors (MD or DO), including residents and fellows, who are buying a primary home. Many lenders also accept dentists (DDS or DMD), and some add other doctorate-level or advanced-practice clinicians. Buyers of second homes or rentals, and buyers who already have 20% down, often do better elsewhere.
Who this usually applies to
- MDs and DOs, including residents, fellows and, at some lenders, interns or graduating medical students.
- Dentists (DDS or DMD) at many lenders.
- At some lenders only: podiatrists (DPM), veterinarians (DVM or VMD), pharmacists (PharmD), optometrists (OD), CRNAs, physician assistants, nurse practitioners and, rarely, registered nurses or chiropractors. Eligible professions vary by lender.
- Buyers relocating to Utah, or finishing training, who have a signed contract but have not started the job.
- Borrowers with large student loan balances or limited savings for a down payment.
Who needs another option
- Second homes and rentals: most physician programs require a primary residence. A few allow second homes; investment property generally needs a conventional or DSCR loan.
- Buyers with 20% or more down: a conventional loan has no mortgage insurance at 80% loan-to-value or less and may price better. See physician mortgage vs. conventional loan.
- Eligible veterans and service members: a VA loan allows no down payment and has no monthly mortgage insurance. See VA home loans in Utah.
- Loan amounts above a lender’s physician cap: compare Utah jumbo mortgages.
- Practice owners paid through their business: income may be documented with tax returns, or with bank statement loans when returns do not show current cash flow.
How do physician loans Utah lenders offer compare with other loan options?
Physician loans Utah doctors compare may allow less money down and no PMI. Student loan rules may also be more flexible. Conventional, FHA and VA loans use agency rules. Physician and jumbo terms come from each lender. Compare the options below. Lender terms vary.
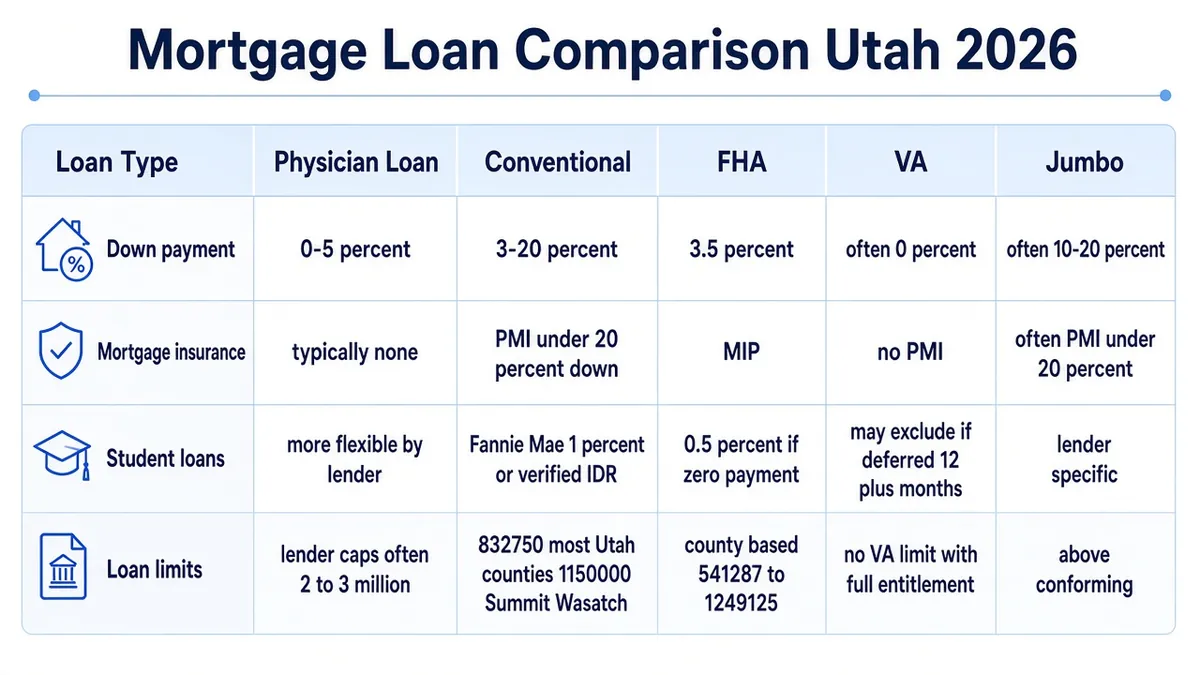
| Feature | Physician loan (typical; varies by lender) | Conventional (Fannie Mae) | FHA | VA | Jumbo |
|---|---|---|---|---|---|
| Minimum down payment | Commonly 0%–5% up to a lender’s maximum-financing cap (often $850,000–$2 million); more down above it | 3% for eligible buyers using 97% LTV options; otherwise more | 3.5% with a 580+ credit score | 0% with full entitlement | Set by each lender |
| Mortgage insurance | Typically none | Required above 80% LTV; can be cancelled at 80% and ends by 78% of original value | 1.75% upfront plus annual MIP (0.55% for 30-year loans of $726,200 or less with under 5% down) | No monthly MI; one-time funding fee (2.15% first use with under 5% down) unless exempt | Usually none; varies |
| Student loans in DTI | Often more lenient; some lenders exclude deferred or forborne loans for residents and fellows, or use the income-driven payment | Reported payment; a verified $0 income-driven payment can be used; deferred or forborne: 1% of balance or a fully amortizing payment | Reported payment if above $0; if $0, 0.5% of the balance | Excluded if deferred 12+ months past closing; otherwise at least 5% of the balance ÷ 12, unless a lower payment is documented by the servicer | Set by each lender |
| Closing before the job starts | Commonly allowed with a signed contract; published windows of about 90–150 days from closing to start date | Allowed; without a paystub before delivery, start date up to 90 days after closing plus extra reserves | New-job income must begin within 60 days of closing, with income or reserves to cover the gap | Confirm with the lender | Set by each lender |
| 2026 loan limits in Utah | No agency limit; lender caps, commonly $2 million–$3 million | $832,750 in most Utah counties; $1,150,000 in Summit and Wasatch | Set by county; $541,287 floor to $1,249,125 ceiling; Utah County $601,450 | No VA limit with full entitlement; lender approval still applies | Above the county conforming limit |
| Occupancy | Usually primary residence only | Primary, second home or investment | Primary residence | Primary residence | Varies |
Sources: FHFA 2026 conforming loan limits (November 25, 2025) and county list; Fannie Mae Selling Guide B3-6-05 (08/05/2026), B3-3.3-03 (10/07/2026) and B7-1-02, and Fannie Mae’s 97% LTV Options page; HUD Mortgagee Letters 2025-23, 2023-05 and 2021-13 and HUD Handbook 4000.1; VA Circular 26-17-02, VA loan limits and VA funding fee pages; CFPB on PMI removal. Physician ranges are drawn from published lender program pages listed under Sources, accessed November 4, 2026. Full links are below.
How do lenders count student loans for doctors?
Student loan rules depend on the loan type. Fannie Mae may use 1% of a deferred or forborne balance, or a fully amortizing payment. FHA uses 0.5% if the reported payment is $0. VA may exclude a loan deferred for 12 months or more after closing. Some physician lenders may be more flexible. Ask how your lender will count the payment.
For example, a $250,000 balance with a $0 reported payment may count as $2,500 a month for conventional or $1,250 for FHA. A physician lender may count $0 for a resident with a deferred loan. Fannie Mae may use a verified $0 income-driven payment as $0. Ask the lender how it will count your payment. See also medical resident mortgage loans: contracts and student loans.
Can I close on a Utah home before my new medical job starts?
Some physician loans Utah lenders offer allow closing before a job starts. You may need a signed contract. Each lender sets its own time window. Fannie Mae and FHA have separate rules for new jobs. Ask what funds you need to cover the gap before your first paycheck.
What 2026 loan limits matter for a physician loan in Utah?
Physician loans Utah doctors compare have lender-set caps. FHFA and FHA limits still help with comparisons. In 2026, the conventional limit is $832,750 in most Utah counties. It is $1,150,000 in Summit and Wasatch counties. A larger loan is usually a jumbo loan.
For other counties and two- to four-unit limits, see 2026 conventional loan limits in Utah, 2026 FHA loan limits in Utah and Park City jumbo mortgage down payments.
Hypothetical example: a resident buying in Lehi before starting an attending job
Hypothetical example for illustration only. Not a quote, an approval or an offer of terms.
Dr. A is finishing residency and has a signed, non-contingent contract for a $320,000 base salary at a Utah County practice, starting August 2, 2027. She wants to close on a $700,000 home in Lehi on June 15, 2027, which is 48 days before her start date. She has $250,000 of federal student loans in forbearance, showing a $0 payment on her credit report.
- Conventional, 5% down: $35,000 down and a $665,000 loan, under the $832,750 Utah County conforming limit. PMI applies above 80% LTV. Student loans count at $2,500 a month (1% of the balance), about 9.4 percentage points of her $26,667 gross monthly income. If the lender uses Fannie Mae’s no-paystub contract option, extra reserves also apply.
- FHA, 3.5% down: the $675,500 base loan would exceed Utah County’s $601,450 FHA limit, so FHA would only work with roughly $98,550 or more down.
- Physician loan, 0%–5% down: if the lender’s maximum-financing tier covers $700,000, she may need little or no down payment and no PMI. Some lenders would exclude her forborne student loans while she is in training; others would count a payment. Her 48-day gap fits the 90- to 150-day windows lenders commonly publish.
The physician loan may still carry a different rate, fees or reserve requirement than the conventional loan. Dr. A should compare Loan Estimates for both, issued the same day for the same price and lock period.
What documents do physician loans Utah lenders ask you to provide?
Physician loans Utah lenders offer may require different records by specialty and job status. The lender may ask for the items below. Send files through a secure channel.
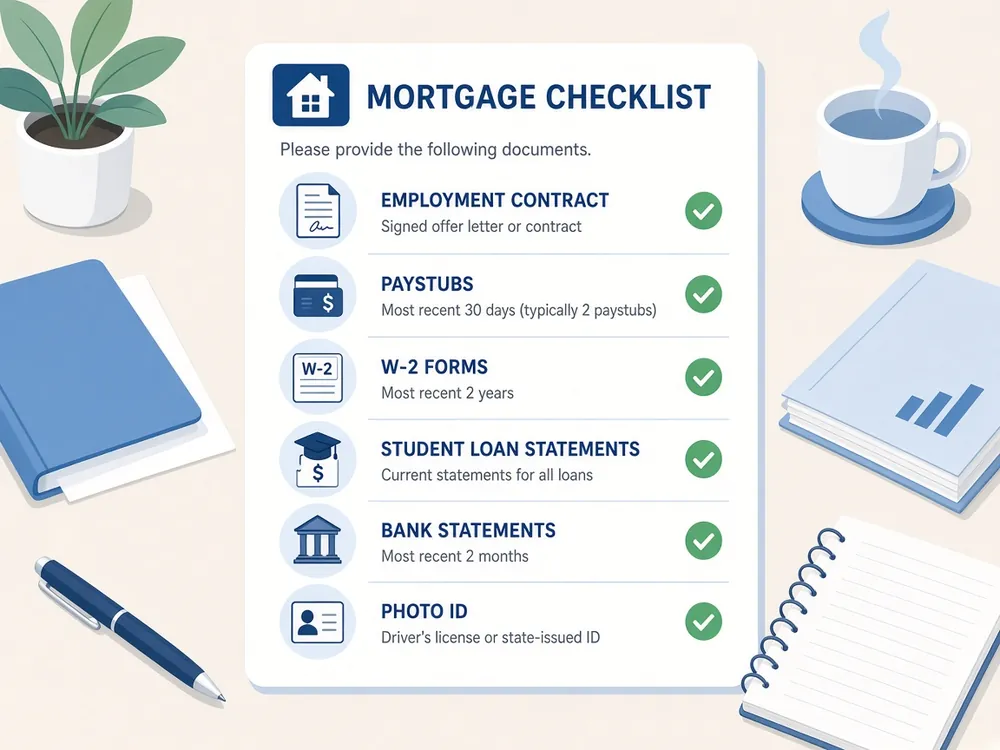
- Government-issued photo ID.
- Medical, dental or other professional degree, license or proof of residency or fellowship, if the lender requests it.
- Signed, non-contingent employment contract or offer letter showing employer, position, pay and start date.
- Recent paystubs and W-2s for the last two years; for practice owners or 1099 income, personal and business tax returns.
- Student loan servicer statements showing balance, monthly payment, repayment plan and deferment or forbearance end dates.
- Two months of bank, brokerage and retirement statements, plus a gift letter if family is helping.
- Statements for other debts, and the purchase contract and HOA details once you have them.
Is a physician loan always the best choice for a doctor?
No. A physician loan helps most when savings are limited or student loans would push a conventional DTI too high. With 20% down, a conventional loan avoids PMI and may price better. Eligible veterans should compare VA. Compare the total cost over the years you expect to keep the loan, not just the down payment.
Can dentists, residents or fellows get a physician loan in Utah?
Many programs accept MDs and DOs, including residents and fellows. Many also accept dentists. Some accept other clinicians. Physician loans Utah lenders offer may have different profession rules. Confirm your degree and training status before you make an offer.
See home loans for medical professionals in Utah and Utah physician loan requirements and FAQs.
What credit score do I need for a physician loan?
Minimum scores vary by lender and by how much you put down. Published physician programs commonly start around 680 to 700, and the highest financing or largest loan amounts may require higher scores. Paying down credit card balances and checking your reports before you apply can help. Ask each lender for its exact score tiers.
Can I use a physician loan for a second home in Park City?
Usually not. Most physician programs require the home to be your primary residence, though a few published options allow second homes. For a Park City or Heber vacation home, compare conventional second-home financing, which in 2026 is limited to $1,150,000 in Summit and Wasatch counties, with jumbo financing above that.
Are physician loan rates higher than conventional rates?
Sometimes. Physician loan pricing is set by each lender, and the rate, points and fees can be higher or lower than a conventional loan for the same borrower. Mortgage insurance savings and a smaller down payment are part of the trade-off. Compare the APR, cash to close and monthly payment on official Loan Estimates.
See Utah physician loan down payment and mortgage insurance. For the Teal, Pink and Silver doctor-loan options Daniel compares, see physician loan options in Utah; confirm current terms before relying on them.
Next step: request a physician loan vs. conventional comparison
Share your signed contract or expected start date, student loan statements and target price. Daniel can compare physician loans Utah buyers may qualify for with conventional options. If relevant, he can also compare VA or jumbo financing. Review down payment, mortgage insurance, counted student loan payment and cash to close. Request your comparison or call (801) 604-4949.
Related Utah physician loan guides
- Utah physician mortgage loans: doctor loan guide
- Physician mortgage loans in Utah cities and counties
- Utah County mortgage loans: Provo, Orem and Lehi
- Salt Lake City mortgage loans
- Utah mortgage pre-approval
Sources
- FHFA, “FHFA Announces Conforming Loan Limit Values for 2026,” November 25, 2025: FHFA 2026 conforming loan limit announcement
- FHFA, 2026 conforming loan limits by county (Utah: $832,750 in most counties; Summit and Wasatch $1,150,000): FHFA 2026 county loan limit list
- Fannie Mae Selling Guide B3-6-05, Monthly Debt Obligations, Student Loans (08/05/2026): Fannie Mae Selling Guide: student loans
- Fannie Mae Selling Guide B3-3.3-03, Employment Offers or Contracts (10/07/2026): https://selling-guide.fanniemae.com/sel/b3-3.3-03/employment-offers-or-contracts
- Fannie Mae Selling Guide B7-1-02, Mortgage Insurance Coverage Requirements: https://selling-guide.fanniemae.com/sel/b7-1-02/mortgage-insurance-coverage-requirements
- Fannie Mae, 97% Loan to Value Options: https://singlefamily.fanniemae.com/originating-underwriting/mortgage-products/97-loan-value-options
- HUD Mortgagee Letter 2025-23, 2026 FHA forward mortgage limits (December 11, 2025): HUD 2026 FHA loan limits
- HUD FHA Mortgage Limits lookup (Utah County, CY2026): https://entp.hud.gov/idapp/html/hicostlook.cfm
- HUD Mortgagee Letter 2021-13, Student Loan Payment Calculation (effective August 16, 2021): https://www.hud.gov/sites/dfiles/OCHCO/documents/2021-13hsgml.pdf
- HUD Mortgagee Letter 2023-05, Reduction of FHA Annual MIP (effective March 20, 2023): https://www.hud.gov/sites/dfiles/OCHCO/documents/2023-05hsgml.pdf
- HUD Handbook 4000.1 (Expected Income within 60 days; 580 score for maximum financing; 1.75% upfront MIP): https://www.hud.gov/program_offices/housing/sfh/handbook_4000-1/
- VA Circular 26-17-02, Student Loans (January 23, 2017): https://benefits.va.gov/HOMELOANS/documents/circulars/26_17_2.pdf
- VA, Home loan entitlement and limits: VA home loan limits
- VA, Funding fee and loan closing costs (rates effective April 7, 2023): https://www.va.gov/housing-assistance/home-loans/funding-fee-and-closing-costs/
- CFPB, When can I remove private mortgage insurance (PMI) from my loan?: https://www.consumerfinance.gov/ask-cfpb/when-can-i-remove-private-mortgage-insurance-pmi-from-my-loan-en-202/
- CFPB, Loan Estimate explainer: CFPB Loan Estimate guide
- Published physician-loan program pages used for the typical ranges (examples only, accessed November 4, 2026): UWM Doctor Loans, https://www.uwm.com/trending/doctor-loans-expanded; Bank of America Doctor Loan, https://www.bankofamerica.com/mortgage/doctor-loan/; Huntington Doctor Loan, https://www.huntington.com/physician-loans/doctor-loan; GMFS Physician Loan, https://gmfsmortgage.com/physician-loan/
This page is educational and is not a commitment to lend, a rate quote or an offer of specific terms. Physician loan features, eligible professions, loan caps and student loan treatment vary by lender and change without notice. Loan limits are set by FHFA and HUD each year. All financing is subject to borrower qualification, property eligibility, lender guidelines and underwriting approval.
Daniel Paris, NMLS #243976. Utah Low Rate (DBA UtahLowRate.com), NMLS #243976-3138. 512 East Winchester Street, Murray, UT 84107. (801) 604-4949. Equal Housing Opportunity. Verify licensing at www.nmlsconsumeraccess.org.

