
Home Loans for Business Owners
If you are self-employed and buying or refinancing a home in Utah, your mortgage options are not limited to traditional W-2 financing. A self-employed mortgage in Utah may use tax returns, bank statements, 1099 income, Profit and Loss statements, eligible assets or other approved documentation, depending on the loan program.
UtahLowRate.com helps Utah business owners, entrepreneurs, independent contractors, real estate professionals and other self-employed borrowers compare conventional and alternative-documentation mortgage programs.
Daniel Paris | Utah Mortgage Broker
27+ Years of Mortgage Experience
UtahLowRate.com | 801-604-4949
Mortgage programs are available to qualified borrowers throughout Utah, including Salt Lake City, Murray, Holladay, Millcreek, Sandy, Draper, Park City, Deer Valley, Heber City, Lehi, Provo, Orem, Ogden and St. George.
Quick Answer: Can You Get a Mortgage in Utah If You Are Self-Employed?
Yes. Self-employed borrowers can qualify for home loans in Utah.
The main difference is how the lender documents and calculates qualifying income.
Traditional mortgages may rely on federal tax returns and business financial information. Alternative-documentation programs may instead evaluate eligible bank deposits, 1099 income, Profit and Loss statements, assets or investment-property cash flow.
The right mortgage depends on your income structure, credit, assets, down payment, loan amount, occupancy and property.
Self-Employed Mortgage Options at a Glance
| Borrower Situation | Mortgage Option to Explore |
|---|---|
| Tax returns show sufficient qualifying income | Conventional mortgage |
| Strong personal or business deposits | Bank Statement mortgage |
| Most income is reported on Form 1099 | 1099 mortgage |
| Strong current business financials | Profit & Loss mortgage |
| Complex or alternative income | Non-QM mortgage |
| Higher-priced property | Jumbo mortgage |
| High-value property with alternative documentation | Jumbo Bank Statement mortgage |
| Investment property with rental cash flow | DSCR mortgage |
| Eligible Veteran or service member | VA mortgage |
| Eligible owner-occupied borrower | FHA mortgage |
This is a starting point rather than an approval chart. Each program has its own underwriting requirements.
What Is a Self Employed Mortgage in Utah?
A self employed mortgage is not one specific type of home loan.
Instead, the term describes mortgage financing for people who earn some or all of their income through a business, independent contracting, commissions, partnerships or other self-employment activities.
Self-employed borrowers may include:
- Business owners
- Independent contractors
- Consultants
- Freelancers
- Realtors and real estate professionals
- Attorneys
- Medical professionals
- Contractors and builders
- Sales professionals
- Agency owners
- Restaurant owners
- Online business owners
- Investors
- Gig-economy workers
- 1099 professionals
Some borrowers can qualify through a standard Conventional Mortgage Loan.
Others may benefit from an alternative method of documenting income.
Why Is Getting a Mortgage Different When You Are Self-Employed?
The challenge is often not how much money your business earns.
It is how much income mortgage underwriting allows the lender to use.
Business owners frequently take legitimate deductions for expenses such as advertising, payroll, equipment, vehicles, insurance, supplies, professional services and other operating costs.
Those deductions can reduce taxable income.
As a result, a profitable business owner can sometimes show less mortgage qualifying income on a tax return than the business's actual cash flow might suggest.
That is why it can be useful to compare both traditional and alternative-documentation mortgage programs.
Conventional Mortgages for Self-Employed Borrowers in Utah
Do not assume that being self-employed means you automatically need a Non-QM mortgage.
A conventional mortgage may still provide an attractive option when your income can be documented under agency underwriting requirements.
Self-employed income analysis can consider factors such as:
- Length of self-employment
- Historical earnings
- Income stability
- Business ownership
- Personal tax returns
- Business tax returns when required
- K-1 income
- Current business activity
- Business financial strength
- Assets and reserves
Qualified borrowers should generally evaluate conventional financing before assuming an alternative-documentation loan is necessary.
Explore: Conventional Mortgage Loans in Utah
Bank Statement Loans for Self-Employed Utah Borrowers
A Bank Statement Mortgage Loan in Utah can provide an alternative income-documentation method for eligible self-employed borrowers.
Instead of qualifying primarily from taxable income shown on federal tax returns, these programs may calculate income using eligible deposits shown on personal or business bank statements.
Depending on the program, underwriting may review 12 or 24 months of bank statements.
How Does a Bank Statement Mortgage Work?
The lender reviews eligible deposits and determines qualifying income according to the specific program.
Not every deposit necessarily counts.
Items such as transfers between accounts, borrowed money, unusual deposits and other non-income transactions may need to be excluded.
Business bank statement programs can also apply an expense factor or use another approved method of determining qualifying business income.
Bank statement financing can be especially useful for business owners whose tax returns do not accurately represent the income available for mortgage qualification.
Learn more: Utah Bank Statement Mortgage Loans
1099 Mortgage Loans in Utah
Independent contractors often receive income through IRS Form 1099 rather than W-2 wages.
A 1099 Mortgage Loan in Utah may allow an eligible borrower to qualify using an alternative analysis of 1099 income.
These programs can be relevant for:
- Independent contractors
- Consultants
- Freelancers
- Commission-based professionals
- Real estate professionals
- Other eligible 1099 earners
A 1099 mortgage is not a no-documentation mortgage. Credit, assets, income history, property and other underwriting requirements still apply.
Compare options: 1099 Mortgage Loans Utah
Profit and Loss Mortgage Loans for Utah Business Owners
Some self-employed borrowers may qualify through a Profit and Loss Mortgage Loan.
Instead of relying exclusively on historical tax-return calculations, an eligible program may use a qualifying Profit and Loss statement to help determine income.
Additional documentation can still be required to establish the business, verify assets or reserves and satisfy underwriting requirements.
P&L programs vary by lender and investor.
For that reason, it can be useful to compare a P&L mortgage against bank statement and 1099 options rather than selecting a documentation method before your financial profile has been reviewed.
Learn more: Profit and Loss Mortgage Loans in Utah
Bank Statement vs. 1099 vs. P&L Mortgage
These programs can solve similar problems, but they document income differently.
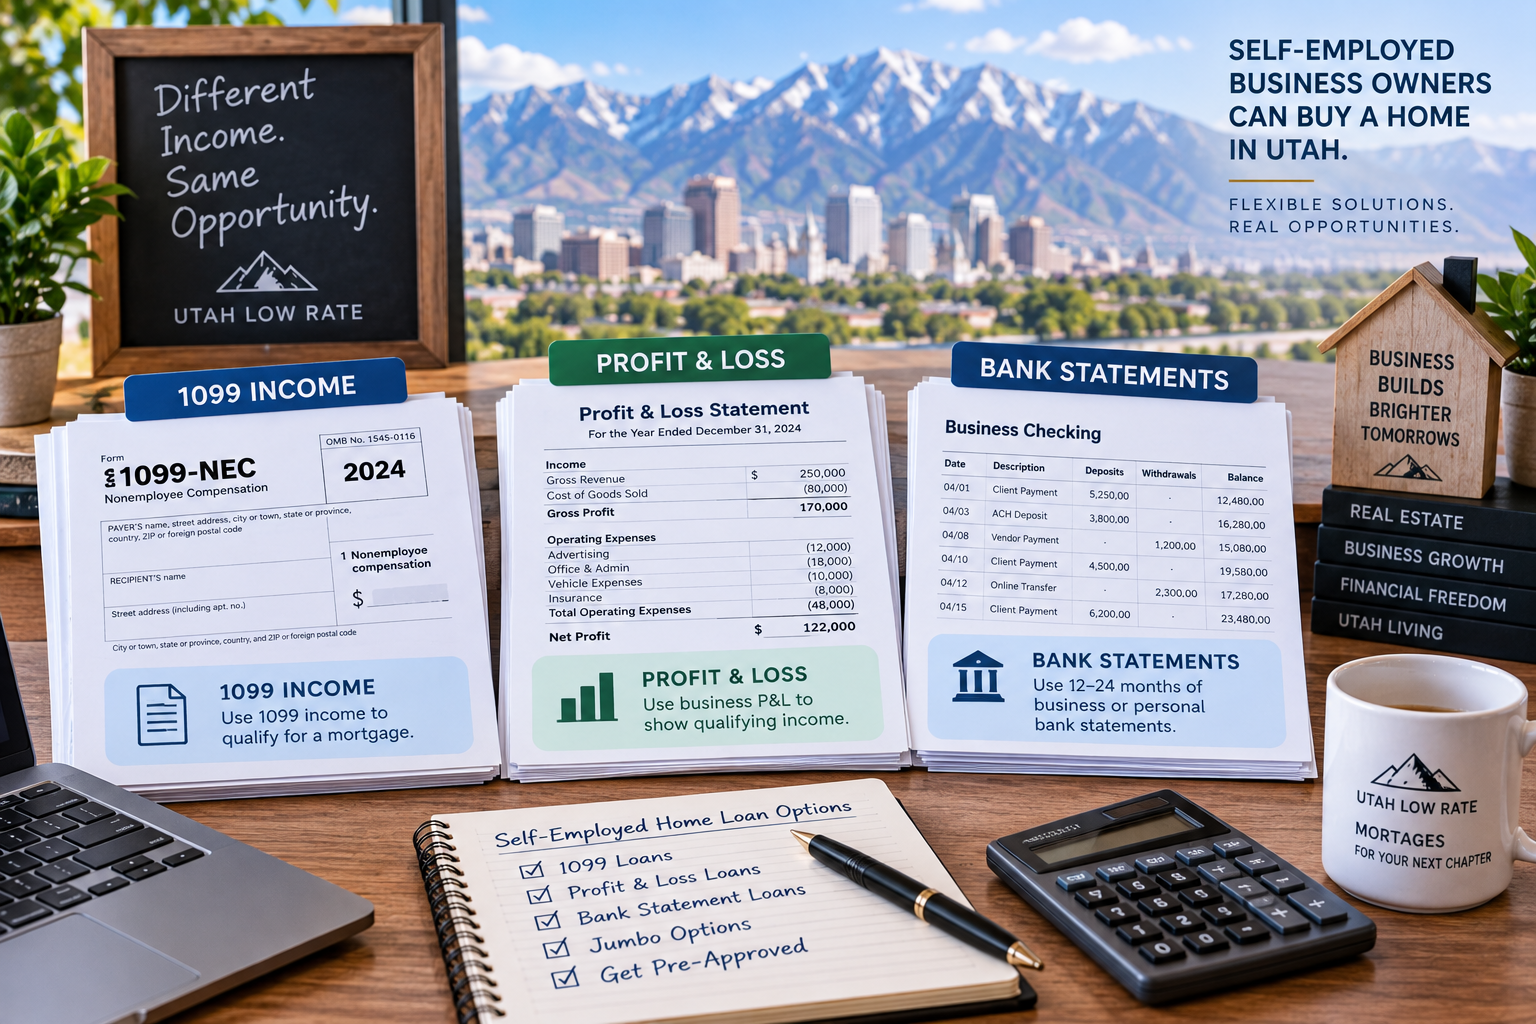
| Program | Primary Income Documentation | May Fit |
|---|---|---|
| Bank Statement | Eligible bank deposits | Business owners with strong recurring deposits |
| 1099 Mortgage | Eligible 1099 income | Independent contractors and 1099 professionals |
| Profit & Loss | Qualifying P&L | Business owners with strong current financials |
| Conventional | Traditional income documentation | Borrowers whose tax-return income qualifies |
There is no universally superior method.
The goal is to determine which eligible program appropriately documents your ability to repay while also comparing rates, fees, down payment, reserves and other loan requirements.
Non-QM Mortgage Loans for Self-Employed Borrowers
Non-QM means Non-Qualified Mortgage.
It does not mean no documentation, no underwriting or guaranteed approval.
Non-QM mortgages can provide alternative ways to document a borrower's financial capacity when the scenario does not fit traditional agency mortgage guidelines.
Depending on current program availability, self-employed Non-QM options may include:
- Bank Statement mortgages
- 1099 mortgages
- Profit and Loss mortgages
- Asset-based mortgages
- Asset-depletion programs
- Jumbo alternative-documentation mortgages
- Other specialized programs
Every loan remains subject to applicable lender and investor requirements.
Jumbo Mortgages for Self-Employed Utah Borrowers
Self-employed borrowers purchasing higher-value Utah homes may also require Jumbo Mortgage financing.
This is particularly relevant in markets such as:
- Park City
- Deer Valley
- Empire Pass
- Salt Lake City
- Holladay
- Cottonwood Heights
- Draper
- Alpine
- Highland
- Heber City
- Midway
- St. George
Traditional jumbo underwriting may analyze tax returns, business income, K-1 income, assets, liquidity and reserves.
Alternative-documentation jumbo mortgages may also be available for qualified borrowers whose income does not fit traditional jumbo underwriting.
For especially large transactions, review Super Jumbo Mortgage Loans in Utah and California.
DSCR Loans for Self-Employed Utah Real Estate Investors
Self-employed real estate investors have another potential option.
A DSCR Mortgage Loan in Utah generally focuses on the qualifying cash flow of an eligible investment property rather than primarily qualifying the borrower from personal employment income.
DSCR stands for Debt Service Coverage Ratio.
This financing can be useful for investors with:
- Multiple rental properties
- Complicated tax returns
- Multiple businesses
- Significant business deductions
- Income that varies from year to year
DSCR financing is generally intended for qualifying investment properties rather than owner-occupied primary residences.
Can Self-Employed Borrowers Get FHA Loans?
Yes. Being self-employed does not automatically prevent an eligible borrower from obtaining FHA financing.
Self-employed income must still satisfy applicable FHA and lender requirements.
FHA financing can be worth evaluating for qualified borrowers purchasing or refinancing an eligible primary residence.
Explore: FHA Loans in Utah
Can Self-Employed Veterans Get VA Loans?
Yes.
An eligible Veteran, active-duty service member or other VA-eligible borrower can potentially obtain VA financing while self-employed.
The borrower must satisfy applicable VA and lender requirements for documenting and analyzing self-employed income.
Explore Utah home financing options: Utah Mortgage Loans
What Documents Do Self-Employed Mortgage Borrowers Need?
Required documents depend heavily on the mortgage program.
You may be asked for some combination of:
- Personal tax returns
- Business tax returns
- IRS transcripts
- K-1 statements
- 1099 forms
- Personal bank statements
- Business bank statements
- Profit and Loss statements
- Balance sheets
- Business licenses
- CPA or tax-preparer documentation when applicable
- Asset statements
- Retirement or investment statements
- Identification
- Purchase contract
- Property information
An alternative-documentation mortgage does not mean a no-documentation mortgage.
It means the program may use a different approved method to evaluate income and the borrower's ability to repay.
How Much Can a Self-Employed Borrower Qualify For?
There is no single loan amount that applies to every self-employed borrower.
Mortgage qualification can depend on:
- Qualifying monthly income
- Existing monthly debts
- Credit profile
- Loan-to-value ratio
- Down payment or equity
- Available reserves
- Property type
- Occupancy
- Loan amount
- Income-documentation method
- Lender and investor requirements
Two business owners with identical gross revenue could potentially have very different qualifying results because their expenses, credit, assets, debts and income documentation are different.
That is why comparing documentation methods before choosing the loan program can be valuable.
Self Employed Mortgage Loans in Salt Lake City and the Wasatch Front
UtahLowRate.com works with self-employed borrowers throughout Salt Lake County and the Wasatch Front, including:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale and surrounding communities.
Business owners in these markets can compare conventional, bank statement, 1099, P&L, jumbo and other available mortgage programs based on their individual financial profiles.
Self Employed Mortgages in Park City and the Wasatch Back
Self-employed borrowers purchasing higher-value properties in Park City and the Wasatch Back may have additional considerations because of property values, jumbo loan amounts, second-home transactions and complex financial profiles.
UtahLowRate.com works with borrowers financing eligible properties throughout Park City, Deer Valley, Canyons Village, Empire Pass, Old Town, Kimball Junction, Heber City, Midway, Jordanelle, Hideout and Kamas.
Depending on the transaction, borrowers may compare traditional jumbo financing with alternative-documentation jumbo programs.
Self Employed Mortgage Loans in Utah County
Self-employed homebuyers and homeowners in Utah County can also explore multiple documentation methods.
Areas served include:
Lehi, Alpine, Highland, American Fork, Pleasant Grove, Orem, Provo, Saratoga Springs, Eagle Mountain, Spanish Fork and surrounding communities.
Business owners whose tax returns do not fully reflect their current cash flow may want to compare conventional qualification against available bank statement, 1099 and P&L programs.
Self Employed Mortgage Loans in St. George and Southern Utah
Self-employed borrowers in Southern Utah can explore mortgage programs for eligible homes in St. George, Washington, Ivins, Santa Clara, Hurricane and surrounding communities.
Available financing can include conventional, government-backed, jumbo, bank statement and other alternative-documentation programs, subject to borrower and property eligibility.
How to Compare Self-Employed Mortgage Options
1. Identify How You Earn Income
Determine whether your income is best documented through tax returns, bank deposits, 1099s, business financial statements, assets or rental-property cash flow.
2. Review Your Credit and Assets
Credit, down payment, equity and reserves can affect which programs are available.
3. Compare More Than One Income Method
Do not assume your tax-return calculation is your only option.
An eligible borrower may produce different qualifying results using conventional, bank statement, 1099 or P&L documentation.
4. Compare the Complete Mortgage
Consider the interest rate, APR, points, lender fees, down payment, reserves, mortgage insurance when applicable, prepayment terms when applicable and total financing structure.
5. Complete Pre-Approval Before Shopping
If you are purchasing a home, determining the appropriate income calculation before making an offer can provide a clearer picture of your available financing.
Frequently Asked Questions About Self Employed Mortgages in Utah
Can I get a mortgage in Utah if I am self-employed?
Yes. Qualified self-employed borrowers can obtain mortgages in Utah. Depending on the financial profile, options may include conventional, FHA, VA, jumbo, bank statement, 1099, P&L and other Non-QM mortgages.
Can I get a mortgage without tax returns in Utah?
Potentially. Certain alternative-documentation mortgage programs may qualify eligible borrowers using bank statements, 1099 income, Profit and Loss statements, assets or another permitted method instead of using personal tax returns as the primary income calculation.
Are bank statement loans only for self-employed borrowers?
Bank statement mortgage programs are commonly designed for self-employed borrowers and business owners. Exact eligibility requirements depend on the lender and program.
How many months of bank statements do mortgage lenders require?
Bank statement programs commonly use a specified history such as 12 or 24 months, although requirements vary by program.
Can a 1099 worker qualify for a mortgage?
Yes. A 1099 worker may potentially qualify through conventional underwriting or an eligible alternative-documentation 1099 mortgage program.
Can I use a Profit and Loss statement to qualify for a mortgage?
Certain alternative-documentation mortgage programs may permit an eligible Profit and Loss statement to be used as part of the qualifying-income analysis.
Can self-employed borrowers get jumbo mortgages in Utah?
Yes. Qualified self-employed borrowers may obtain jumbo financing. Income may be documented traditionally or through an eligible alternative-documentation jumbo program, depending on lender guidelines.
Can I qualify if I have only been self-employed for one year?
Potentially. Requirements vary by mortgage type and lender. Some programs may consider borrowers with shorter self-employment histories when applicable experience, income and other program requirements are satisfied.
Do self-employed borrowers pay higher mortgage rates?
Not simply because they are self-employed. Pricing depends on the mortgage program and factors such as credit, loan-to-value ratio, occupancy, property type, loan amount and documentation. Alternative-documentation programs can be priced differently from conventional mortgages.
What is the best mortgage for a self-employed borrower?
There is no single mortgage that is best for every self-employed borrower. The appropriate program depends on how income is earned and documented, along with credit, assets, debts, down payment, property and financing objectives.
Compare Self Employed Mortgage Options in Utah
If you own a business, work as an independent contractor or receive 1099 income, do not assume your tax return is the only way to qualify for a mortgage.
The first step is to determine which available income-documentation method appropriately represents your financial situation.
Daniel Paris
Utah Mortgage Broker
27+ Years of Mortgage Experience
UtahLowRate.com
801-604-4949
See If I Qualify | Explore Bank Statement Loans | Compare Utah Mortgage Programs
Important Mortgage Disclosure
Mortgage programs, interest rates, APRs, fees, loan amounts, loan-to-value limits, credit requirements, reserve requirements and documentation standards can change.
Alternative-documentation mortgage programs still require underwriting and verification. Program availability depends on lender and investor guidelines, borrower qualification, property eligibility and other requirements.
This information is for general educational purposes and is not a commitment to lend, loan approval, rate quote or guarantee of financing.

