
Home Loans with Daniel Paris
If you are looking for a Utah mortgage company to help finance a home purchase, refinance, investment property or luxury residence, UtahLowRate.com can help you compare mortgage options based on your actual financial situation.
Daniel Paris, Utah Mortgage Broker with UtahLowRate.com, has more than 27 years of mortgage lending experience helping homebuyers, homeowners, self-employed borrowers, real estate investors and high-net-worth borrowers evaluate mortgage financing throughout Utah.
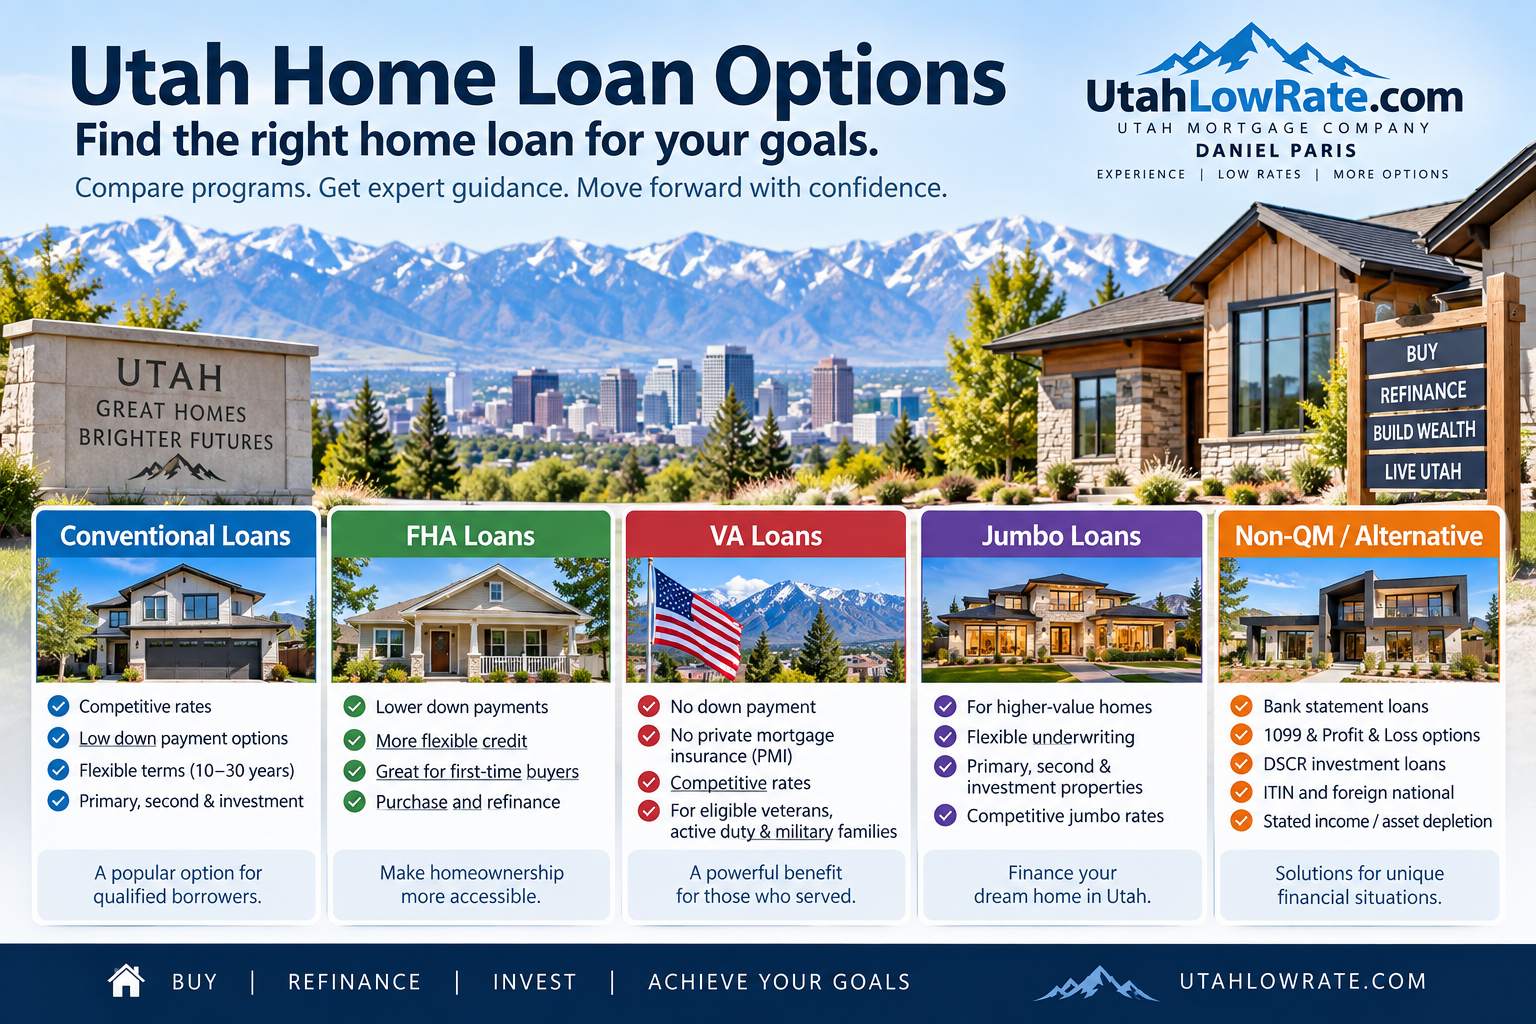
Available mortgage options may include Conventional, FHA, VA, Jumbo, Super Jumbo, Bank Statement, 1099, Profit & Loss, DSCR and other non-QM programs.
Daniel Paris | Utah Mortgage Broker
NMLS #243976
Call: 801-604-4949
Quick Answer: What Does a Utah Mortgage Company Do?
A Utah mortgage company helps borrowers finance the purchase or refinance of real estate. Depending on the company and borrower, financing may include conventional, FHA, VA, jumbo, refinance and alternative-documentation mortgages. UtahLowRate.com works through wholesale mortgage sources to help qualified Utah borrowers compare multiple programs rather than relying on a single mortgage option.
Utah Mortgage Company Quick Facts
| Topic | UtahLowRate.com |
|---|---|
| Mortgage Professional | Daniel Paris |
| Experience | 27+ years |
| Service Area | Utah statewide |
| Home Purchase Loans | Available |
| Mortgage Refinancing | Available |
| Conventional Loans | Available |
| FHA Loans | Available |
| VA Loans | Available for eligible borrowers |
| Jumbo Loans | Available |
| Super Jumbo Loans | Available |
| Bank Statement Loans | Available |
| 1099 Programs | Available |
| Profit & Loss Programs | Available |
| DSCR Loans | Available for eligible investment properties |
| Non-QM Loans | Available |
| Self-Employed Borrower Options | Available |
| Phone | 801-604-4949 |
| Website | UtahLowRate.com |
Loan availability and qualification depend on the borrower, property, transaction and applicable lender/investor guidelines.
What Is the Difference Between a Utah Mortgage Company, Bank and Mortgage Broker?
The terms mortgage company, mortgage lender, bank and mortgage broker are sometimes used interchangeably by consumers, but they can describe different ways of obtaining a home loan.
A bank generally offers mortgage products available through its own lending platform.
A mortgage broker can work with multiple wholesale mortgage lending sources, which can make it possible to compare different programs, guidelines and pricing structures.
UtahLowRate.com is operated around the mortgage-broker model, with Daniel Paris helping qualified borrowers evaluate financing from available wholesale lending sources.
Learn more about working with a Utah mortgage broker.
Mortgage Loans Available in Utah
The appropriate mortgage depends on much more than an advertised interest rate.
Income, employment, credit, assets, debts, down payment, property type, occupancy, loan amount, reserves and documentation can all affect the programs available to a borrower.
Here are several major categories to consider.
Conventional Mortgage Loans
Conventional mortgages are widely used for primary residences, second homes and qualifying investment properties.
Depending on the transaction and underwriting requirements, borrowers may have access to different down-payment, fixed-rate and adjustable-rate structures.
Learn more about Conventional Mortgage Loans in Utah.
FHA Loans
FHA-insured mortgages can provide another financing option for qualified Utah homebuyers.
FHA financing has its own requirements for credit, down payment, mortgage insurance, property eligibility and loan limits.
See the complete Utah FHA Loans guide.
VA Home Loans
Eligible veterans, active-duty service members and certain surviving spouses may be able to use VA home-loan benefits when purchasing or refinancing an eligible property.
VA financing has specific eligibility, entitlement, property and underwriting requirements.
Explore VA Mortgage Loans in Utah.
Jumbo Mortgage Loans
Higher-priced Utah homes may require financing above the applicable conforming loan limit.
Jumbo lending can be particularly relevant in higher-value markets such as Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Highland, Heber City and Midway.
Jumbo guidelines can differ significantly among lenders, making program comparison particularly important.
Explore Jumbo Mortgage Loans in Utah.
Super Jumbo Mortgage Loans
Very high-value properties can require specialized financing beyond traditional jumbo programs.
Depending on the borrower and transaction, available solutions may involve larger loan amounts, significant assets, complex income, substantial reserves or specialized underwriting.
See Super Jumbo Mortgage Loans in Utah and California.
Utah Mortgage Options for Self-Employed Borrowers
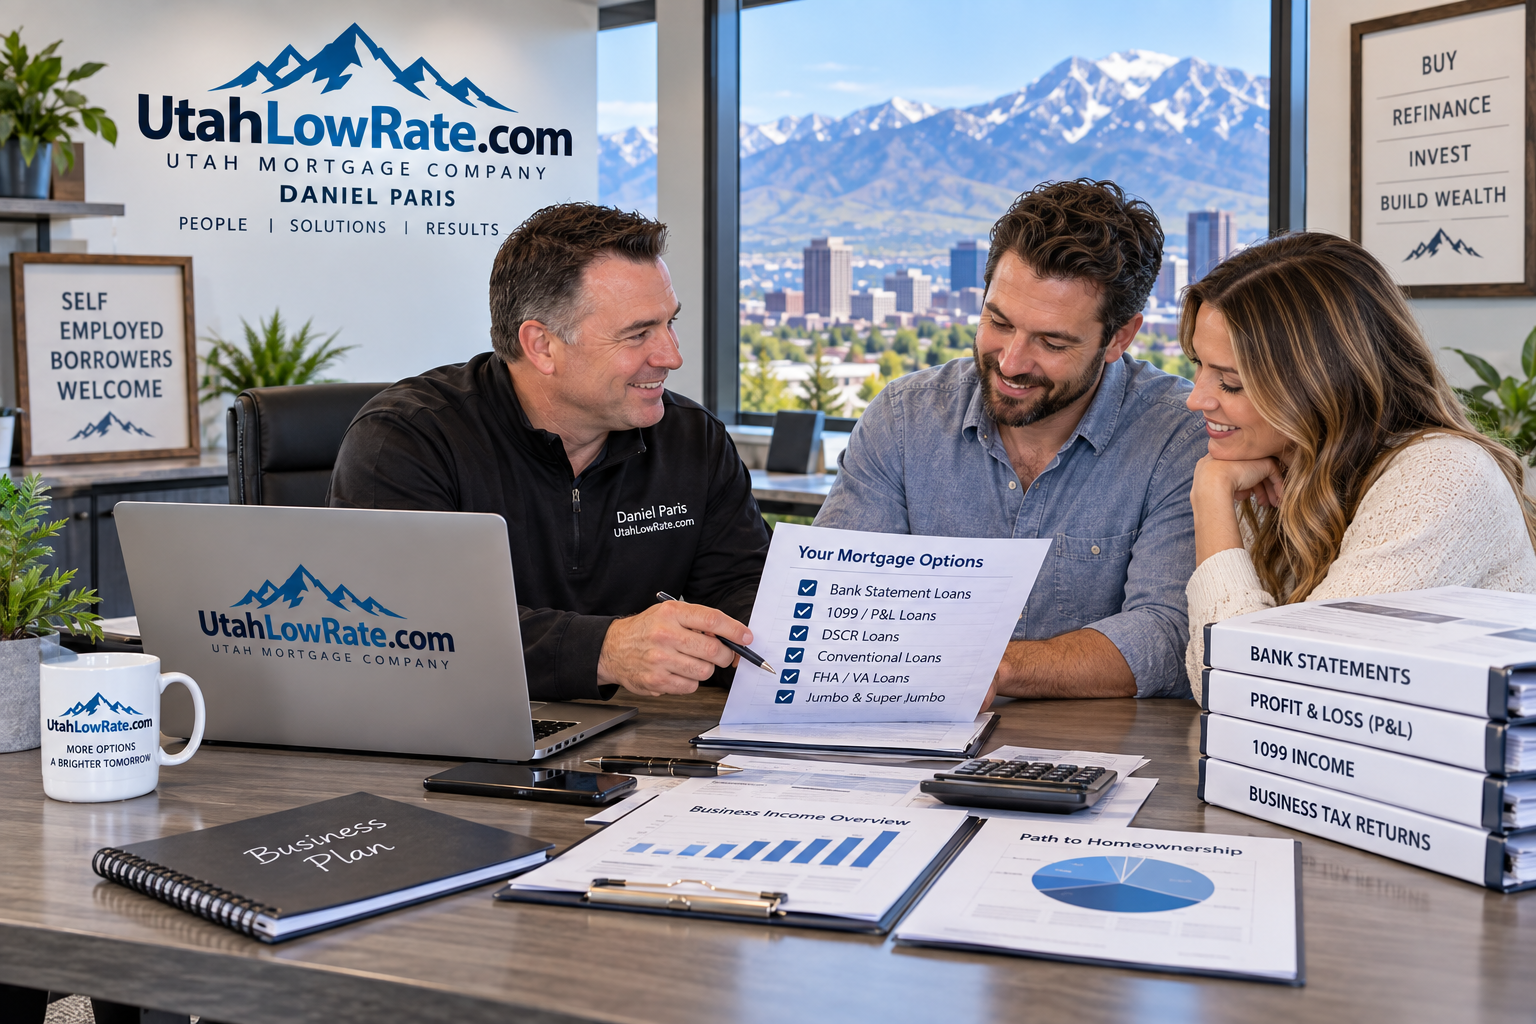
Business owners and self-employed borrowers do not always fit neatly into traditional mortgage-income calculations.
Tax deductions that are legitimate and useful for business purposes can sometimes reduce the taxable income used in traditional mortgage underwriting.
That does not necessarily mean a self-employed borrower cannot qualify.
Depending on the borrower's circumstances, potential financing methods can include traditional mortgages and alternative-documentation programs.
Bank Statement Loans
A bank statement mortgage may allow a qualified self-employed borrower to establish qualifying income using eligible deposits appearing on personal or business bank statements.
Learn about Bank Statement Loans in Utah.
Profit & Loss Mortgage Programs
Certain programs may use an eligible Profit & Loss statement as part of their income-documentation methodology.
Explore Profit and Loss Mortgage Loans in Utah.
Jumbo Bank Statement Loans
A self-employed borrower purchasing or refinancing a higher-value property may need both alternative income documentation and jumbo financing.
See Jumbo Bank Statement Loans in Utah.
Other Non-QM Mortgage Options
Depending on program availability and borrower eligibility, other Non-QM solutions may be available for borrowers whose income, assets or property do not fit standard agency underwriting.
The important question is not simply whether you are self-employed.
It is how your qualifying income can be documented under the programs currently available for your transaction.
Utah Mortgage Company for Real Estate Investors
Financing an investment property can require a different strategy from financing a primary residence.
Some investors qualify using traditional income documentation. Others may want to evaluate a loan based primarily on the property's rental cash flow.
DSCR Mortgage Loans
A Debt Service Coverage Ratio, or DSCR, mortgage generally evaluates an investment property's qualifying rental income relative to its housing obligation under the applicable lender's calculation.
This can provide an alternative to traditional borrower-income qualification for eligible investment properties.
Learn more about DSCR Mortgage Loans in Utah.
Buying a Home in Utah
Utah contains dramatically different housing markets, property values and property types.
UtahLowRate.com works with qualified borrowers throughout the state, including communities in:
Salt Lake County: Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman and surrounding communities.
Utah County: Provo, Orem, Lehi, American Fork, Pleasant Grove, Alpine, Highland, Saratoga Springs, Eagle Mountain, Spanish Fork and surrounding areas.
Summit and Wasatch Counties: Park City, Deer Valley, Canyons Village, Heber City, Midway, Jordanelle, Hideout, Kamas and surrounding communities.
Davis and Weber Counties: Layton, Farmington, Kaysville, Bountiful, Ogden and surrounding communities.
Washington County: St. George, Washington, Ivins, Santa Clara, Hurricane and surrounding Southern Utah communities.
The mortgage that works for a conventional home purchase in one market may be very different from financing a Park City luxury residence, a St. George second home or an investment property along the Wasatch Front.
How to Choose a Mortgage Company in Utah
Choosing a mortgage provider should involve more than comparing a single advertised interest rate.
Consider the complete financing structure.
1. Determine Which Loan Programs Are Available
A borrower should not automatically assume conventional financing is the only choice.
Compare relevant conventional, FHA, VA, jumbo and alternative-documentation programs based on your circumstances.
2. Compare the Rate and APR
Interest rate matters, but it should be evaluated together with points, lender fees and other applicable loan costs.
3. Compare Loan Terms
Consider whether a fixed-rate, adjustable-rate or other available structure fits your goals.
4. Understand Your Income Qualification
This is especially important for business owners, independent contractors, 1099 earners and other self-employed borrowers.
5. Review the Total Financing Scenario
Credit, income, assets, reserves, property, occupancy, down payment and loan amount should be evaluated together.
How Does the Utah Mortgage Process Work?
Although every transaction is different, the mortgage process generally follows several steps.
Step 1 — Discuss Your Goals
Start with the property, estimated purchase price or value, loan amount and financing objective.
Step 2 — Review Credit, Income and Assets
Determine how you are likely to qualify and which documentation method may apply.
Step 3 — Compare Mortgage Programs
Evaluate relevant loan programs based on your complete scenario.
Step 4 — Obtain Mortgage Pre-Approval
For a home purchase, a mortgage pre-approval can help establish an estimated financing range before making an offer.
Step 5 — Submit the Property and Loan for Underwriting
Once a property is under contract, the transaction proceeds through applicable disclosures, appraisal, documentation and underwriting.
Step 6 — Complete Final Approval and Closing
Final loan approval remains subject to satisfying applicable underwriting and closing requirements.
Mortgage Purchase, Refinance and Cash-Out Options
UtahLowRate.com works with borrowers pursuing several different financing objectives.
Home Purchase
Buying a primary residence, second home or eligible investment property.
Rate-and-Term Refinance
Replacing an existing mortgage with another loan when the new financing fits the homeowner's objectives.
Cash-Out Refinance
Eligible homeowners may be able to refinance and access a portion of their home equity, subject to program requirements.
Before refinancing, compare the new rate, APR, costs, loan term, monthly payment and long-term financial impact.
Why Work with Daniel Paris at UtahLowRate.com?
Daniel Paris has more than 27 years of mortgage lending experience working with homebuyers, homeowners, business owners, investors and borrowers with complex financing needs.
Instead of assuming every borrower should fit the same mortgage program, the objective is to identify available financing that fits the complete scenario.
That can be particularly useful when the transaction involves:
- Self-employment
- Complex income
- Jumbo financing
- Luxury real estate
- Investment properties
- Alternative income documentation
- Significant assets
- Multiple properties
- Refinancing
- Cash-out financing
Learn more about Daniel Paris and UtahLowRate.com.
Utah Mortgage Company FAQ
What is a Utah mortgage company?
A Utah mortgage company helps consumers obtain financing to purchase or refinance real estate. The available products and lending model depend on the company. A mortgage broker may work with multiple wholesale lending sources rather than offering only one lender's mortgage menu.
What types of mortgages are available in Utah?
Qualified borrowers may have access to Conventional, FHA, VA, Jumbo, Super Jumbo, Bank Statement, 1099, Profit & Loss, DSCR and other non-QM mortgage programs. Availability depends on the borrower, property, transaction and lender guidelines.
How do I find a mortgage company in Utah?
Compare mortgage providers based on available loan programs, rates, APRs, fees, experience, communication, income-documentation options and ability to handle your particular property and financing scenario.
Is UtahLowRate.com a mortgage broker?
UtahLowRate.com works through the mortgage-broker model, with Daniel Paris helping qualified borrowers evaluate programs available through wholesale mortgage lending sources.
Can a mortgage broker compare multiple lenders?
A mortgage broker can work with multiple participating wholesale lending sources and compare applicable programs for a qualifying borrower. Available lenders and programs depend on the specific transaction.
Can I get a Utah mortgage if I am self-employed?
Yes, self-employed borrowers may qualify for mortgages. Depending on the borrower's financial profile, possible options may include conventional financing, Bank Statement loans, 1099 programs, Profit & Loss programs, asset-based programs and other Non-QM mortgages.
Do you offer mortgages for investment properties?
Investment-property financing may be available through traditional investment mortgages, DSCR loans and other eligible programs. Requirements vary by property and lender.
Do you offer jumbo mortgages in Utah?
Yes. Jumbo mortgage options are available for qualified borrowers purchasing or refinancing higher-value Utah properties. Program guidelines vary by lender, loan amount, property, occupancy, credit, assets and other factors.
Does UtahLowRate.com provide mortgage loans throughout Utah?
UtahLowRate.com works with borrowers throughout Utah, including Salt Lake County, Utah County, Davis County, Weber County, Summit County, Wasatch County, Washington County and other Utah communities.
How do I get a Utah mortgage quote?
Start with your estimated property value or purchase price, down payment or equity, desired loan amount, occupancy, credit profile and income-documentation method. Daniel Paris can then review the scenario and discuss available mortgage options.
Talk With Daniel Paris About Your Utah Mortgage
Whether you are buying your first home, moving to another Utah property, purchasing a luxury residence, investing in rental real estate, refinancing or trying to qualify with self-employment income, the mortgage should be evaluated around your specific financial circumstances.
Daniel Paris
Utah Mortgage Broker
NMLS #243976
27+ Years of Mortgage Lending Experience
801-604-4949
UtahLowRate.com
Mortgage programs, rates, APRs, fees, loan amounts, credit requirements, LTV limits, reserve requirements, documentation standards and availability are subject to change. All financing is subject to borrower qualification, applicable lender/investor guidelines, underwriting, property eligibility and appraisal requirements. Information on this page is educational and does not constitute a commitment to lend, guarantee of approval or guarantee of any particular rate or terms.
Last Updated: September 2026

