
Content updated: .
Bank statement loans Salt Lake City borrowers use can provide an alternative way for self-employed homebuyers and homeowners to document mortgage income. Instead of relying primarily on taxable income shown on traditional tax returns, eligible programs may analyze qualifying deposits from personal or business bank statements.
This can be useful for business owners, entrepreneurs, independent contractors, consultants, real estate professionals and other self-employed borrowers whose tax returns may not fully reflect their recurring business cash flow.
Daniel Paris of UtahLowRate.com helps borrowers throughout Salt Lake City and Salt Lake County compare available bank statement mortgage programs for purchases, refinances, cash-out refinances and qualifying jumbo transactions.
Daniel Paris — Utah Mortgage Broker
NMLS #243976
801-604-4949
Explore Bank Statement Loans Throughout Utah
Request a Bank Statement Income Review
Quick Answer: How Do Bank Statement Loans Work in Salt Lake City?
A Salt Lake City bank statement loan may allow an eligible self-employed borrower to qualify using recurring deposits shown on personal or business bank statements.
Many programs review either 12 or 24 months of statements. The lender identifies eligible deposits and applies the program's income and expense calculation.
Credit, debts, assets, reserves, property type, occupancy, loan amount and loan-to-value ratio are also reviewed.
Bank statement mortgages are fully underwritten loans. They are not no-documentation or stated-income loans.
See Bank Statement Loan Requirements in Utah
Salt Lake City Bank Statement Loan Quick Facts
| Feature | Typical Structure |
|---|---|
| Designed primarily for | Self-employed borrowers |
| Income documentation | Eligible bank deposits |
| Statement period | Commonly 12 or 24 months |
| Personal statements | May be permitted |
| Business statements | May be permitted |
| Tax-return income | May not be the primary qualification method |
| Purchase | Available through qualifying programs |
| Rate-and-term refinance | May be available |
| Cash-out refinance | May be available |
| Jumbo financing | Available through select investors |
| Primary residence | Available through qualifying programs |
| Second home | Select programs |
| Investment property | Select programs |
| Credit requirements | Investor-specific |
| Maximum LTV | Program and borrower specific |
| Reserves | Often required |
| Underwriting | Full underwriting required |
Important: Guidelines vary by lender and investor and can change. Examples on this page are educational and should not be treated as universal qualification requirements.
What Is a Bank Statement Mortgage?
A bank statement mortgage is an alternative-documentation home loan designed primarily for eligible self-employed borrowers.
Traditional conventional underwriting often analyzes self-employment income using tax returns and other financial documents.
A bank statement program can take a different approach.
Depending on the program, the lender may analyze recurring deposits shown on:
- Personal bank statements
- Business bank statements
- 12 months of statements
- 24 months of statements
The lender then determines which deposits qualify as income and applies the required expense methodology when necessary.
The result is an estimated monthly qualifying income figure used with the borrower's other financial information.
For a statewide overview, read the Bank Statement Loans Utah guide.
Who May Consider Bank Statement Loans in Salt Lake City?
Bank statement financing may be worth exploring when a borrower has consistent self-employment cash flow but does not qualify for the desired mortgage amount using a traditional tax-return calculation.
Potential borrowers include:
- Business owners
- Entrepreneurs
- Independent contractors
- 1099 professionals
- Real estate agents and brokers
- Consultants
- Attorneys
- Physicians and dentists
- Construction company owners
- Contractors and tradespeople
- Technology consultants
- Marketing professionals
- Agency owners
- Online business owners
- Freelancers
Being self-employed does not automatically qualify someone for a bank statement mortgage.
The complete loan still needs to satisfy the selected investor's underwriting guidelines.
12-Month vs. 24-Month Bank Statement Loans Salt Lake City
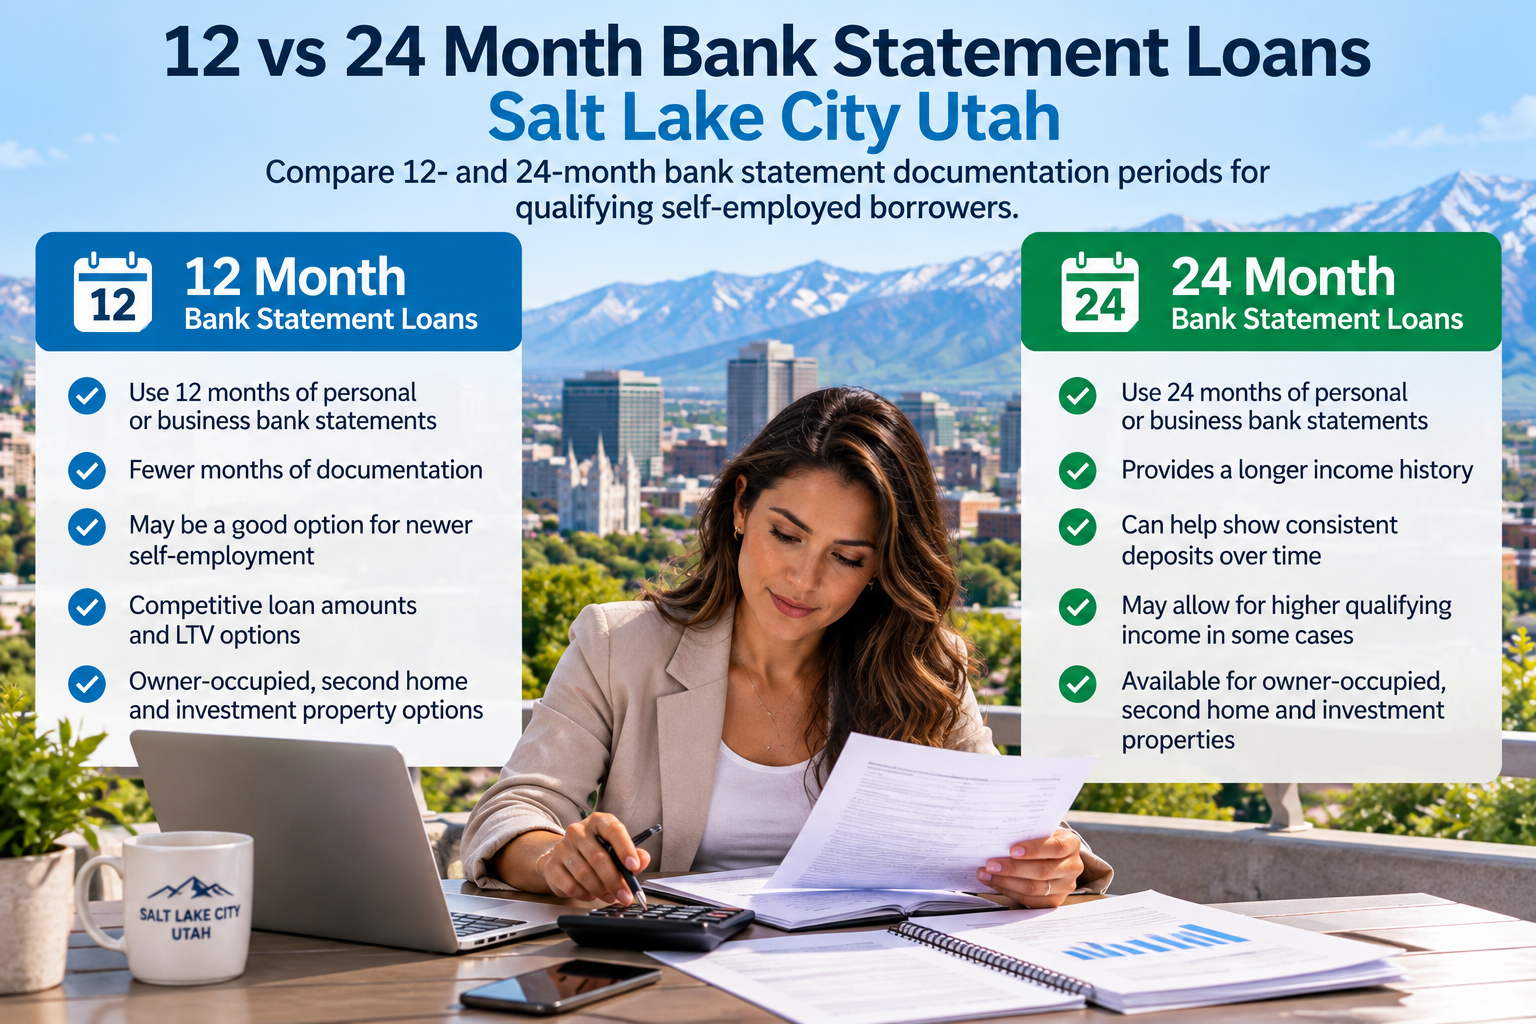
One of the first decisions is whether a borrower should be evaluated using 12 or 24 months of bank statements.
12-Month Bank Statement Loans
Some programs permit approximately 12 months of qualifying statements.
A 12-month analysis may better reflect current business activity when recent revenue differs from an older period.
Availability depends on the investor and borrower profile.
24-Month Bank Statement Loans
Other programs analyze approximately 24 months.
A longer period may help show income consistency and can smooth out seasonal changes in revenue.
Is 12 Months or 24 Months Better?
Neither option is automatically better.
For example, a business that has grown significantly during the past year may produce a different income average under a 12-month calculation than under a 24-month calculation.
A seasonal business could have the opposite situation.
The statements and program should be evaluated before choosing an underwriting strategy.
Estimate qualifying income with the Bank Statement Loan Income Calculator.
Personal vs. Business Bank Statements
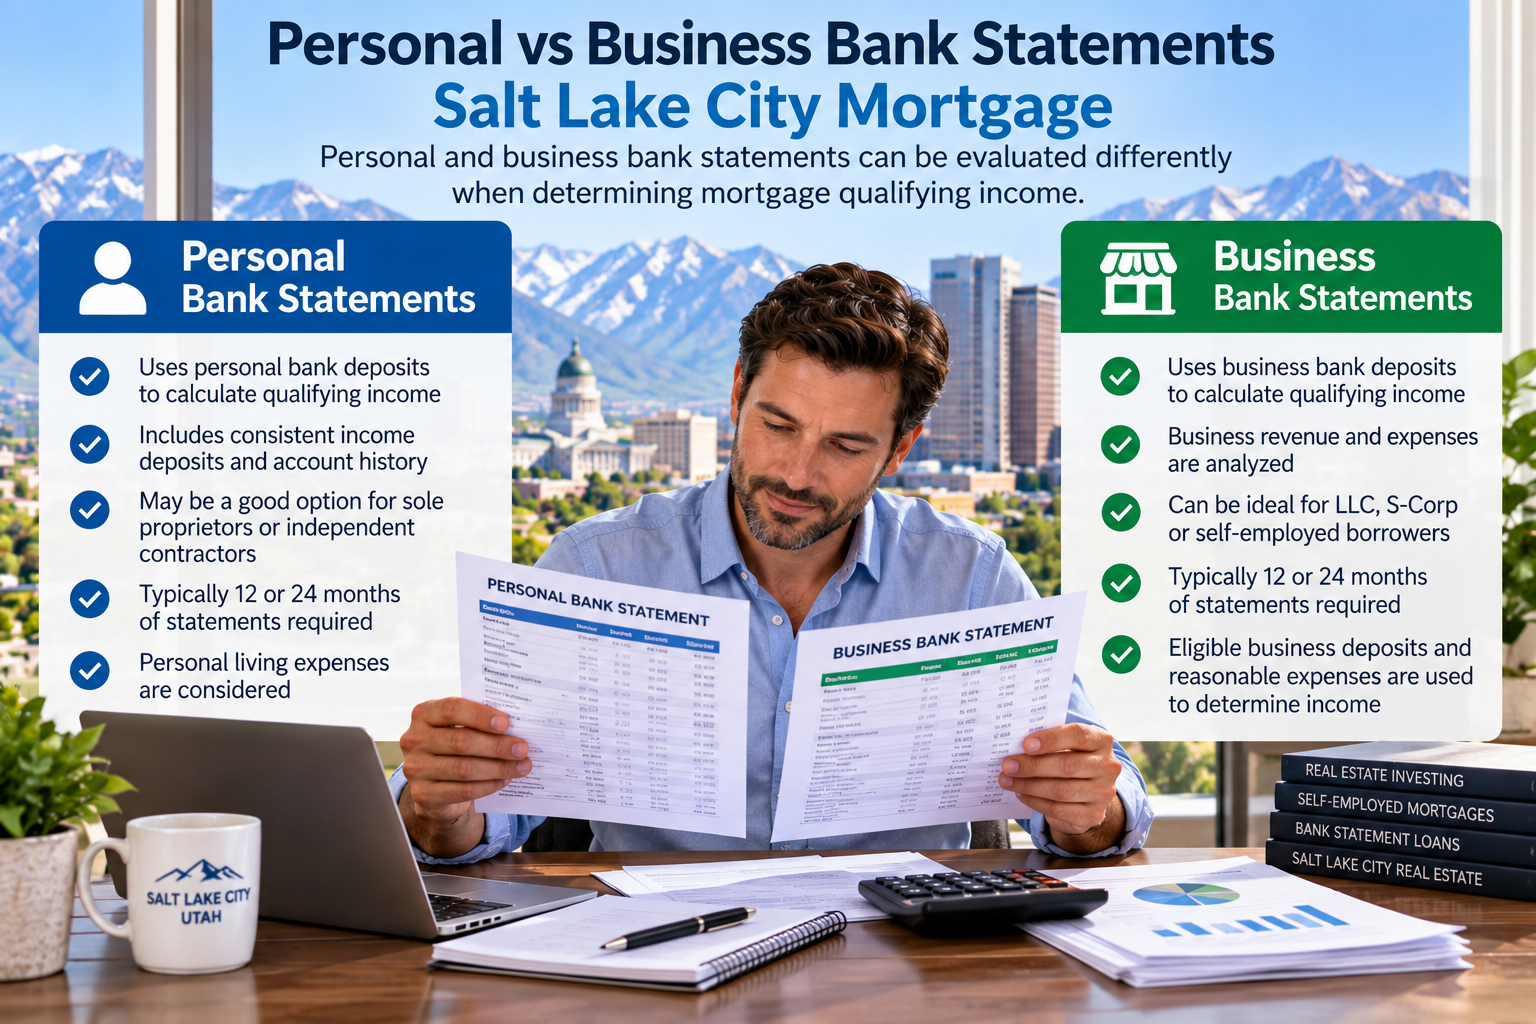
Another important question is which bank accounts should be used.
Personal Bank Statements
Certain programs permit personal statements when qualifying self-employment income is regularly deposited into a personal account.
The lender reviews the deposits and determines which transactions can be included under its guidelines.
Business Bank Statements
Business accounts generally contain gross business receipts.
Gross revenue, however, is not the same as personal qualifying income.
A business has expenses.
The lender therefore applies the expense calculation permitted by the selected program to determine how much eligible business revenue can potentially be treated as qualifying income.
Which Bank Statements Should I Use?
That depends on your business and banking structure.
Before submitting a mortgage application, it can be helpful to determine:
- Where business revenue is deposited
- Whether personal and business funds are separated
- Which deposits represent recurring revenue
- Whether transfers appear between accounts
- Which statement period produces an appropriate income history
- Which expense methodology applies
Choosing the right account can materially change the qualifying-income calculation.
How Is Bank Statement Mortgage Income Calculated?
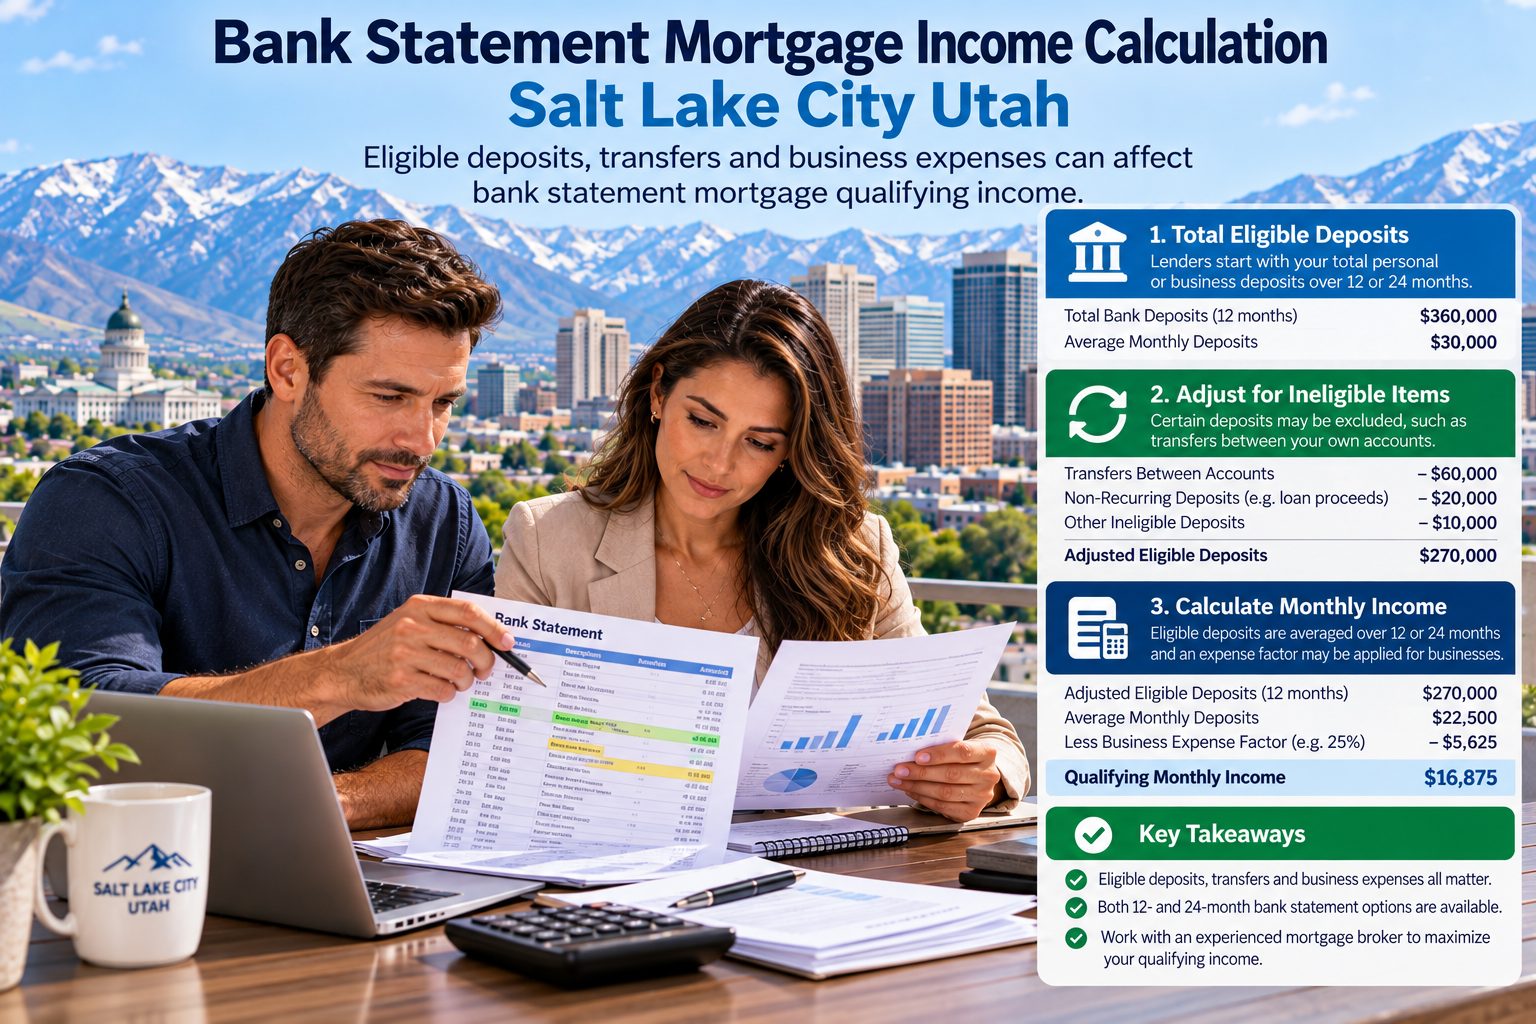
A simplified calculation begins with eligible deposits.
The process may look like this:
- Review the required 12 or 24 months of statements.
- Identify recurring deposits.
- Remove transfers between accounts.
- Remove deposits that do not qualify as income.
- Determine total eligible deposits.
- Calculate average eligible monthly deposits.
- Apply the investor's approved expense methodology.
- Determine estimated monthly qualifying income.
Salt Lake City Bank Statement Income Example
Assume a self-employed borrower has:
Average eligible business deposits: $30,000 per month
For an educational example, assume the applicable methodology results in 50% of those deposits being recognized as qualifying income.
$30,000 × 50% = $15,000 estimated monthly qualifying income
Request a Bank Statement Income Review
That does not mean every borrower depositing $30,000 per month automatically qualifies using $15,000.
Another program may use a different calculation.
Under certain qualifying programs and circumstances, an approved methodology could result in approximately 75% of eligible deposits being recognized. That percentage is not automatic and depends on the applicable investor guidelines and documentation.
Use the Bank Statement Loan Income Calculator for more examples.
Bank Statement Loan Requirements Salt Lake City Borrowers Should Know
There is no single qualification standard for every bank statement mortgage.
Requirements vary by lender, investor and transaction.
Bank Statements
Borrowers commonly provide 12 or 24 consecutive months of complete statements.
Self-Employment
The borrower generally must establish an eligible self-employment history and active business.
Credit
There is no universal credit-score requirement for every bank statement loan.
Available options can depend on:
- Credit history
- LTV
- Loan amount
- Occupancy
- Property type
- Mortgage history
- Reserves
- Overall borrower profile
Down Payment and Equity
Required equity varies by program.
For illustration:
| Maximum LTV | Corresponding Equity/Down Payment |
|---|---|
| 90% | 10% |
| 85% | 15% |
| 80% | 20% |
| 75% | 25% |
These figures simply show the mathematical relationship between LTV and equity. They do not mean every borrower can qualify at each LTV.
Mortgage Reserves
Some programs require borrowers to retain a certain amount of eligible liquid assets after closing.
Reserve requirements can increase with larger loan amounts or more complex transactions.
Property and Occupancy
Depending on the program, financing may be available for qualifying:
- Primary residences
- Second homes
- Investment properties
Eligibility varies by investor.
See the complete Bank Statement Loan Requirements Utah guide before preparing your documentation.
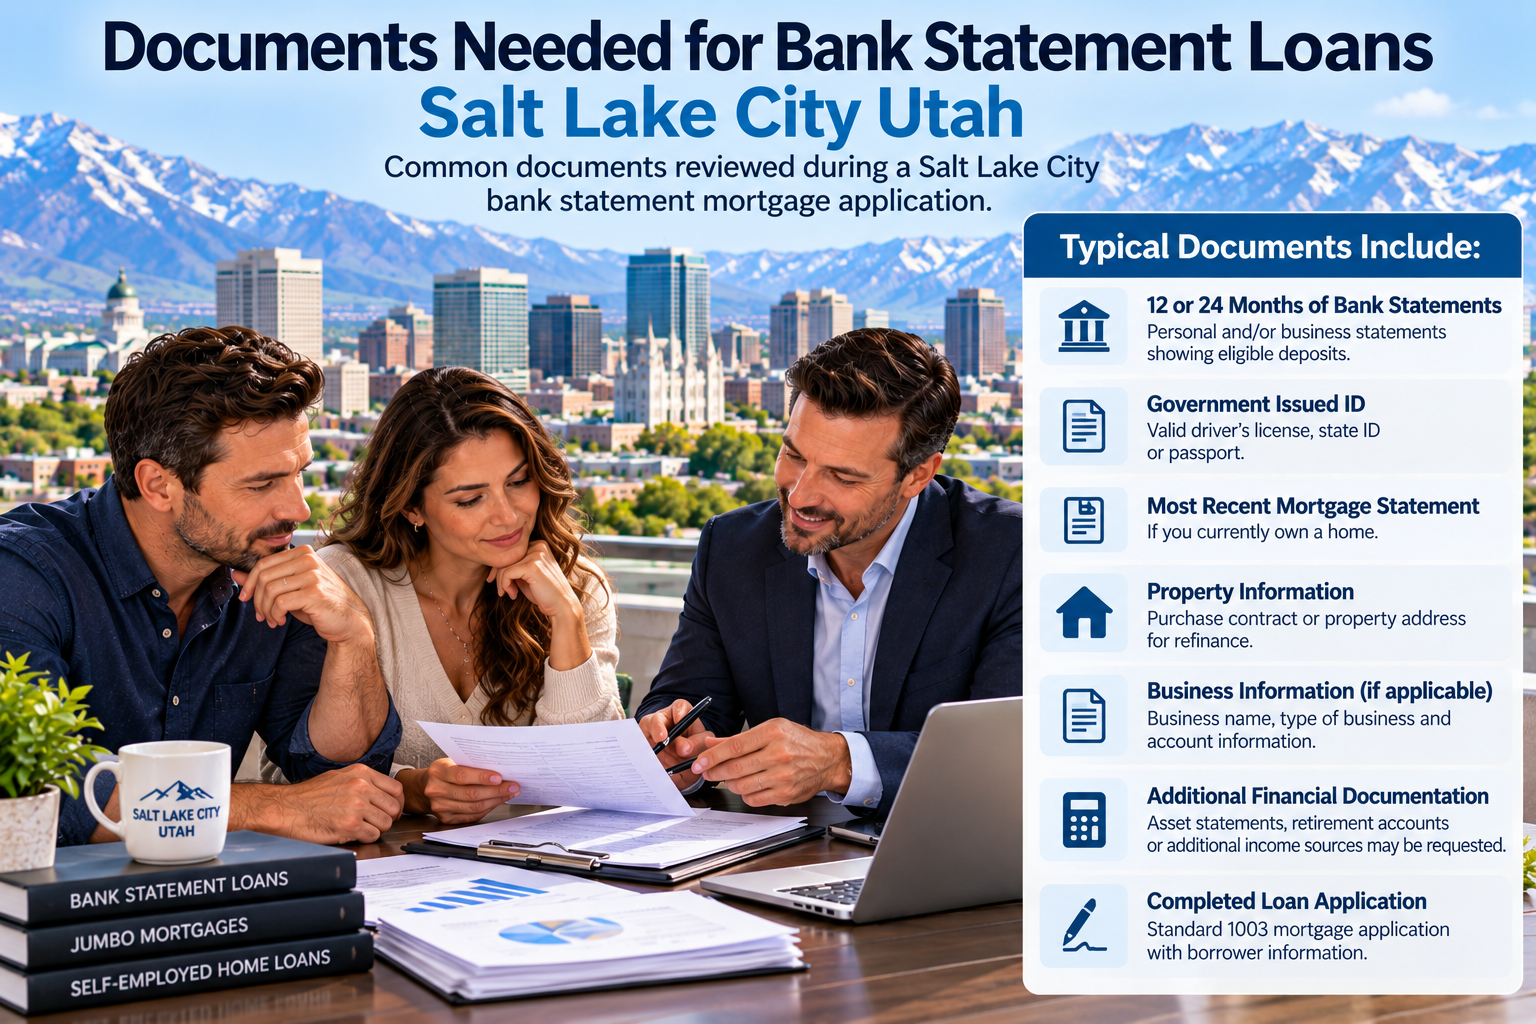
Documents Commonly Needed for a Salt Lake City Bank Statement Loan
Depending on the loan program, a borrower may need:
- 12 or 24 months of bank statements
- Government-issued identification
- Evidence of self-employment
- Business documentation
- Asset statements
- Housing history
- Explanations for unusual deposits
- Documentation for transfers
- Purchase agreement for a home purchase
- Property information
- Homeowners insurance information
- Additional documents required by underwriting
Preparing the documents early can make the preliminary income review easier.
Bank Statement Loans for Buying a Home in Salt Lake City
Bank statement financing may be used for eligible home purchases.
For a self-employed buyer, calculating income before making an offer can be especially useful.
Gross business revenue does not equal mortgage qualifying income.
A preliminary analysis can help determine:
- Estimated qualifying income
- Appropriate bank accounts
- 12-month vs. 24-month documentation
- Potential loan amount
- Potential LTV
- Approximate down payment
- Reserve requirements
- Whether jumbo financing may be needed
This can give a buyer a clearer financing range before shopping for a property.
Bank Statement Refinance Options in Salt Lake City
Bank statement loans are not limited to purchases.
Rate-and-Term Refinance
Eligible homeowners may be able to refinance an existing mortgage using bank statement income documentation.
Program requirements still apply.
Cash-Out Refinance
Some programs permit qualified self-employed homeowners to access equity through a bank statement cash-out refinance.
Maximum LTV, credit requirements, reserves, seasoning rules and available cash-out can differ by investor.
Jumbo Bank Statement Loans Salt Lake City
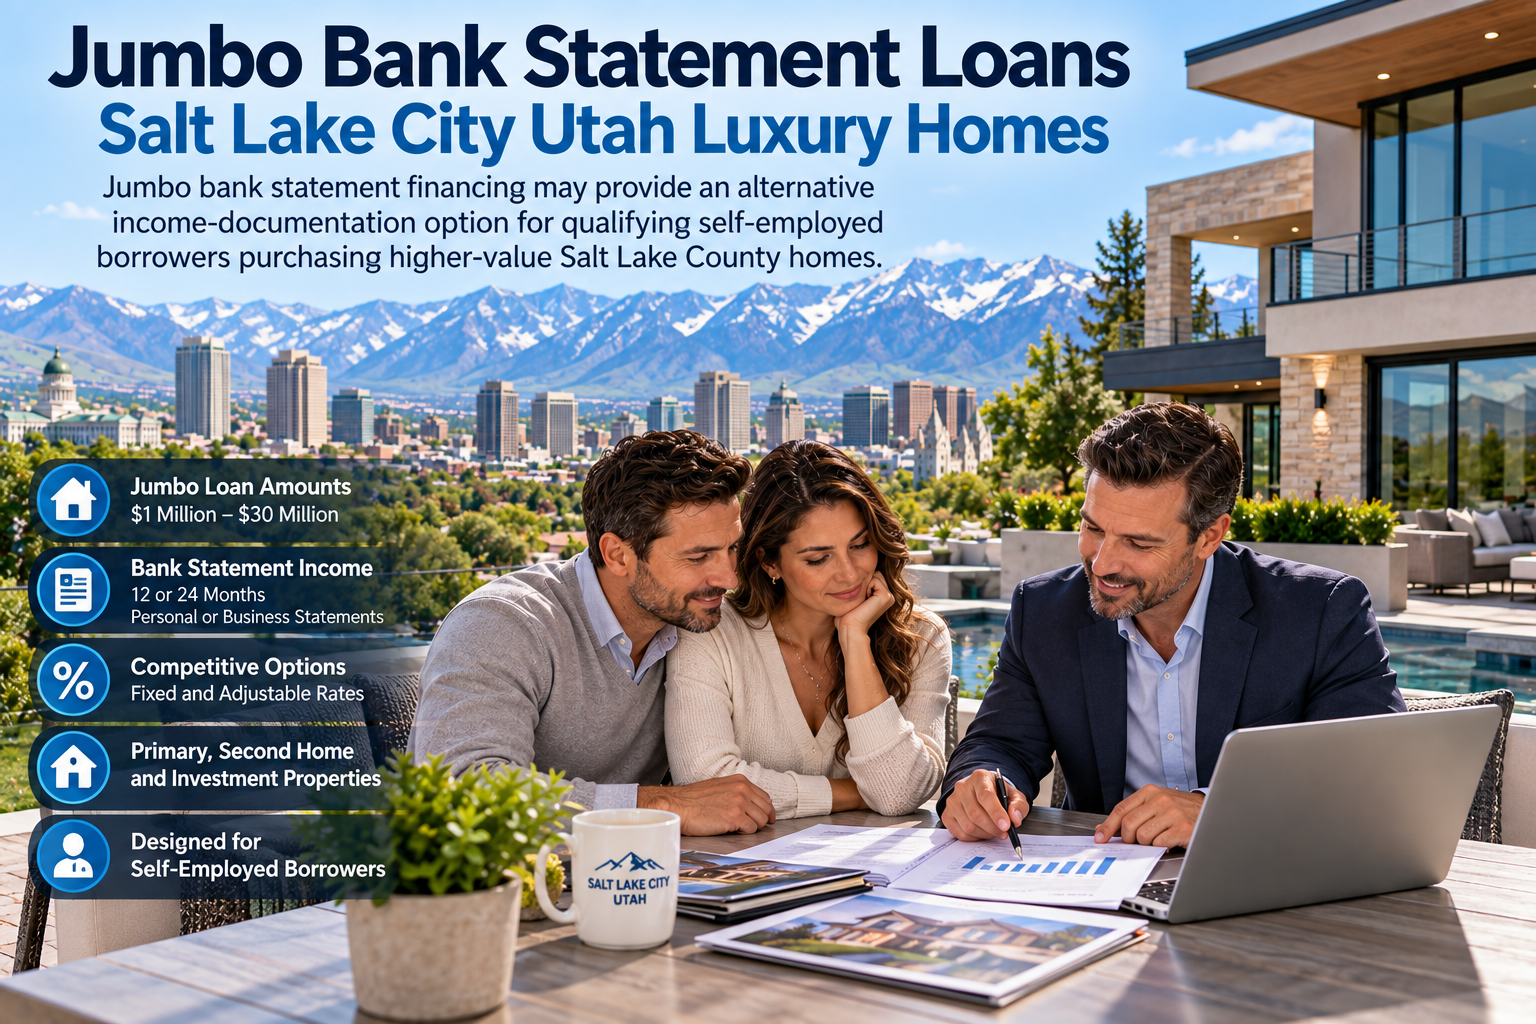
Higher-value properties can require larger mortgage amounts.
This can be especially relevant in parts of Salt Lake County such as Holladay, Cottonwood Heights, Draper, Sandy and other higher-priced neighborhoods.
Select wholesale investors offer jumbo bank statement mortgages for qualified self-employed borrowers.
Larger transactions can involve closer review of:
- Bank statement income
- Credit
- Assets
- Liquidity
- Mortgage reserves
- Property value
- Appraisal
- LTV
- Occupancy
- Loan amount
- Overall financial strength
For larger mortgage amounts, visit the Jumbo Bank Statement Loans Utah guide.
Bank Statement Loans Throughout Salt Lake County
UtahLowRate.com works with qualifying self-employed borrowers throughout Salt Lake County, including:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale, Midvale, Taylorsville and South Salt Lake.
Location does not determine loan eligibility. The borrower, property, loan amount and underwriting guidelines do.
Local property values can, however, affect the required loan size and whether conventional, jumbo or alternative-documentation financing should be evaluated.
Compare Other Utah Bank Statement Loan Markets
UtahLowRate.com has dedicated local resources for borrowers in several Utah markets.
Park City and Deer Valley
Higher property values in Park City and Deer Valley can create situations where borrowers need both alternative income documentation and jumbo financing.
See Bank Statement Loans Park City Utah.
Heber City and the Wasatch Back
Self-employed borrowers purchasing in Heber City, Midway, Jordanelle and nearby communities can review:
Bank Statement Loans Heber City Utah.
Statewide Utah
For the main program guide and statewide information, return to:
Bank Statement Loans vs. Conventional Mortgages
| Feature | Bank Statement Mortgage | Conventional Mortgage |
|---|---|---|
| Primary income documentation | Eligible bank deposits | Traditional income documentation |
| Tax-return income | May not be primary method | Common for self-employed analysis |
| 12/24-month statements | Common | Usually not primary income method |
| Business expense methodology | Investor specific | Traditional self-employment analysis |
| Credit review | Required | Required |
| Asset review | Required | Required |
| Underwriting | Required | Required |
| Best use case | Eligible borrowers needing alternative income documentation | Borrowers qualifying under traditional documentation |
A bank statement mortgage is not automatically preferable to a conventional loan.
If a borrower qualifies using conventional income documentation, both approaches can be compared.
For context, Fannie Mae's self-employed borrower guidelines explain how traditional conventional underwriting evaluates self-employment and business income.
Review Fannie Mae Self-Employed Borrower Guidelines
Why Bank Statement Mortgage Programs Can Produce Different Results
Bank statement mortgage guidelines vary between investors.
Two lenders could review the same bank statements and arrive at different potential qualifying-income figures.
Differences can involve:
- Eligible deposits
- 12 vs. 24 months of statements
- Personal vs. business accounts
- Business expense methodologies
- Self-employment history
- Credit requirements
- Maximum LTV
- Reserves
- Property eligibility
- Loan amounts
- Jumbo guidelines
- Cash-out restrictions
This is one reason it can be useful to evaluate the actual bank statements before selecting a program.
Common Bank Statement Loan Mistakes to Avoid
Counting Transfers as Income
Moving money between accounts generally does not create new business revenue.
Counting Every Deposit
Loan proceeds, refunds, transfers, asset-sale proceeds or other non-recurring deposits may not qualify.
Assuming Gross Revenue Equals Qualifying Income
Business revenue and personal qualifying income are not necessarily the same.
Choosing a Program Before Calculating Income
The same statements can produce different results under different approved methodologies.
Ignoring Reserves
Having enough money for the down payment does not necessarily mean the borrower satisfies post-closing reserve requirements.
Waiting Until After Making an Offer
A preliminary income analysis before shopping can identify potential documentation or qualification issues earlier.
How to Get a Bank Statement Loan in Salt Lake City
A practical process is:
1. Gather your statements.
Collect the personal or business statements that show your self-employment revenue.
2. Review your deposits.
Identify recurring revenue, transfers and unusual transactions.
3. Estimate qualifying income.
Determine how an eligible program may calculate monthly income.
4. Review credit, assets and debts.
Income is only one part of qualification.
5. Compare available programs.
Evaluate statement periods, expense methodologies, LTV, reserves and loan amounts.
6. Complete the mortgage application.
Provide the documents required for underwriting.
7. Complete property underwriting.
The property, appraisal, title and other transaction requirements must also be approved.
Salt Lake City Bank Statement Mortgage Resources
Continue through the UtahLowRate.com bank statement loan cluster:
- Bank Statement Loans Utah — Main Guide
- Bank Statement Loan Requirements Utah
- Bank Statement Loan Income Calculator
- Bank Statement Loan FAQ
- Jumbo Bank Statement Loans Utah
- Bank Statement Loans Park City Utah
- Bank Statement Loans Heber City Utah
Talk With a Salt Lake City Bank Statement Mortgage Broker
If traditional tax-return income does not reflect the cash flow your business generates, a bank statement mortgage may be worth evaluating.
Daniel Paris can review the basic scenario, including the type of statements available, estimated deposits, property, loan amount, credit profile and transaction type.
Daniel Paris
Utah Mortgage Broker
NMLS #243976
UtahLowRate.com
801-604-4949
Serving Salt Lake City, Salt Lake County and borrowers throughout Utah.
CTA: Get a Bank Statement Loan Review
Frequently Asked Questions About Bank Statement Loans Salt Lake City
Can I qualify for a Salt Lake City mortgage using bank statements?
Potentially. Certain mortgage programs allow eligible self-employed borrowers to establish qualifying income using eligible personal or business bank deposits instead of relying primarily on traditional tax-return income.
How many months of bank statements do I need?
Many bank statement programs review 12 or 24 months of statements. The required period depends on the lender, investor and borrower profile.
Can I use business bank statements?
Yes, under qualifying programs. Because business deposits usually represent gross revenue, an approved expense methodology is generally applied to determine potential qualifying income.
Can I use personal bank statements?
Certain programs permit personal bank statements when they appropriately document the borrower's qualifying self-employment income.
Do bank statement loans require tax returns?
Certain programs may calculate qualifying income primarily from eligible bank deposits rather than traditional tax-return income. Other documentation and full underwriting are still required.
What credit score is required for a bank statement loan?
There is no single minimum that applies to every program. Requirements depend on the investor, LTV, loan amount, property, occupancy, reserves and overall borrower profile.
Are bank statement loans available for jumbo mortgages?
Yes. Select investors provide jumbo bank statement financing for qualified self-employed borrowers who need higher loan amounts.
Can I get a bank statement cash-out refinance?
Certain programs permit cash-out refinancing. Maximum LTV, cash-out, credit, reserves and seasoning requirements vary by investor.
Are bank statement loans stated-income loans?
No. Bank statement mortgages require documented financial information and full underwriting. The lender analyzes actual bank statement activity rather than simply accepting a borrower-stated income amount.
Where can I learn more about bank statement loan requirements?
Read the Bank Statement Loan Requirements Utah guide or the Bank Statement Loan FAQ for more detailed information.
Request a Bank Statement Income Review · Call Daniel Paris: 801-604-4949

