
Content updated: September 29, 2026
Jumbo Refinance Loans Utah can help qualified homeowners replace an existing high-balance mortgage, change their interest rate or loan structure, shorten or extend the loan term, move between fixed and adjustable-rate financing, or access equity through a jumbo cash-out refinance.
Daniel Paris at UtahLowRate.com helps homeowners compare jumbo refinance programs for higher-value properties throughout Utah, including Salt Lake City, Park City, Deer Valley, Holladay, Cottonwood Heights, Draper, Alpine, Highland, Heber City, Midway and St. George.
Check My Jumbo Options or call 801-604-4949.
Because jumbo mortgages are not one-size-fits-all, credit, equity, income documentation, reserves, property type, occupancy and loan amount can all affect available refinance options.
Daniel Paris | Utah Mortgage Broker | UtahLowRate.com
Call: 801-604-4949
Request a Utah Jumbo Refinance Quote
Quick Answer: How Does a Jumbo Refinance Work in Utah?
A jumbo refinance loan in Utah replaces an existing mortgage with a new jumbo mortgage. Qualified homeowners may refinance to change their rate, term or loan structure, or they may choose a cash-out refinance to access eligible home equity.
Jumbo underwriting requirements vary by lender. Credit score, property value, loan-to-value ratio, reserves, income documentation, occupancy and requested loan amount can affect both eligibility and pricing.
Key Facts About Jumbo Refinance Loans Utah
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Typical Jumbo Refinance Consideration |
|---|---|
| Transaction | Rate-and-term or cash-out refinance |
| Loan size | Above applicable conforming limits or within lender-specific jumbo parameters |
| Property | Higher-value residential real estate |
| Occupancy | Primary, second home or eligible investment property, depending on program |
| Income | Traditional or eligible alternative documentation |
| Credit | Requirements vary by lender and loan amount |
| Equity | Maximum LTV varies by program |
| Reserves | Often required and may increase with loan size |
| Appraisal | Generally required |
| Loan structures | Fixed-rate and ARM options may be available |
| Large balances | Super jumbo options may be available for qualified borrowers |
Program availability and underwriting requirements vary and are subject to change.
What Is a Jumbo Refinance Loan?
A jumbo refinance is a mortgage refinance involving a loan amount that falls outside applicable conforming loan parameters or otherwise meets a lender's definition of jumbo financing.
Rather than using a standard conforming mortgage program, the homeowner may need financing from a lender or investor that specifically underwrites larger mortgage balances.
Jumbo underwriting can evaluate:
- Credit history
- Loan-to-value ratio
- Property value
- Income and employment
- Liquid assets
- Post-closing reserves
- Existing mortgage history
- Property type
- Occupancy
- Loan amount
- Debt-to-income ratio
- Other real estate owned
For an overview of high-balance financing, visit our Jumbo Mortgage Utah guide.
Jumbo Refinance Loans Utah: Rate-and-Term Refinancing
A rate-and-term jumbo refinance generally replaces an existing mortgage without the borrower taking substantial equity from the property.
Homeowners may consider this strategy when they want to:
- Change their mortgage interest rate
- Change the remaining loan term
- Move from an adjustable-rate mortgage to a fixed-rate loan
- Move from a fixed mortgage into an ARM
- Restructure an existing jumbo mortgage
- Replace temporary or short-term financing
- Consolidate eligible mortgage liens
- Change their overall mortgage strategy
A lower interest rate does not automatically make refinancing worthwhile.
The more useful question is whether the financial benefit of the new mortgage justifies its closing costs and fits the homeowner's expected ownership period and financial objectives.
Calculate the Jumbo Refinance Break-Even Point
A simple calculation is:
Estimated refinance costs ÷ estimated monthly savings = approximate break-even period
For example, if refinancing costs $8,000 and reduces the mortgage payment by $400 per month:
$8,000 ÷ $400 = 20 months
If the homeowner expects to keep the new mortgage substantially longer than 20 months, the transaction may deserve further analysis.
This is only a simplified example. Taxes, insurance, prepaid interest, loan-term changes, opportunity costs and other factors can affect the actual economics.
Jumbo Cash-Out Refinance Loans in Utah
A jumbo cash-out refinance allows a qualified homeowner to replace an existing mortgage with a larger mortgage and receive eligible equity as cash at closing.
Homeowners may consider cash-out refinancing for purposes such as:
- Home improvements
- Major renovations
- Investment opportunities
- Debt restructuring
- Liquidity needs
- Education expenses
- Business purposes
- Real estate acquisitions
- Building financial reserves
The amount of cash available depends on the home's appraised value, existing liens, requested loan amount and lender's maximum permitted LTV.
Learn more about Cash-Out Refinance options.
Jumbo Cash-Out Example
Assume a Utah homeowner has:
Estimated property value: $2,500,000
Existing mortgage: $1,100,000
New mortgage: $1,500,000
Before closing costs and other adjustments, the difference between the new mortgage and the existing loan would be approximately $400,000.
This example is for illustration only. Actual proceeds depend on appraisal, payoff figures, LTV restrictions, closing costs and underwriting.
How Much Equity Do I Need for a Jumbo Refinance in Utah?
There is no universal LTV requirement that applies to every jumbo refinance.
Maximum loan-to-value ratios can change based on:
- Loan amount
- Credit score
- Rate-and-term versus cash-out
- Primary residence versus second home
- Investment property
- Property type
- Number of financed properties
- Documentation method
- Reserve levels
- Overall borrower profile
A borrower refinancing a $1 million mortgage may have access to different guidelines than someone seeking a $5 million, $10 million or larger mortgage.
That is one reason comparing multiple wholesale jumbo programs can be important.
What Credit Score Is Needed for a Utah Jumbo Refinance?
There is no single credit-score requirement for all Jumbo Refinance Loans Utah.
Jumbo lenders establish their own underwriting guidelines and pricing tiers.
In general, stronger credit may provide access to:
- More competitive pricing
- Higher permitted LTVs
- Larger loan amounts
- More program choices
A lower score does not automatically mean a jumbo refinance is impossible. The entire transaction needs to be evaluated.
Credit should be considered together with equity, assets, reserves, income, property type and requested loan amount.
Income Requirements for Jumbo Refinance Loans Utah
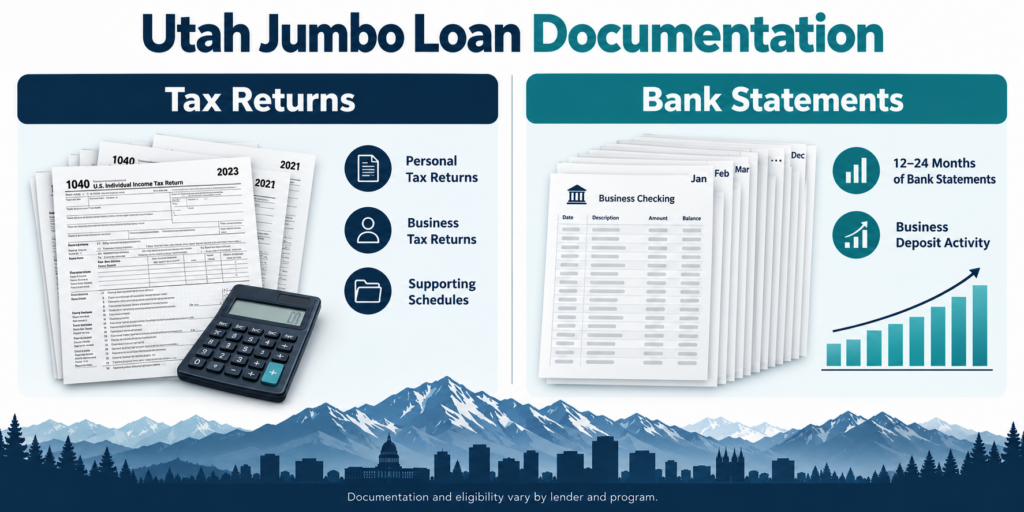
Traditional jumbo mortgage underwriting may document income using items such as:
- W-2s
- Pay stubs
- Tax returns
- Employment verification
- Business tax returns
- K-1s
- Asset statements
- Other applicable financial documentation
But not every high-net-worth or self-employed homeowner fits traditional underwriting.
UtahLowRate.com also works with alternative mortgage programs for qualified borrowers whose financial profile requires another approach.
Jumbo Refinance Loans for Self-Employed Utah Homeowners
Business owners frequently have significant income, assets and home equity while showing lower taxable income because of legitimate business deductions.
Depending on the program, a self-employed borrower may be able to explore:
- Bank statement mortgages
- Personal bank statement programs
- Business bank statement programs
- Profit & Loss mortgage programs
- Asset-depletion programs
- Non-QM jumbo mortgages
- Other alternative-documentation programs
Qualified business owners can explore our Bank Statement Loans Utah guide.
For higher loan balances, see Jumbo Bank Statement Loans Utah.
Super Jumbo Refinance Loans in Utah
Some Utah properties require financing well beyond ordinary jumbo mortgage sizes.
This can occur with luxury residences, estates, resort properties and high-value second homes in markets such as Park City, Deer Valley, Holladay, Alpine and other affluent Utah communities.
Qualified borrowers seeking especially large mortgage balances can explore Super Jumbo Mortgage Loans Utah.
Depending on current lender programs and borrower qualifications, super jumbo financing may provide solutions for multimillion-dollar mortgage transactions.
Larger loan amounts generally make factors such as liquidity, reserves, net worth, property marketability and overall borrower strength increasingly important.
Fixed-Rate vs. ARM Jumbo Refinance
A jumbo refinance does not necessarily have to be a 30-year fixed-rate mortgage.
Depending on available programs, borrowers may compare fixed-rate mortgages with adjustable-rate mortgages.
Fixed-Rate Jumbo Refinance
A fixed-rate mortgage provides a rate that remains fixed according to the loan terms.
This may appeal to homeowners who prioritize predictable principal-and-interest payments and expect to keep the property or mortgage for a longer period.
Jumbo ARM Refinance
An adjustable-rate mortgage typically provides an initial fixed-rate period followed by future adjustments according to the loan terms.
An ARM may deserve consideration when a borrower:
- Expects to sell the property
- Anticipates another refinance
- Has a shorter expected mortgage horizon
- Wants to compare initial ARM pricing with fixed-rate alternatives
The appropriate structure depends on the borrower's objectives and risk tolerance.
Jumbo Refinance for Park City and Deer Valley Homes
Park City and Deer Valley contain some of Utah's highest-value residential real estate.
Jumbo refinancing can be particularly relevant for:
- Ski-in/ski-out residences
- Luxury condominiums
- Resort-area homes
- Second homes
- Mountain estates
- Properties in gated communities
- High-value primary residences
Areas may include Deer Valley, Empire Pass, Old Town, Canyons Village, Promontory, Prospector, Kimball Junction and surrounding Summit County communities.
Higher-value or unique properties may require more specialized appraisal and underwriting review than a typical conforming property.
Jumbo Refinance Loans in Salt Lake City and Salt Lake County
Higher-value properties throughout Salt Lake County may also require jumbo financing.
UtahLowRate.com works with qualified homeowners in:
Salt Lake City, Holladay, Millcreek, Murray, Cottonwood Heights, Sandy, Draper, South Jordan, West Jordan, Riverton, Herriman, Bluffdale, Midvale and surrounding communities.
Luxury properties in areas such as Holladay, Cottonwood Heights and Draper may require jumbo or super jumbo financing depending on the requested mortgage amount.
Jumbo Refinance Loans in Utah County
High-value housing is also found throughout Utah County.
Jumbo refinance opportunities may apply to qualified homeowners in:
- Alpine
- Highland
- Lehi
- American Fork
- Pleasant Grove
- Provo
- Orem
- Saratoga Springs
- Eagle Mountain
- Spanish Fork
Custom homes and larger properties in Alpine and Highland can be particularly relevant to jumbo financing.
Jumbo Refinance Loans in Heber City and Wasatch County
Heber City, Midway and the Jordanelle area contain primary residences, second homes, vacation properties and luxury real estate that may require jumbo financing.
Homeowners in Wasatch County may use a jumbo refinance to restructure existing financing, change mortgage terms or access eligible equity.
Property type and occupancy can affect available programs.
Jumbo Refinance Loans in St. George and Southern Utah
Southern Utah's higher-value residential market includes St. George, Washington, Ivins, Santa Clara, Hurricane and surrounding communities.
Qualified homeowners with luxury residences, second homes and other higher-value properties may consider jumbo refinancing when restructuring existing mortgage debt or accessing equity.
Investment Property: Should You Use a Jumbo Loan or DSCR Loan?
Owners refinancing a high-value rental property may have more than one financing path.
A traditional jumbo investment-property mortgage may evaluate the borrower's personal income, debts, credit, assets and property.
A DSCR mortgage takes a different approach. Qualification generally focuses more heavily on the investment property's qualifying rental income relative to its mortgage-related obligation.
For investors, compare both strategies when appropriate.
Explore the Utah DSCR Loan Cluster
Start with the DSCR Mortgage Loans Utah guide.
Related DSCR topics include:
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Purchase Loans Utah
- DSCR Refinance Loans Utah
- DSCR Cash-Out Refinance Utah
- Interest-Only DSCR Loans Utah
- DSCR Loans for LLCs Utah
- DSCR vs. Conventional Investment Loans Utah
- DSCR Loans Salt Lake City
- DSCR Loans Park City
- DSCR Loans St. George
Important: Link each item above to its corresponding published DSCR cluster URL once that page is live. Do not create links to unpublished URLs merely for SEO.
Jumbo Refinance vs. DSCR Refinance
| Feature | Jumbo Refinance | DSCR Refinance |
|---|---|---|
| Primary use | High-balance residential financing | Investment-property financing |
| Primary residence | Potentially eligible | Generally no |
| Second home | Potentially eligible | Generally no |
| Investment property | Program dependent | Primary purpose |
| Personal income | Commonly evaluated | Often not the primary qualification method |
| Rental cash flow | May be considered | Central underwriting factor |
| Cash-out | May be available | May be available |
| Entity ownership | Program dependent | Common in eligible programs |
Investors should compare the complete cost and underwriting structure rather than choosing a loan solely because one documentation method appears easier.
Documents Commonly Needed for a Jumbo Refinance
Documentation varies by program, but homeowners should be prepared to provide information about the borrower and property.
Common documentation may include:
Income
Pay stubs, W-2s, tax returns or applicable self-employment documentation.
Assets
Bank, brokerage, retirement and other eligible asset statements.
Existing Mortgage
Current mortgage statement and information about additional property liens.
Insurance
Evidence of acceptable homeowners insurance and other applicable coverage.
Property
A new appraisal is commonly required.
Other Real Estate
Borrowers who own multiple properties may need mortgage, insurance, tax, lease or other documentation for those properties.
Alternative-documentation programs can have substantially different requirements.
How Are Jumbo Refinance Rates Determined?
There is no single Utah jumbo refinance rate.
Pricing can depend on:
- Credit score
- Loan amount
- Property value
- LTV
- Occupancy
- Property type
- Fixed versus ARM structure
- Loan term
- Cash-out versus rate-and-term
- Documentation type
- Points or lender credits
- Market conditions
Compare the interest rate, APR, points, lender fees and total closing costs rather than focusing on the advertised rate alone.
Visit Utah Mortgage Rates for additional rate information.
When Does Refinancing a Jumbo Mortgage Make Sense?
A refinance may deserve consideration when it helps accomplish a specific financial objective.
Examples include:
Reducing Interest Expense
A homeowner may refinance when a new mortgage provides sufficiently better economics after considering transaction costs.
Changing the Loan Term
A shorter term may increase the monthly payment while potentially reducing total interest expense.
A longer term may reduce the required monthly principal-and-interest payment but can increase total interest over time.
Moving From an ARM to Fixed Financing
Some homeowners refinance before an ARM begins adjusting.
Changing From Fixed to an ARM
A homeowner with a shorter expected ownership period may want to compare an ARM with fixed-rate financing.
Accessing Equity
Cash-out refinancing can convert a portion of accumulated home equity into available funds.
Replacing Temporary Financing
Borrowers who initially used bridge or other short-term financing may eventually want permanent jumbo financing.
When Might a Jumbo Refinance Not Make Sense?
Refinancing is not automatically beneficial.
Potential reasons to keep an existing mortgage include:
- The current rate is substantially below available rates
- Closing costs outweigh expected savings
- The homeowner plans to sell soon
- The refinance substantially extends the repayment period
- Cash-out costs are too high relative to alternatives
- The borrower would lose favorable existing loan terms
A mortgage comparison should consider both immediate payment changes and longer-term costs.
How to Refinance a Jumbo Mortgage in Utah
Step 1: Define the Goal
Determine whether the objective is a lower rate, different term, ARM/fixed conversion, cash-out or another restructuring goal.
Step 2: Estimate Property Value and Equity
Your current value and mortgage balance help determine estimated LTV.
Step 3: Review Credit and Income
Determine which jumbo programs fit your credit and documentation profile.
Step 4: Review Assets and Reserves
Larger jumbo loans may have substantial reserve requirements.
Step 5: Compare Wholesale Jumbo Programs
Compare available lenders for rate, APR, points, fees, LTV, reserves and underwriting requirements.
Step 6: Complete the Application
Submit the required borrower, income, asset and property documentation.
Step 7: Complete the Appraisal and Underwriting
The lender reviews the borrower, collateral and complete loan file.
Step 8: Review the Final Loan Economics
Before closing, evaluate the new payment, costs, APR, loan term and expected break-even period.
Start Your Jumbo Refinance Application
Why Work With a Utah Mortgage Broker for a Jumbo Refinance?
Jumbo mortgage guidelines can differ substantially between lenders.
One lender may have a better solution for a salaried borrower with substantial reserves, while another may be better suited for a business owner, high-net-worth borrower or complex luxury property.
A mortgage broker can compare multiple available wholesale programs rather than limiting the borrower to a single institution's product menu.
Daniel Paris has more than 27 years of mortgage lending experience and works with qualified homeowners throughout Utah.
Frequently Asked Questions About Jumbo Refinance Loans Utah
Can I refinance a jumbo mortgage in Utah?
Yes. Qualified Utah homeowners may be able to refinance an existing jumbo mortgage using a rate-and-term or cash-out transaction. Eligibility depends on credit, equity, income, assets, property and lender guidelines.
Can I get cash out with a Utah jumbo refinance?
Potentially. Jumbo cash-out programs may allow qualified homeowners to access eligible equity. Maximum LTV and cash-out amounts vary by lender, loan size, occupancy and borrower profile.
Do jumbo refinance loans require an appraisal?
Generally, a lender will require an appraisal or another acceptable valuation method to establish the property's value. Requirements depend on the lender and transaction.
Can a self-employed borrower refinance a jumbo mortgage?
Yes. Self-employed borrowers may qualify through traditional underwriting or eligible alternative-documentation programs such as bank statement, Profit & Loss or asset-based mortgages.
Can I refinance a multimillion-dollar Utah home?
Potentially. Jumbo and super jumbo mortgage programs may be available for qualified borrowers refinancing multimillion-dollar properties. Requirements generally become more specialized as the loan amount increases.
Are jumbo refinance loans available in Park City?
Yes. Qualified Park City and Deer Valley homeowners may have access to jumbo and super jumbo refinance programs for eligible primary residences, second homes and certain investment properties.
Can I refinance from an ARM into a fixed-rate jumbo mortgage?
Potentially. A jumbo rate-and-term refinance can be used to replace an adjustable-rate mortgage with fixed-rate financing when the borrower and property meet applicable underwriting requirements.
Can I refinance a rental property using DSCR instead?
Potentially. For an eligible investment property, a DSCR refinance may provide an alternative to traditional jumbo underwriting because qualification can focus primarily on the property's qualifying rental cash flow.
Compare Jumbo Refinance Loans in Utah
A jumbo refinance should solve a specific financial problem—not simply replace one large mortgage with another.
The right structure depends on your:
- Existing mortgage
- Property value
- Equity
- Credit profile
- Income documentation
- Available assets
- Desired cash-out
- Expected ownership period
- Short- and long-term financial objectives
Daniel Paris at UtahLowRate.com can help qualified Utah homeowners compare available jumbo, super jumbo, bank statement and other refinance options.
Daniel Paris
Utah Mortgage Broker | UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Apply for a Jumbo Refinance | Explore Jumbo Mortgages | Compare Utah Mortgage Rates
Loan programs, interest rates, APRs, maximum loan amounts, LTV limits, credit requirements, reserves, cash-out limits and underwriting guidelines vary by lender and are subject to change. This information is educational and is not a commitment to lend. Equal Housing Opportunity.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

