
Content updated: September 29, 2026
Super Jumbo Bridge Loans Utah can provide short-term financing for qualified borrowers who need to purchase, refinance, or reposition high-value real estate before another property is sold or another source of liquidity becomes available.
For buyers of multimillion-dollar homes, the timing of a real estate transaction can be just as important as the permanent mortgage.
Check My Jumbo Options or call 801-604-4949.
A qualified borrower may have substantial net worth, significant home equity, investments, business interests, or other assets but may not want to liquidate those assets immediately simply to close on a new luxury property.
A Super Jumbo bridge loan may provide another way to structure the transaction.
Daniel Paris of UtahLowRate.com helps qualified borrowers evaluate Super Jumbo Bridge Loans in Utah and other specialized luxury-mortgage strategies.
Daniel Paris | Utah Mortgage Broker
UtahLowRate.com
Call: 801-604-4949
Quick Answer: A Super Jumbo bridge loan is short-term financing designed for qualified borrowers who need substantial liquidity to complete a high-value real-estate transaction before an existing property is sold or another expected source of funds becomes available. Loan amounts, collateral requirements, LTV limits, documentation, repayment structure, rates, and eligibility depend on the lender and transaction.
Super Jumbo Bridge Loan Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Potential Structure |
|---|---|
| Loan type | Short-term bridge financing |
| Typical purpose | Bridge timing between real-estate transactions |
| High loan amounts | Available through select programs |
| Luxury properties | Potentially eligible |
| Primary residences | Program dependent |
| Second homes | Program dependent |
| Investment properties | Select programs |
| Purchase financing | Potentially available |
| Existing-property equity | May be considered |
| Cross-collateralization | Select programs |
| Interest-only payments | May be available |
| Asset-based qualification | Select programs |
| Exit strategy | Generally required |
| Permanent financing | May follow the bridge transaction |
| Underwriting | Required |
Program terms vary significantly. This table is educational and does not represent a commitment to lend.
What Is a Super Jumbo Bridge Loan?
A Super Jumbo bridge loan is generally a short-term mortgage or real-estate financing arrangement involving a large loan amount.
It can help bridge the financial gap between two events.
For example, a borrower may want to purchase a $7 million home in Park City before selling a $5 million residence in Salt Lake City.
Instead of making the purchase contingent on selling the existing home, an eligible bridge-financing structure may allow the borrower to access sufficient capital to complete the new purchase first.
Once the existing property sells, proceeds may be used to repay some or all of the bridge financing according to the loan terms.
Bridge financing is therefore less about long-term mortgage financing and more about solving a timing and liquidity problem.
Borrowers needing permanent large-balance financing should also review our Super Jumbo Mortgage Loans Utah & California options.
When Can Super Jumbo Bridge Loans Utah Make Sense?
A Super Jumbo bridge loan may be worth evaluating when a qualified borrower has substantial assets or equity but does not have—or does not want to deploy—all required cash immediately.
Common scenarios can include:
- Buying a luxury home before selling another home
- Purchasing a Park City or Deer Valley property quickly
- Making an offer without a home-sale contingency
- Accessing equity from another high-value property
- Bridging the period before permanent financing is completed
- Coordinating a relocation involving two expensive properties
- Avoiding an immediate sale of certain investments solely to fund a purchase
- Creating liquidity for a time-sensitive luxury-property transaction
- Using multiple eligible properties as collateral under certain programs
The appropriate structure depends on the borrower, properties, collateral, liquidity, credit profile, loan amount, and exit strategy.
How Does a Super Jumbo Bridge Loan Work?
Consider a simplified example.
A borrower owns a luxury residence worth approximately $6 million and plans to sell it.
The borrower then finds an $8 million property that they want to purchase before their existing residence sells.
Waiting for the first property to close could mean losing the new property.
Rather than making the new purchase dependent upon the sale, the borrower could investigate bridge financing.
The lender may evaluate:
- Existing property value
- Existing mortgage balances
- New property value
- Requested bridge-loan amount
- Combined collateral
- Borrower liquidity
- Credit profile
- Income or alternative qualification method
- Cash reserves
- Expected property sale
- Permanent financing strategy
- Overall exit strategy
If approved, the bridge loan could provide temporary financing until the expected liquidity event occurs.
The actual structure varies considerably between lenders.
Super Jumbo Bridge Loans vs. Traditional Jumbo Mortgages
A traditional jumbo mortgage is generally designed as longer-term financing.
A bridge loan is generally temporary.
| Super Jumbo Bridge Loan | Traditional Jumbo Mortgage |
|---|---|
| Short-term financing | Long-term financing |
| Solves timing/liquidity issues | Finances property over longer term |
| Exit strategy important | Long-term repayment capacity important |
| Existing property may be involved | Usually focuses on financed property |
| Cross-collateral may be possible | Usually one financed property |
| May precede permanent mortgage | Often permanent financing |
| Specialized underwriting | Standard or specialized jumbo underwriting |
If permanent financing is the goal, review our Jumbo Mortgage Utah guide.
Super Jumbo Bridge Loans for Park City and Deer Valley
Park City and Deer Valley are natural markets for Super Jumbo bridge financing because high-value properties can involve significant transaction sizes and complicated timing.
A buyer may own another residence in Utah, California, or another state and find a Park City property they want to acquire before selling their current home.
Properties may include:
- Ski-in/ski-out residences
- Luxury condominiums
- Custom mountain estates
- Vacation residences
- Second homes
- Resort-area properties
- High-value primary residences
For qualified borrowers, bridge financing may allow the new purchase and existing-property sale to be handled as separate events rather than requiring them to close simultaneously.
Salt Lake City Super Jumbo Bridge Financing
Luxury real estate throughout the Wasatch Front can also create bridge-financing situations.
Potential markets include:
Salt Lake City, Holladay, Millcreek, Cottonwood Heights, Sandy, Draper, Alpine, Highland, Lehi, South Jordan and surrounding communities.
A homeowner with substantial equity in an existing Wasatch Front residence, for example, may want to purchase another property before listing or closing the sale of the existing home.
A bridge loan may provide a temporary financing strategy when the transaction qualifies.
Heber City, Midway and Wasatch County Bridge Loans
Luxury housing has expanded beyond Park City into communities throughout the Wasatch Back.
Qualified buyers considering properties in Heber City, Midway, Jordanelle, Hideout, Kamas and surrounding areas may encounter the same timing challenge.
The borrower has the financial resources to complete the transaction, but those resources may be tied to another property or financial asset.
A Super Jumbo bridge structure may provide temporary liquidity while the borrower's longer-term strategy is completed.
St. George and Southern Utah Luxury Bridge Loans
High-value homes in Southern Utah may also require specialized financing.
Potential markets include:
St. George, Ivins, Santa Clara, Washington, Hurricane, Desert Color and surrounding communities.
Buyers relocating to Southern Utah may want to purchase their next home before selling another residence.
For qualifying transactions, a bridge loan may help coordinate those two events.
Can You Buy Before Selling Your Current Luxury Home?
Potentially.
This is one of the primary reasons borrowers investigate bridge financing.
Traditional purchase financing can become more complicated when the borrower still owns an expensive existing residence.
The borrower may also be unwilling to sell first because doing so could require temporary housing while searching for another luxury property.
A bridge strategy can potentially reverse the sequence:
Purchase the new property → move → sell the existing property → repay or restructure the bridge financing.
Approval depends on the lender's guidelines and the complete transaction.
Cross-Collateral Super Jumbo Bridge Loans
Some specialized lending programs may allow more than one property to support a financing structure.
This is generally called cross-collateralization.
Instead of evaluating only the new property, a lender may potentially consider equity in another eligible property.
For example:
Property A: Existing luxury residence with substantial equity
Property B: New luxury residence being purchased
A specialized lender could potentially structure financing around both properties.
Cross-collateralization is not available on every program and can introduce additional legal, valuation, title, and underwriting considerations.
The structure should therefore be reviewed carefully before closing.
Bridge Loan vs. Pledged Asset Mortgage
High-net-worth borrowers may have several ways to create liquidity.
A borrower with a substantial securities portfolio, for example, may prefer to investigate an asset-backed strategy instead of selling investments.
That makes it useful to compare bridge financing with a Super Jumbo pledged-asset mortgage.
A pledged-asset structure may involve eligible financial assets, while a bridge loan commonly focuses on real-estate collateral and a defined short-term exit strategy.
The best structure depends on where the borrower's wealth is held and what they are trying to accomplish.
Bridge Loan vs. Asset Depletion Mortgage
These strategies solve different problems.
Bridge financing primarily solves a timing or liquidity issue.
Asset depletion financing can potentially use eligible assets to establish qualifying income.
A borrower who has millions of dollars in investments but relatively little conventional employment income may therefore want to compare both approaches.
For permanent luxury financing based on substantial assets, consider a Super Jumbo Asset Depletion Loan.
What Is the Exit Strategy for a Super Jumbo Bridge Loan?
The exit strategy is one of the most important parts of bridge-loan underwriting.
Because the financing is temporary, the lender generally wants to understand how it will be repaid.
Possible exit strategies can include:
- Selling the borrower's existing property.
- Refinancing into permanent Super Jumbo financing.
- Receiving proceeds from another documented liquidity event.
- Paying down the loan with eligible assets.
- Repositioning collateral according to the approved loan structure.
The exit strategy should be realistic and supported by the borrower's financial circumstances.
What Documents May Be Needed?
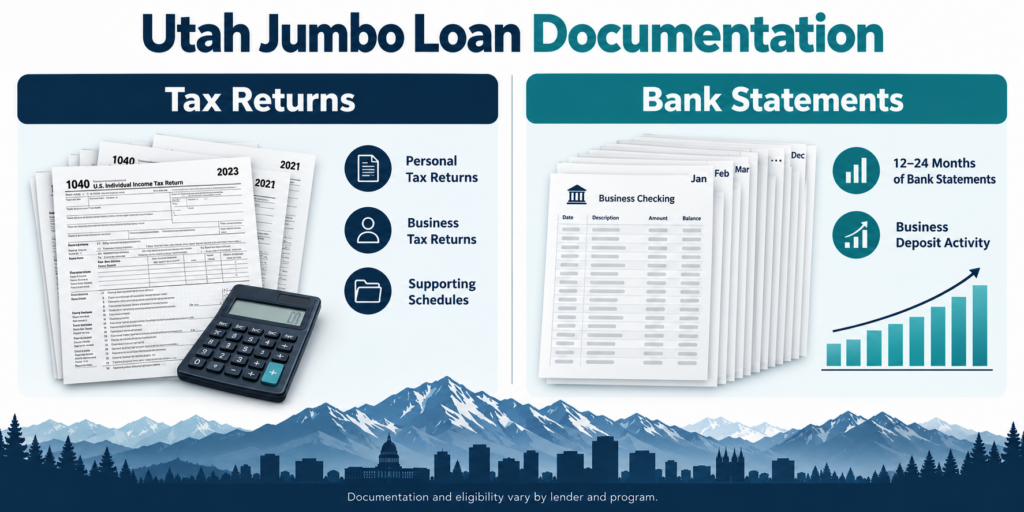
Documentation depends on the loan program.
A lender may request information concerning:
Borrower
- Identification
- Credit authorization
- Income documentation when required
- Personal financial statement
- Asset statements
- Bank statements
- Investment-account statements
- Existing real-estate schedule
- Mortgage statements
Existing Property
- Property address
- Estimated value
- Existing liens
- Property insurance
- Title information
- Current mortgage statement
- Listing information when applicable
New Property
- Purchase agreement
- Appraisal
- Title documentation
- Insurance
- Property information
- HOA documentation when applicable
Exit Strategy
Documentation supporting the expected repayment strategy may also be required.
Super Jumbo Bridge Loan LTV
There is no universal LTV limit for every Super Jumbo bridge loan.
Maximum leverage can depend on:
- Loan amount
- Property value
- Property type
- Occupancy
- Borrower credit
- Liquidity
- Reserves
- Number of properties pledged
- Existing liens
- Marketability of collateral
- Exit strategy
- Overall borrower strength
Very large loans may have more conservative leverage requirements than smaller jumbo transactions.
Super Jumbo Bridge Loan Rates
Bridge-loan pricing should not be compared with a conventional 30-year mortgage based solely on the headline interest rate.
Bridge financing is specialized short-term capital.
Pricing can depend on the loan amount, term, collateral, LTV, borrower strength, exit strategy, property, and current capital-market conditions.
Borrowers seeking permanent financing should compare available structures with current Utah Mortgage Rates and available Super Jumbo programs.
Super Jumbo Bridge Loans for Self-Employed Borrowers
Entrepreneurs and business owners frequently have substantial net worth without receiving a simple W-2 salary.
That does not necessarily mean every bridge program will evaluate the borrower using conventional income documentation.
Depending on the lender, specialized qualification options may be available.
Self-employed borrowers needing permanent financing may also want to review:
- Bank Statement Loans Utah
- Jumbo Bank Statement Loans Utah
- Asset depletion mortgage programs
- Non-QM mortgage programs
The goal is to match the documentation method with the borrower's actual financial profile.
Super Jumbo Bridge Loans and Investment Properties
Some bridge programs may be available for investment-property transactions.
However, investment-property bridge financing should be distinguished from a standard residential bridge loan.
Real-estate investors may have other alternatives depending on the property and transaction.
One important alternative is a DSCR mortgage.
DSCR financing generally evaluates the qualifying rental income of an investment property relative to its applicable housing obligations rather than relying primarily on traditional personal-income qualification.
For investment-property financing, explore the complete UtahLowRate.com DSCR resource center.
Utah DSCR Loan Resources
- DSCR Mortgage Loans Utah
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Loans Salt Lake City Utah
- DSCR Loans Park City Utah
- DSCR Loans St. George Utah
Bridge financing and DSCR financing solve different problems. A bridge loan is generally short-term financing, while DSCR financing can provide a longer-term mortgage for an eligible rental property.
$2 Million to $30 Million+ Luxury Mortgage Strategies
Large mortgage transactions should not automatically be forced into one financing structure.
Depending on borrower qualifications and current lender programs, borrowers may want to compare financing at several levels:
- $2 million mortgage loans
- $5 million mortgage loans
- $10 million mortgage loans
- $20 million mortgage loans
- $30 million mortgage loans
- Super Jumbo bridge loans
- Super Jumbo pledged-asset mortgages
- Super Jumbo asset-depletion loans
- Super Jumbo purchase loans
- Super Jumbo refinance loans
- Super Jumbo cash-out financing
The larger the transaction becomes, the more important liquidity, reserves, collateral, documentation, and overall financial structure can become.
Why Use a Mortgage Broker for Super Jumbo Bridge Financing?
Super Jumbo bridge lending is highly specialized.
Guidelines can vary substantially among lending sources.
One lender may focus heavily on liquidity.
Another may be more comfortable with multiple properties.
Another may allow a different collateral arrangement.
Another may specialize in borrowers with substantial investment assets.
Working with a mortgage broker provides the opportunity to evaluate available wholesale and specialty programs rather than assuming one lender's guidelines represent the entire market.
Daniel Paris has more than 27 years of mortgage lending experience and helps qualified borrowers evaluate Jumbo, Super Jumbo, alternative-documentation, asset-based, and other specialized mortgage strategies.
How to Evaluate a Super Jumbo Bridge Loan
A useful preliminary review usually begins with the complete transaction rather than just the desired loan amount.
Be prepared to discuss:
1. New property purchase price
2. Desired loan amount
3. Existing property value
4. Current mortgage balances
5. Estimated available equity
6. Credit profile
7. Liquid assets
8. Investment assets
9. Income or documentation method
10. Expected exit strategy
This information can help identify which available financing structures are worth evaluating.
Frequently Asked Questions About Super Jumbo Bridge Loans Utah
What is a Super Jumbo bridge loan?
A Super Jumbo bridge loan is specialized short-term financing involving a large mortgage or real-estate transaction. It can help qualified borrowers bridge the period between purchasing a new property and selling an existing property or completing another expected liquidity event.
Can I buy a luxury home before selling my current home?
Potentially. Qualified borrowers may be able to use bridge financing to complete a new luxury-home purchase before selling an existing residence. Approval depends on equity, collateral, credit, liquidity, reserves, loan amount, property and exit strategy.
Are Super Jumbo bridge loans available in Park City?
Qualified borrowers may have access to specialized bridge financing for eligible Park City and Deer Valley properties, subject to lender guidelines, property eligibility and underwriting.
Can two properties be used for a bridge loan?
Some specialized programs may permit cross-collateral structures involving multiple eligible properties. Availability and requirements vary by lender.
Are Super Jumbo bridge loans interest-only?
Some programs may offer interest-only payment structures. Terms vary, and borrowers should review the payment requirements, maturity date, fees and repayment strategy carefully.
Can self-employed borrowers obtain a Super Jumbo bridge loan?
Potentially. Qualification depends on the selected lender and transaction. Self-employed borrowers may also have access to bank-statement, asset-based, asset-depletion and other alternative-documentation programs.
Can a bridge loan be refinanced into a Super Jumbo mortgage?
That may be an available exit strategy. The borrower would still need to qualify for the permanent mortgage under the lender's guidelines at the time of refinancing.
Are bridge loans available for investment properties?
Select bridge programs may finance eligible investment-property transactions. Investors should also compare bridge financing with DSCR and other business-purpose investment-property programs.
Discuss Your Super Jumbo Bridge Loan Scenario
A multimillion-dollar property transaction can require more than a standard mortgage approval.
The critical issue may be timing, liquidity, collateral, or the coordination of several assets and properties.
Daniel Paris helps qualified borrowers evaluate Super Jumbo Bridge Loans Utah along with permanent Super Jumbo mortgages, pledged-asset strategies, asset-depletion financing, Jumbo bank-statement loans and other specialized mortgage options.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
Call: 801-604-4949
CTA: Check My Super Jumbo Bridge Loan Options
Important Mortgage Disclosure
Mortgage programs, bridge-loan programs, loan amounts, rates, APRs, fees, terms, LTV limits, collateral requirements, credit requirements, documentation requirements, reserve requirements, interest-only options and underwriting guidelines can change without notice.
Information on this page is for general educational purposes and does not constitute an offer, guarantee, approval or commitment to lend.
All loans are subject to borrower qualification, acceptable collateral, property eligibility, appraisal, lender and investor guidelines, underwriting approval, applicable licensing requirements and program availability.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

