
Home Financing Options
If you are buying, refinancing or investing in property in Salt Lake City, Utah, the right mortgage depends on more than the advertised interest rate. Credit, income, down payment, property type, occupancy, loan amount and documentation can all affect your available financing.
Daniel Paris at UtahLowRate.com helps qualified Salt Lake City homebuyers, homeowners, self-employed borrowers, investors and luxury-home buyers compare conventional, FHA, VA, jumbo, bank statement, DSCR and other mortgage options.
With more than 27 years of mortgage lending experience, Daniel can help you evaluate financing based on your actual scenario rather than trying to fit every borrower into the same mortgage program.
Call Daniel Paris: 801-604-4949
CTA: Check My Salt Lake City Mortgage Options
Quick Answer: What Mortgage Loans Are Available in Salt Lake City?
Salt Lake City borrowers may have access to conventional, FHA, VA, jumbo, super jumbo, bank statement, 1099, Profit & Loss, DSCR and other Non-QM mortgage programs. The appropriate loan depends on your credit, qualifying income, assets, down payment or equity, property type, occupancy and loan amount.
Salt Lake City Mortgage Loan Quick Facts
| Mortgage Topic | Salt Lake City Financing Options |
|---|---|
| Home Purchase | Available for qualified borrowers |
| Mortgage Refinance | Rate-and-term and eligible cash-out options |
| Conventional Loans | Available |
| FHA Loans | Available for eligible borrowers and properties |
| VA Loans | Available for eligible Veterans and service members |
| Jumbo Loans | Available |
| Super Jumbo Loans | Specialized high-balance financing available |
| Bank Statement Loans | Alternative income documentation for eligible self-employed borrowers |
| 1099 Loans | Available for qualifying independent contractors |
| Profit & Loss Loans | Alternative-documentation programs available |
| DSCR Loans | Available for eligible investment properties |
| First-Time Buyers | Multiple potential programs |
| Self-Employed Borrowers | Traditional and alternative-documentation options |
| Mortgage Broker | Daniel Paris |
| Experience | 27+ years |
| Phone | 801-604-4949 |
| Service Area | Salt Lake City and communities throughout Utah |
Program availability, rates, terms and qualification requirements can change. All financing is subject to applicable lender and investor guidelines.
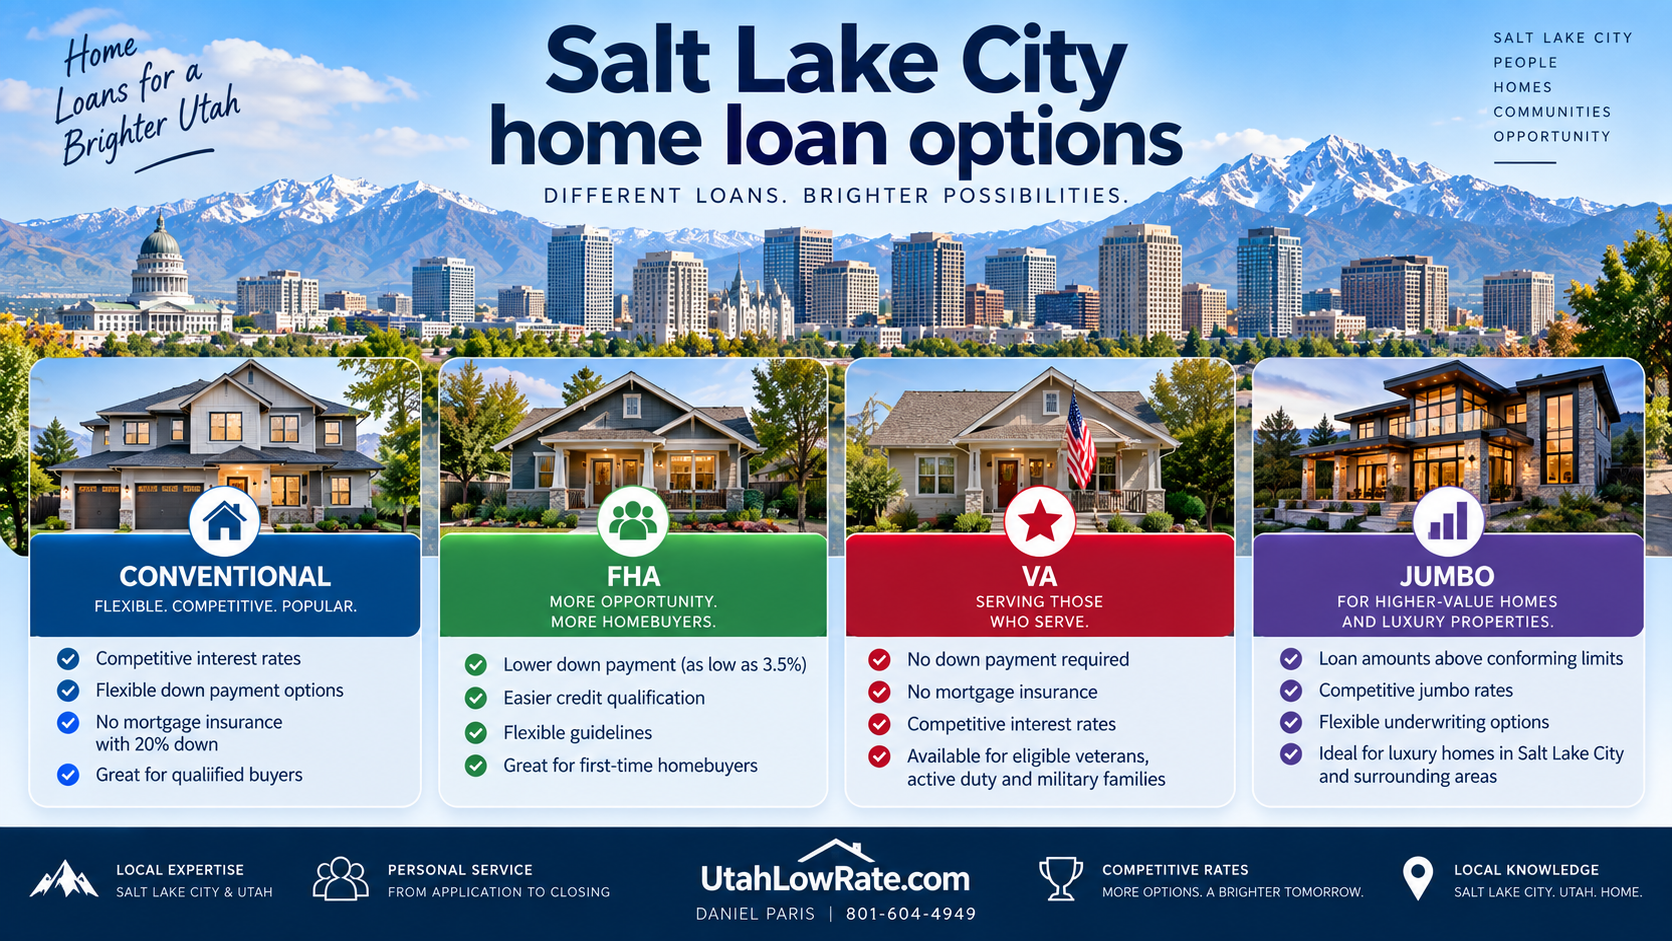
How Do Salt Lake City Mortgage Loans Work?
A mortgage provides financing to purchase or refinance real property. The mortgage program you qualify for can depend on several factors, including:
- Credit history and credit score
- Employment
- Qualifying income
- Self-employment history
- Monthly debts
- Debt-to-income ratio
- Down payment or available equity
- Cash reserves
- Property type
- Primary, second-home or investment occupancy
- Loan amount
- Documentation
- Underwriting requirements
That is why comparing only an advertised mortgage rate can be misleading.
Two Salt Lake City borrowers purchasing similarly priced homes could receive different loan options or pricing because their financial profiles are different.
Conventional Mortgage Loans in Salt Lake City
Conventional mortgages are commonly used by Salt Lake City homebuyers with qualifying credit, income and assets.
Depending on program requirements, conventional financing may be used for:
- Primary residences
- Second homes
- Investment properties
- Home purchases
- Rate-and-term refinances
- Cash-out refinances
Down-payment requirements depend on the program, occupancy, property and borrower profile.
Borrowers should also consider whether private mortgage insurance may apply when financing a larger percentage of the property's value.
Learn more about Conventional Mortgage Loans in Utah.
You can also review 2026 Conventional Loan Limits in Utah.
FHA Loans in Salt Lake City, Utah
FHA mortgages can be useful for qualified borrowers who want a lower minimum down-payment option or whose credit profile may not fit certain conventional programs.
FHA financing may offer:
- Low-down-payment purchase options
- Flexible credit qualification
- Gift-fund options when FHA requirements are met
- Purchase and refinance programs
- FHA 203(k) renovation financing for eligible properties and improvements
FHA mortgages also include mortgage insurance requirements.
Loan limits vary according to the property's location and number of units, so borrowers purchasing in Salt Lake County should verify the current applicable FHA limit.
See the complete FHA Loans Utah Guide and 2026 FHA Loan Limits in Utah.
CTA: See If I Qualify for an FHA Loan
VA Home Loans in Salt Lake City
Eligible Veterans, active-duty service members and certain qualifying surviving spouses may want to compare VA financing with conventional and FHA alternatives.
Potential VA benefits can include:
- Eligible zero-down-payment financing
- No monthly private mortgage insurance
- Purchase financing
- VA refinance options
- Financing for eligible higher-priced properties
- Flexible underwriting features under applicable VA and lender requirements
Eligibility does not automatically mean every property or borrower qualifies.
Your VA entitlement, credit profile, income, debts, property, occupancy and applicable underwriting requirements still need to be evaluated.
Explore VA Mortgage Loans in Utah.
Jumbo Mortgage Loans in Salt Lake City
Higher-priced homes can require financing above applicable conforming loan limits.
A jumbo mortgage is a non-conforming mortgage designed for loan amounts that exceed applicable conforming limits.
Salt Lake City jumbo financing may be used for qualifying:
- Luxury homes
- Primary residences
- Second homes
- Investment properties
- Custom homes
- Purchase transactions
- Rate-and-term refinances
- Cash-out refinances
Jumbo underwriting may place additional emphasis on credit, liquidity, reserves, income documentation and the property itself.
UtahLowRate.com also works with qualified borrowers seeking specialized Super Jumbo financing, including programs designed for substantially larger loan amounts.
Explore Jumbo Mortgage Loans in Utah or the dedicated Jumbo Mortgage Salt Lake City Utah resource.
CTA: Compare Salt Lake City Jumbo Programs
Bank Statement Loans in Salt Lake City
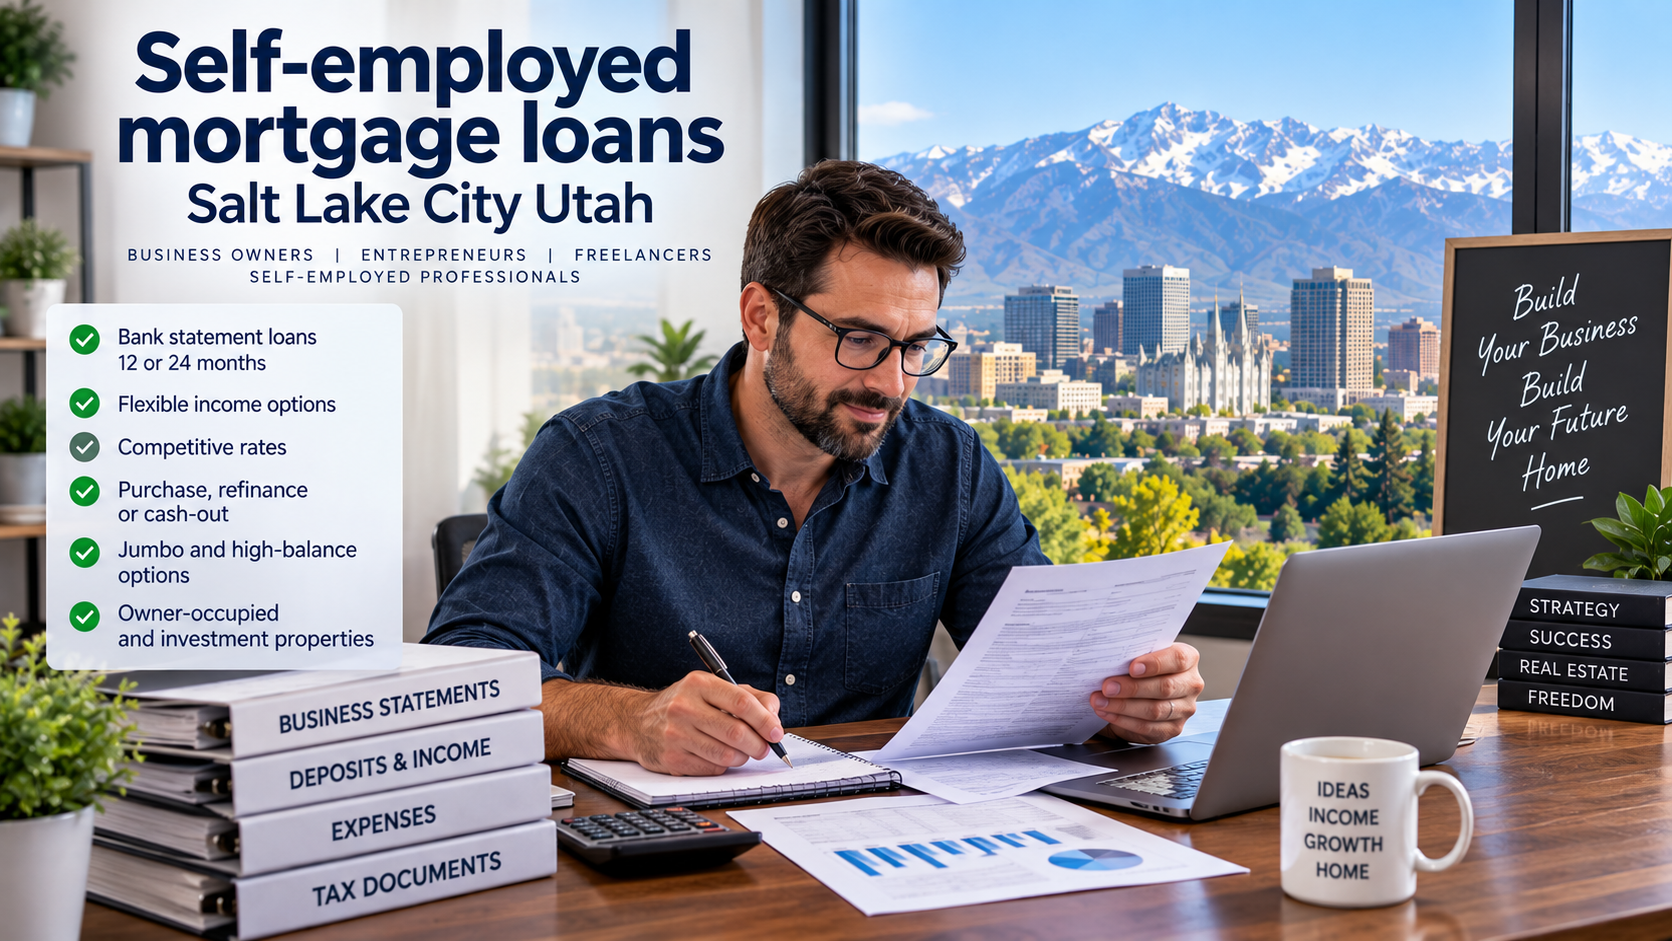
Traditional mortgage underwriting can be challenging for some business owners because taxable income does not always represent the cash flow of the business.
A bank statement mortgage provides an alternative income-documentation method for eligible self-employed borrowers.
Instead of relying exclusively on traditional tax-return calculations, qualifying income may be calculated using eligible deposits from personal or business bank statements.
Depending on the program, lenders may review:
- 12 or 24 months of statements
- Eligible business or personal deposits
- Business expense factors
- Self-employment history
- Credit profile
- Down payment or equity
- Assets and reserves
- Property and occupancy
Transfers, non-income deposits and other ineligible deposits generally should not simply be counted as qualifying income.
Learn more about Bank Statement Loans in Utah and Bank Statement Loans in Salt Lake City.
CTA: Estimate My Bank Statement Income
Mortgage Options for Self-Employed Salt Lake City Borrowers
Bank statements are not the only potential option for self-employed borrowers.
Depending on how you earn and document income, financing possibilities may include:
- Conventional mortgages
- FHA mortgages
- VA mortgages for eligible borrowers
- Jumbo mortgages
- Bank statement mortgages
- 1099 mortgage programs
- Profit & Loss mortgage programs
- Asset-depletion programs
- Non-QM mortgages
The key is matching the documentation method to the borrower's actual financial circumstances.
For example, an independent contractor primarily receiving Form 1099 income may want to review 1099 Mortgage Loans in Utah.
A business owner may also want to compare Profit and Loss Mortgage Loans with bank statement financing.
DSCR Loans for Salt Lake City Real Estate Investors
Real estate investors have different financing needs from owner-occupied homebuyers.
A Debt Service Coverage Ratio, or DSCR, mortgage may allow an eligible investment property's rental income and proposed housing expense to play an important role in qualification.
DSCR programs are generally intended for investment properties rather than owner-occupied homes.
Important factors can include:
- Monthly qualifying rent
- Proposed mortgage payment
- Taxes
- Insurance
- HOA dues when applicable
- Property type
- Loan-to-value ratio
- Credit
- Reserves
- Program requirements
Learn more about DSCR Mortgage Loans in Utah.
CTA: Check My DSCR Scenario
Salt Lake City Mortgage Loans for First-Time Homebuyers
Buying your first home can involve more than determining how much you can borrow.
A useful mortgage comparison should also consider:
- Required down payment
- Estimated closing costs
- Mortgage insurance
- Interest rate
- APR
- Discount points
- Monthly principal and interest
- Property taxes
- Homeowners insurance
- HOA dues when applicable
- Cash reserves after closing
Depending on eligibility, a first-time buyer might compare conventional, FHA, VA or available assistance programs.
Learn about Down Payment Assistance in Utah.
Salt Lake City Mortgage Pre-Approval
Getting pre-approved before making an offer can help establish your potential purchasing range and identify financing issues early.
A mortgage pre-approval may involve reviewing:
- Credit
- Income
- Employment
- Assets
- Existing debts
- Down payment
- Loan amount
- Property and occupancy plans
- Appropriate mortgage programs
A pre-approval is not the same as final mortgage approval. Final approval generally depends on underwriting, the selected property, appraisal or applicable valuation requirements, title, insurance and other conditions.
Start with Utah Mortgage Pre-Approval.
How Should You Compare Salt Lake City Mortgage Rates?
Do not compare mortgages using the interest rate alone.
When comparing Salt Lake City mortgage quotes, consider the complete transaction:
- Interest rate
- APR
- Discount points
- Origination charges
- Lender fees
- Mortgage insurance
- Loan term
- Lock period
- Monthly payment
- Closing costs
- Prepayment provisions when applicable
An advertised low interest rate may involve discount points or assumptions that do not match your financial situation.
For current market context, visit Utah Mortgage Rates.
CTA: Get Today's Utah Rate
Purchase, Refinance or Cash-Out Mortgage Options
Buying a Salt Lake City Home
Your mortgage options should be evaluated before or early in your home search so you understand your potential purchase range, required cash and estimated housing payment.
Refinancing a Salt Lake City Home
Refinancing may be considered for reasons such as changing the loan term, replacing an existing mortgage or restructuring financing.
Whether refinancing makes financial sense depends on the new loan's rate, fees, closing costs, term and the homeowner's objectives.
Cash-Out Refinance
Eligible homeowners may be able to replace an existing mortgage with a larger mortgage and receive part of the available equity as cash.
Cash-out requirements vary by mortgage program, property, occupancy, credit and available equity.
Mortgage Loans Throughout the Salt Lake Valley
Daniel Paris works with qualified borrowers in Salt Lake City and surrounding communities, including:
- Downtown Salt Lake City
- Sugar House
- The Avenues
- Federal Heights
- East Bench
- Holladay
- Millcreek
- Murray
- Cottonwood Heights
- Sandy
- Draper
- South Jordan
- West Jordan
- Riverton
- Herriman
- Bluffdale
- Midvale
- Taylorsville
- South Salt Lake
Borrowers purchasing in different areas may face very different property prices, HOA structures, property types and financing needs.
The appropriate mortgage should be based on the borrower and the specific property—not simply the ZIP code.
Why Work With a Salt Lake City Mortgage Broker?
A mortgage broker can help qualified borrowers compare financing from multiple wholesale lending sources rather than relying only on the mortgage programs available from a single bank.
This can be particularly useful when the scenario involves:
- Self-employment
- Alternative income documentation
- Jumbo financing
- Complex assets
- Investment properties
- Non-QM financing
- Unusual property or borrower circumstances
Daniel Paris has more than 27 years of mortgage lending experience working with Utah homebuyers, homeowners, investors and self-employed borrowers.
Learn more about Daniel Paris and UtahLowRate.com.
Salt Lake City Mortgage Loan FAQ
What types of mortgage loans are available in Salt Lake City?
Qualified borrowers may have access to conventional, FHA, VA, jumbo, super jumbo, bank statement, 1099, Profit & Loss, DSCR and other Non-QM programs. Eligibility varies by borrower, property and program.
How much down payment do I need to buy a home in Salt Lake City?
There is no universal down payment. The required amount depends on the mortgage program, property, occupancy, loan amount and borrower qualifications. Certain eligible programs allow relatively small down payments, while others may require substantially more.
Can I buy a Salt Lake City home with an FHA loan?
Potentially. The borrower, transaction and property must satisfy applicable FHA and lender requirements, and the mortgage amount must comply with the applicable FHA loan limit.
Can I buy a Salt Lake City home with a VA loan?
Eligible Veterans, service members and certain surviving spouses may be able to use VA financing for an eligible primary residence, subject to VA and lender requirements.
Can self-employed borrowers get a mortgage in Salt Lake City?
Yes. Depending on qualifications, self-employed borrowers may use conventional, government, jumbo or alternative-documentation programs such as bank statement, 1099 or Profit & Loss mortgages.
What is a bank statement mortgage?
A bank statement mortgage is an alternative-documentation loan that may allow an eligible self-employed borrower to document qualifying income through analyzed bank deposits rather than relying exclusively on traditional tax-return income calculations.
When do I need a jumbo loan in Salt Lake City?
A jumbo mortgage may be needed when the required loan amount exceeds the applicable conforming loan limit. Jumbo loans use non-conforming underwriting and program requirements.
Are DSCR loans available for Salt Lake City rental properties?
DSCR programs may be available for eligible investment properties. Qualification and terms depend on factors including the property's rental income, proposed housing expense, credit, LTV, reserves and specific program requirements.
What credit score do I need for a Salt Lake City mortgage?
There is no single minimum score that applies to every mortgage. Credit requirements vary among conventional, FHA, VA, jumbo and Non-QM programs, and individual lenders may impose additional requirements.
How do I get pre-approved for a Salt Lake City mortgage?
Start by providing information about your income, employment, assets, debts, credit, down payment and intended purchase. Your mortgage options and potential purchasing range can then be evaluated.
How do I find today's Salt Lake City mortgage rate?
Mortgage rates can change and are borrower-specific. Request a same-day quote using the same loan amount, credit profile, down payment, occupancy, lock period and points structure you intend to compare.
Talk With Daniel Paris About Your Salt Lake City Mortgage
Whether you are purchasing your first home, moving to a larger property, buying a luxury residence, investing in rental property, refinancing or trying to qualify with self-employment income, your mortgage should be evaluated around your actual circumstances.
Daniel Paris
Utah Mortgage Broker
27+ Years of Mortgage Lending Experience
NMLS #243976
UtahLowRate.com
801-604-4949
Compare Your Salt Lake City Mortgage Options
Get a scenario-specific review of available:
- Conventional loans
- FHA loans
- VA loans
- Jumbo and Super Jumbo loans
- Bank statement loans
- 1099 mortgages
- Profit & Loss mortgages
- DSCR loans
- Non-QM mortgage programs
- Purchase and refinance options
CTA: Check My Mortgage Options
Mortgage rates, APRs, fees, loan amounts, LTV limits, credit requirements, documentation requirements and program availability are subject to change. All loans are subject to lender and investor guidelines, underwriting approval, borrower qualification, property eligibility and applicable regulations. This page is for educational purposes and is not a commitment to lend.
Last Updated: September 2026

