
Home Financing Options
Buying a home, refinancing, purchasing a second home, or investing in Southern Utah starts with finding financing that fits your situation. St. George Utah mortgage loans can include conventional, FHA, VA, jumbo, bank statement, 1099, Profit & Loss, DSCR, and other mortgage programs for qualified borrowers.
Utah Low Rate helps homebuyers, homeowners, self-employed borrowers, Veterans, investors, and luxury-home buyers compare mortgage options throughout St. George, Washington County, and Southern Utah.
Talk With Daniel Paris About Your St. George Mortgage
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
801-604-4949
Buying or refinancing in Southern Utah? Compare available mortgage programs, rates, documentation requirements, and financing strategies before choosing your loan.
Mortgage programs, rates, terms, eligibility, and underwriting guidelines are subject to change and borrower/property approval.
Quick Answer: What Mortgage Loans Are Available in St. George, Utah?
St. George homebuyers and homeowners may have access to conventional, FHA, VA, jumbo, super jumbo, bank statement, 1099, Profit & Loss, DSCR, Non-QM, purchase, and refinance mortgage loans. The right option depends on your credit, income, assets, down payment, property type, occupancy, loan amount, and financial goals.
St. George Mortgage Loan Quick Facts
- Location: St. George, Washington County, Utah
- 2026 one-unit conforming loan limit: $832,750
- 2026 one-unit FHA loan limit: $607,200
- Loan purposes: Purchase, refinance, and qualifying cash-out transactions
- Occupancy: Primary residence, eligible second home, or investment property depending on program
- Self-employed options: Bank statement, 1099, P&L, asset-based, and other Non-QM programs may be available
- Investor financing: Conventional, jumbo, Non-QM, and DSCR options may be available
- Higher loan amounts: Jumbo and super jumbo financing may be available for qualified borrowers
Loan limits and program guidelines should always be confirmed for the individual transaction.
St. George Utah Mortgage Loan Options
Different borrowers need different financing. A first-time homebuyer purchasing in Little Valley may have very different needs from a self-employed borrower purchasing in Entrada, a Veteran moving to Washington County, or an investor purchasing a rental property.
Here is a quick comparison:
| Mortgage Program | May Be Useful For | Common Qualification Focus |
|---|---|---|
| Conventional | Primary, second homes and eligible investments | Credit, income, assets and DTI |
| FHA | Eligible owner-occupied purchases/refinances | FHA eligibility and underwriting |
| VA | Eligible Veterans and service members | VA eligibility, entitlement and underwriting |
| Jumbo | Higher loan amounts | Credit, income, assets and reserves |
| Bank Statement | Qualified self-employed borrowers | Eligible bank deposits/cash flow |
| 1099 | Eligible independent contractors | Qualifying 1099 income |
| P&L | Certain self-employed borrowers | Eligible Profit & Loss documentation |
| DSCR | Real estate investors | Property rental cash flow |
| Non-QM | Borrowers outside standard agency guidelines | Program-specific alternative criteria |
Not every program is available or appropriate for every borrower.
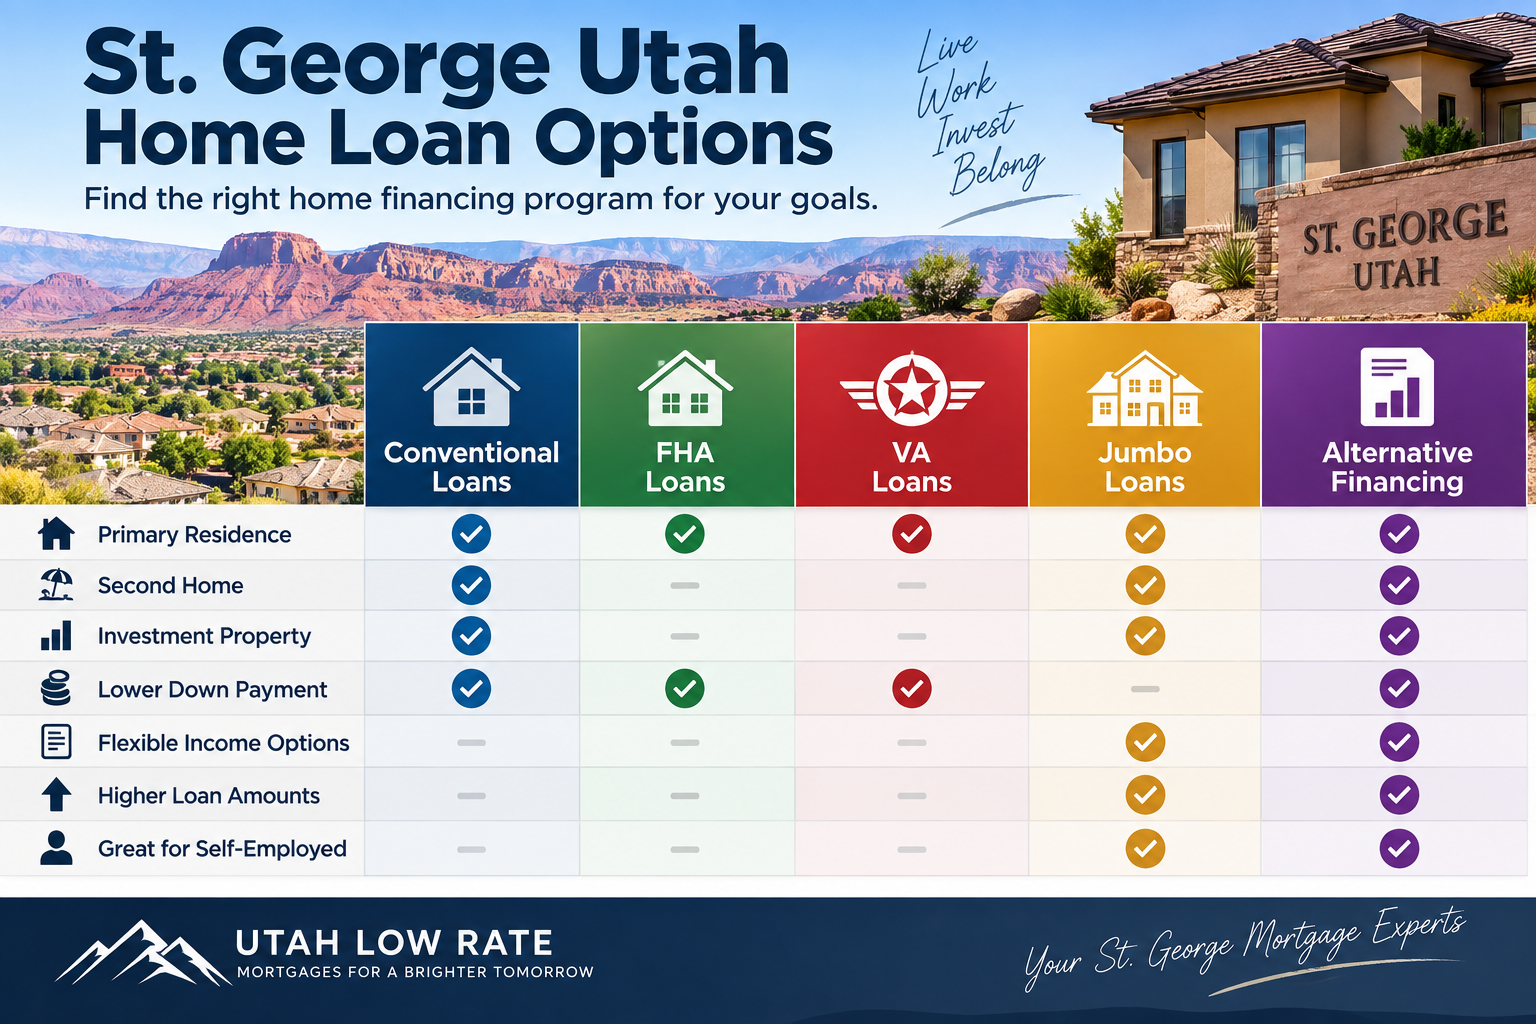
Conventional Mortgage Loans in St. George
Conventional mortgage loans in Utah can be used by qualified borrowers for purchases and refinancing.
Depending on the program, conventional financing may be available for:
- Primary residences
- Eligible second homes
- Investment properties
- Home purchases
- Rate-and-term refinances
- Cash-out refinances
For 2026, Washington County's conforming loan limit for a one-unit property is $832,750.
Borrowers seeking financing above the applicable conforming limit may need to consider jumbo financing or another appropriate mortgage program.
Learn more about 2026 conventional loan limits in Utah.
FHA Loans in St. George, Utah
FHA loans in St. George may provide another option for eligible borrowers purchasing or refinancing an owner-occupied property.
FHA financing can offer:
- Low down-payment options for qualifying borrowers
- Flexible credit guidelines
- Fixed-rate mortgage options
- Purchase financing
- Several refinance options
For 2026, HUD lists the one-unit FHA forward mortgage limit for Washington County at $607,200.
FHA financing also requires applicable mortgage insurance and compliance with FHA borrower, occupancy, appraisal, property, and underwriting requirements.
See the complete Utah FHA loan guide for additional information.
VA Home Loans in St. George
Eligible Veterans, active-duty service members, and certain other qualified borrowers may be able to use a VA-backed mortgage when purchasing or refinancing a home in Southern Utah.
Potential VA benefits can include:
- No required down payment in qualifying transactions
- No monthly private mortgage insurance
- Purchase financing
- Refinance options
- Financing for eligible higher-priced homes
VA eligibility, entitlement, occupancy, appraisal, credit, income, and underwriting requirements apply.
Buyers should verify VA eligibility and financing before making an offer so they understand their potential purchasing range and documentation requirements.
Jumbo Mortgage Loans in St. George
Higher-priced Southern Utah properties may require financing beyond standard conforming loan amounts.
Jumbo loans in St. George may be available to qualified borrowers purchasing or refinancing higher-value properties.
Jumbo financing can be particularly relevant for homes in and around:
Entrada, Stone Cliff, The Ledges, Kayenta, Ivins, Santa Clara, Washington, and other higher-value Southern Utah communities.
Depending on the program, jumbo financing may be available for:
- Primary residences
- Second homes
- Investment properties
- Purchase transactions
- Refinancing
- Cash-out refinancing
Jumbo underwriting can differ substantially from conventional financing. Credit, reserves, down payment, loan-to-value, property characteristics, and income documentation can all affect eligibility.
Compare additional options on the Utah jumbo mortgage page.
Super Jumbo Mortgage Financing in Southern Utah
Some borrowers purchasing very high-value Southern Utah real estate need loan amounts beyond traditional jumbo financing.
Super jumbo mortgage loans may provide financing alternatives for qualified borrowers with complex or high-value mortgage needs.
Depending on the program, underwriting may consider:
- Loan amount
- Property value
- Loan-to-value ratio
- Credit profile
- Liquidity
- Cash reserves
- Income
- Investment assets
- Property occupancy
Because jumbo and super jumbo guidelines can vary significantly among lenders, comparing multiple programs can be especially important.
Self-Employed Mortgage Loans in St. George
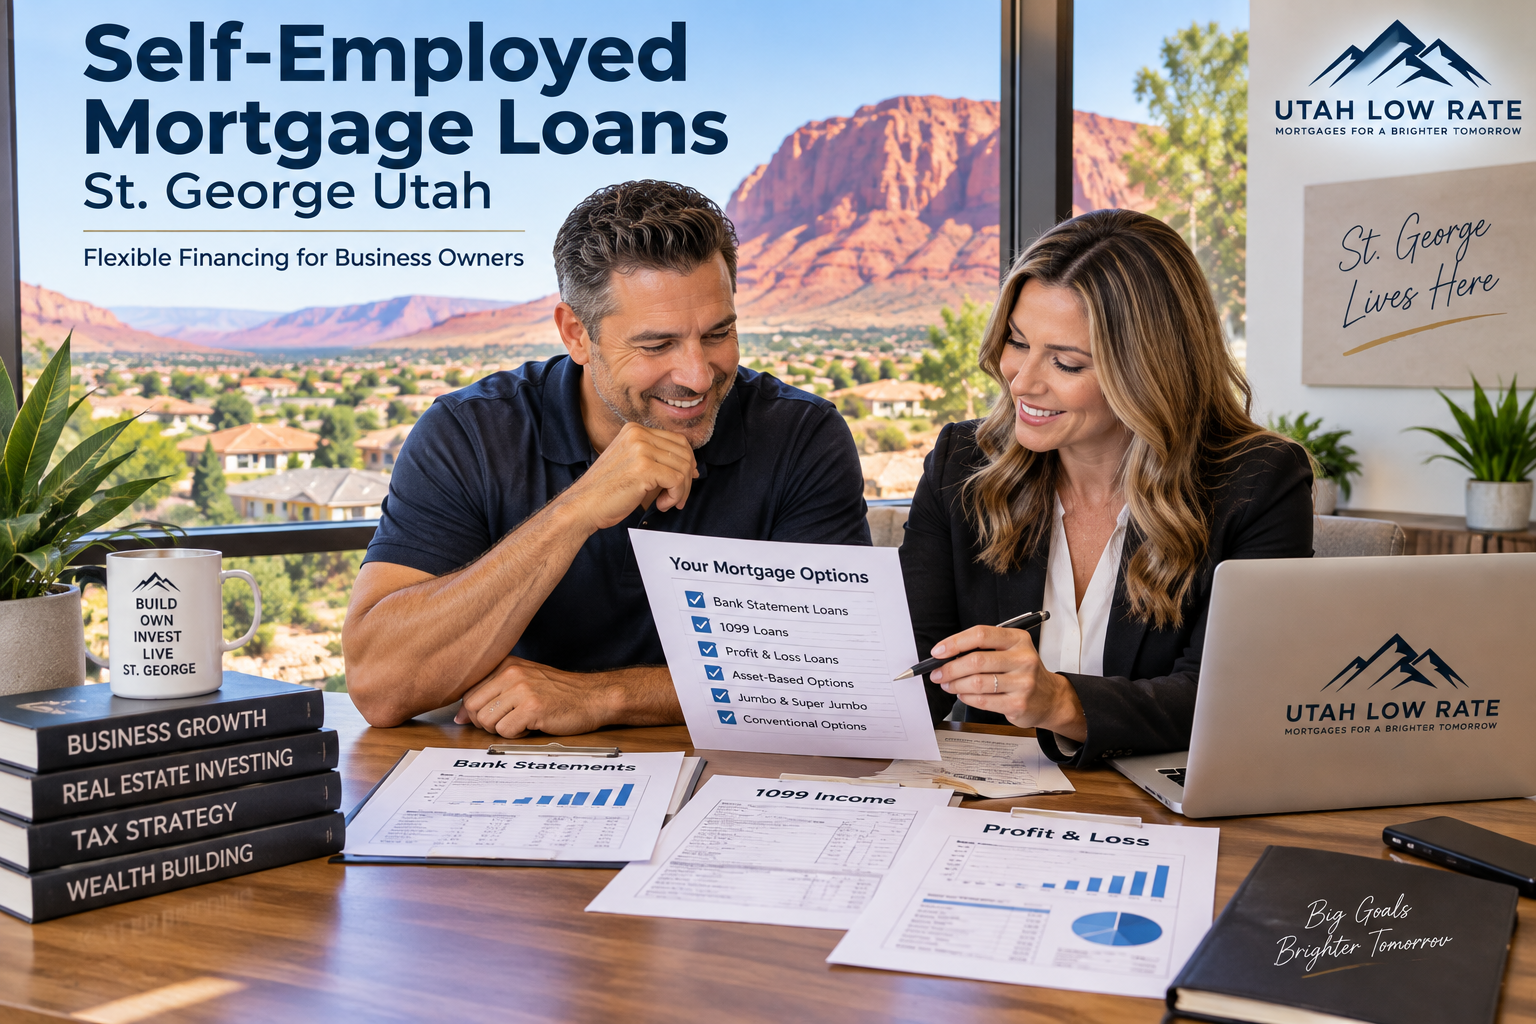
Business owners and independent professionals often have mortgage needs that do not fit neatly into traditional W-2 underwriting.
Tax deductions can reduce taxable income even when a business generates substantial cash flow.
Qualified self-employed borrowers may therefore want to compare both traditional and alternative-documentation mortgage programs.
Bank Statement Loans
Bank statement loans in St. George may allow eligible self-employed borrowers to establish qualifying income using personal or business bank statements under applicable program guidelines.
These programs can be useful when tax-return income does not adequately represent the borrower's current cash flow.
1099 Mortgage Loans
1099 mortgage loans may provide an alternative for eligible independent contractors whose income is documented primarily through 1099 earnings.
Program-specific income calculations and documentation requirements apply.
Profit & Loss Mortgage Loans
Profit and Loss mortgage loans may allow certain qualified self-employed borrowers to use an eligible P&L statement as part of the income documentation process.
Asset-Based Mortgage Options
Borrowers with substantial eligible assets may have access to mortgage programs that use assets as part of the qualifying-income calculation.
The appropriate documentation method depends on the borrower, lender, loan program, property, and transaction.
DSCR Loans for St. George Real Estate Investors
St. George and Washington County real estate investors may have financing choices beyond conventional investment-property mortgages.
DSCR mortgage loans in Utah generally focus on the qualifying rental property's cash flow relative to its housing obligation rather than qualifying primarily from the borrower's traditional employment income.
DSCR financing may be useful for eligible:
- Long-term rental properties
- Single-family investment homes
- Certain 2–4 unit investment properties
- Experienced investors
- New investors who satisfy program requirements
DSCR requirements vary by lender and can include minimum credit, down payment, reserves, property type, rental-income calculations, appraisal requirements, and minimum DSCR standards.
Buying a Second Home in St. George or Southern Utah
Southern Utah attracts buyers who want a second residence in addition to their primary home.
Second-home financing may be available through qualifying conventional or jumbo programs.
A second home is not automatically treated the same as an investment property.
The intended use of the property matters. Borrowers should accurately disclose whether a property will be used as a:
- Primary residence
- Second home
- Investment property
Properties intended primarily for rental use generally need to be evaluated under the applicable investment-property guidelines.
Mortgage Loans Throughout St. George and Washington County
Utah Low Rate works with qualified borrowers throughout St. George and surrounding Southern Utah communities.
Areas can include:
St. George • Washington • Ivins • Santa Clara • Hurricane • Bloomington • Little Valley • Desert Color • Sun River • Entrada • Stone Cliff • The Ledges • Kayenta
The same mortgage program will not necessarily fit every property or borrower.
A luxury second home in Entrada, primary residence in Little Valley, rental property in Washington, or home in Ivins may each require a different financing analysis.
What Determines St. George Mortgage Rates?
There is no single mortgage rate that applies to every borrower.
Your mortgage rate and pricing can depend on factors such as:
- Credit score
- Loan program
- Loan amount
- Down payment or equity
- Loan-to-value ratio
- Property type
- Occupancy
- Loan term
- Discount points
- Debt-to-income ratio
- Market conditions
That means an advertised mortgage rate should not automatically be interpreted as the rate available for your transaction.
Visit Utah mortgage rates to learn more, then request pricing based on your actual loan scenario.
How Should You Compare St. George Mortgage Quotes?
Do not compare mortgage offers based only on the advertised interest rate.
Compare the complete financing structure, including:
- Interest rate
- APR
- Discount points
- Origination charges
- Lender and broker charges
- Mortgage insurance, when applicable
- Loan term
- Estimated monthly payment
- Estimated closing costs
The lowest advertised interest rate does not necessarily represent the lowest overall borrowing cost.
How to Get Pre-Approved for a St. George Mortgage
1. Determine Your Property Goal
Decide whether you are buying a primary residence, second home, or investment property.
2. Review Credit and Income
Your credit profile and income documentation help determine which mortgage programs may be available.
3. Review Assets and Down Payment
Determine your available funds for the down payment, closing costs, and any required reserves.
4. Compare Mortgage Programs
Compare conventional, FHA, VA, jumbo, bank statement, Non-QM, or other programs that may fit your situation.
5. Establish Your Purchase Range
Mortgage approval and your personal housing budget are not necessarily the same amount. Consider both.
6. Obtain Mortgage Pre-Approval
Once the required information has been reviewed, qualified borrowers can move forward with the applicable pre-approval process.
Learn more about Utah mortgage pre-approval.
Why Work With a Mortgage Broker for a St. George Home?
A bank generally offers mortgage products from its own lending platform.
A mortgage broker may be able to compare programs from multiple wholesale lending sources.
That can be particularly useful when evaluating:
- Conventional financing
- FHA and VA loans
- Jumbo mortgages
- Super jumbo loans
- Self-employed financing
- Bank statement mortgages
- 1099 loans
- P&L loans
- DSCR financing
- Non-QM mortgages
The goal is to compare available financing based on the complete borrower and property scenario instead of assuming one program fits everyone.
Frequently Asked Questions About St. George Utah Mortgage Loans
What mortgage loans are available in St. George, Utah?
Qualified borrowers may have access to conventional, FHA, VA, jumbo, super jumbo, bank statement, 1099, Profit & Loss, DSCR, Non-QM, purchase, and refinance mortgage programs. Availability depends on borrower, property, lender, and program requirements.
What is the 2026 conventional loan limit in St. George?
St. George is located in Washington County. The 2026 conforming loan limit for a one-unit property in Washington County is $832,750.
What is the 2026 FHA loan limit in St. George?
HUD lists the 2026 one-unit FHA forward mortgage limit for Washington County at $607,200. Limits differ for eligible two-, three-, and four-unit properties.
Can I get a jumbo mortgage in St. George?
Yes. Qualified borrowers may use jumbo financing for eligible higher-value properties. Jumbo mortgages can have different credit, reserve, down-payment, income-documentation, and loan-to-value requirements than conforming loans.
Can self-employed borrowers get mortgages in St. George?
Yes. A self-employed borrower may qualify using traditional income documentation or, when eligible, an alternative-documentation program such as a bank statement, 1099, Profit & Loss, asset-based, or other Non-QM mortgage.
Can I finance a second home in St. George?
Potentially. Conventional and jumbo mortgage programs may allow eligible second-home financing. The property, occupancy, and transaction must meet the requirements of the selected program.
Are there St. George mortgage programs for real estate investors?
Yes. Qualified investors may have access to conventional investment-property loans, jumbo financing, DSCR mortgages, and certain Non-QM programs.
Do DSCR loans require traditional employment income?
DSCR programs generally focus more heavily on qualifying property rental income relative to the property's applicable housing obligation. Exact income, credit, reserve, property, and DSCR requirements vary by program.
How do I compare St. George mortgage rates?
Compare the interest rate, APR, points, lender or broker charges, mortgage insurance when applicable, loan term, payment, and estimated closing costs. Compare equivalent loan scenarios rather than looking only at the advertised rate.
How do I get pre-approved for a mortgage in St. George?
Start with a mortgage application and review of your credit, income, assets, debts, down payment, occupancy, property goals, and requested loan amount. Documentation requirements depend on the mortgage program.
Compare St. George Utah Mortgage Loans
Whether you're buying your first Southern Utah home, moving to St. George, refinancing, purchasing a luxury property, buying a second home, investing in real estate, or qualifying with self-employed income, your financing should be evaluated around your specific situation.
Daniel Paris helps qualified borrowers compare conventional, FHA, VA, jumbo, super jumbo, bank statement, 1099, Profit & Loss, DSCR, Non-QM, purchase, and refinance options.
Check My St. George Mortgage Options
Daniel Paris
Utah Mortgage Broker
801-604-4949
UtahLowRate.com
Get a mortgage quote or call to discuss your St. George and Washington County financing scenario.
Independent Mortgage Resources
Borrowers can verify conforming loan limits through the Federal Housing Finance Agency and FHA mortgage limits through the U.S. Department of Housing and Urban Development.
Mortgage programs, interest rates, APRs, loan limits, LTV requirements, credit requirements, and underwriting guidelines can change without notice. All financing is subject to borrower qualification, property eligibility, appraisal requirements, investor guidelines, and underwriting approval. This information is educational and is not a commitment to lend.

