
12-month vs 24-month bank statement loans give Utah business owners two ways to show income. One reviews a year of deposits. The other reviews two years. Compare both to see how growth, slow months and business costs affect your income estimate.
Content updated: .
Compare the period that supports a reliable income analysis.
Quick answer: 12-month vs 24-month bank statement loans use different spans of deposit history. Compare Utah bank statement loan options using both periods. A growing business may show more income over the recent 12 months. A two-year view can show a seasonal pattern. If deposits are falling, an older strong year may not support today’s income. The lender must review the trend and its own rules.
For Utah business owners, the biggest average is not always the best choice. The income must be real, steady enough for the program, and backed by records. A sharp rise or drop may lead to more questions. Daniel Paris at UtahLowRate.com can review both periods for your loan and property.
All dollar figures below are hypothetical. They are not loan offers or approved income figures. We first remove transfers and other deposits that are not business income. Then we use a sample 50% expense factor to show the math. A real lender may use a different method.
Request a Bank Statement Income Review
12-Month vs 24-Month Bank Statement Loans: Key Facts
| Question | 12-month review | 24-month review |
|---|---|---|
| Statement history | Usually 12 consecutive months | Usually 24 consecutive months |
| Main advantage | More emphasis on recent deposits when a program permits | Broader view of recurring and seasonal deposits |
| Main concern | A recent spike may not be sustainable | An older strong year can mask a recent decline |
| Income calculation | Eligible deposits ÷ 12, then applicable expense method | Eligible deposits ÷ 24, then applicable expense method |
| Automatic approval or rate advantage? | No | No |
How Do Lenders Calculate Bank Statement Income?
Start with deposits from the business. Remove transfers, duplicates and deposits that do not count as income. Divide by 12 or 24 months. Then use the expense method that the lender allows. This sample formula shows the idea:
Estimated monthly qualifying income = eligible deposits ÷ months reviewed × assumed income percentage.
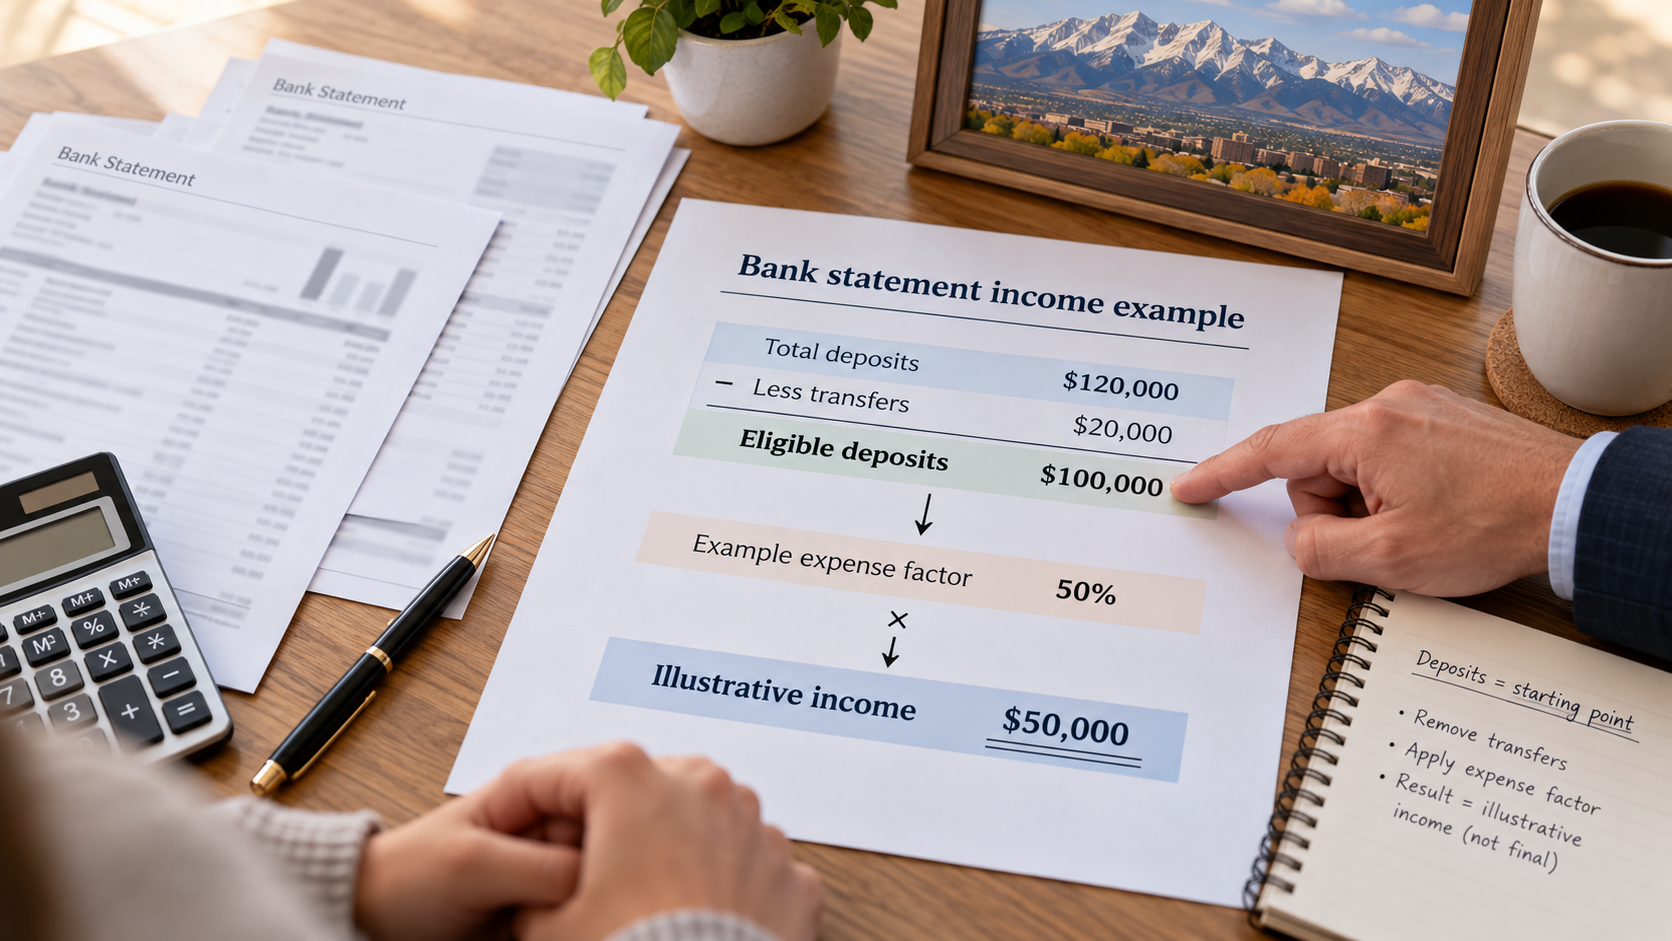
For 12-month vs 24-month bank statement loans, deposit totals are a starting point. The lender sets the final income.
This formula does not decide your approved income. The lender may also check where the money came from, whether deposits are steady, your share of the business, debts and current business activity. Rules for personal accounts can differ from rules for business accounts. See the Bank Statement Loan Income Calculator for more educational examples and the Bank Statement Loan Requirements for the broader qualification review.
What deposits should be removed first?
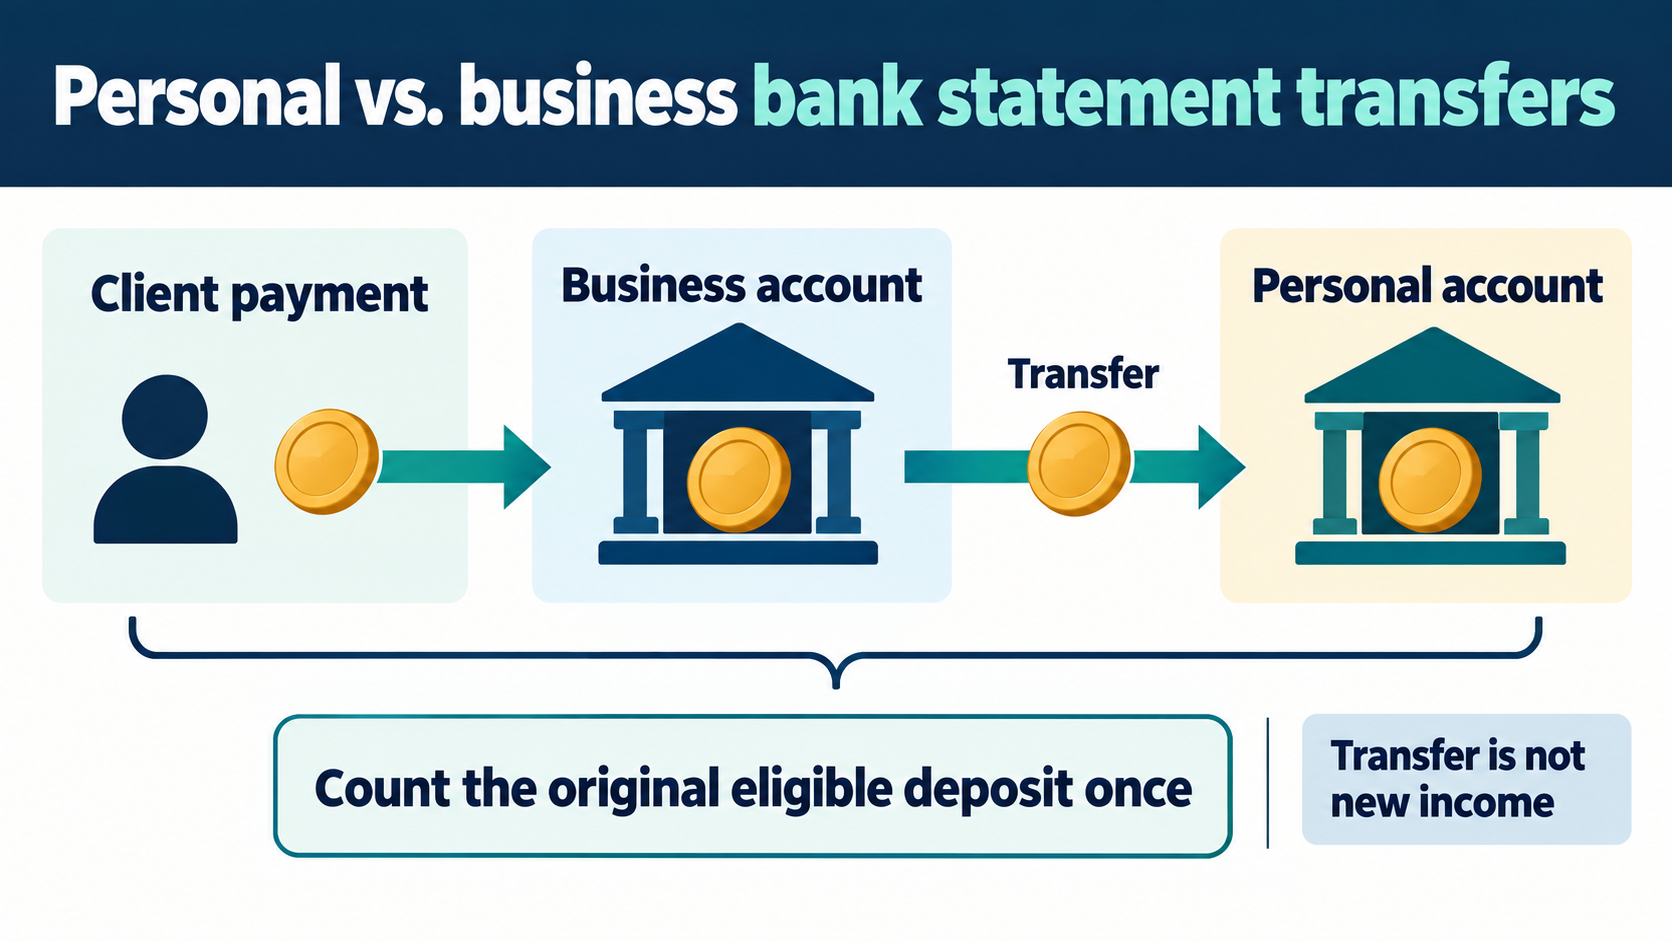
Moving money from a business account to your personal account does not create new income. Loans, refunds and one-time asset sales may not count either. If you use several accounts, show how money moves between them. Keep full statements and explain large or unusual deposits.
Example 1: Growing Utah Business
For this example, a business had $240,000 in deposits in the earlier 12 months and $360,000 in the most recent 12 months. For the sample math, we count half of those deposits as income. This is an example, not a lender rule.
| Period | Calculation | Illustrative monthly income |
|---|---|---|
| Recent 12 months | $360,000 ÷ 12 × 50% | $15,000 |
| Full 24 months | ($240,000 + $360,000) ÷ 24 × 50% | $12,500 |
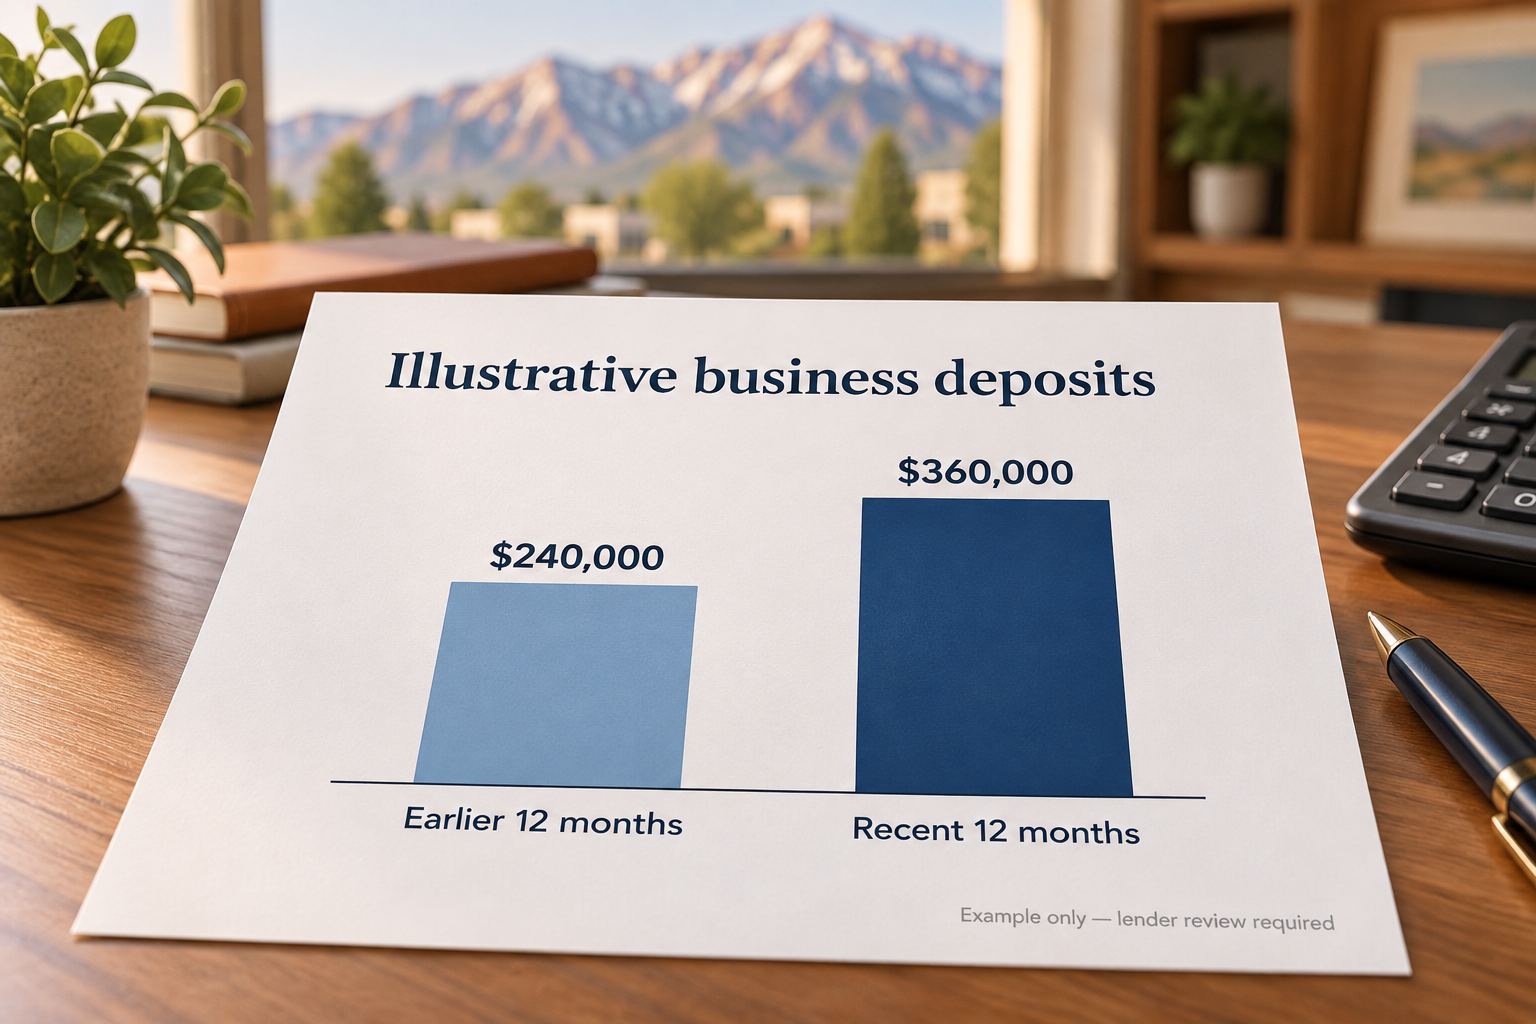
Recent growth can change the average, subject to lender review.
The 12-month figure is $2,500 higher per month. This may help a business that has grown. The lender will still ask why sales rose and whether they are likely to continue. A higher result on paper does not mean the lender will use it.
A Lehi consultant with several new clients is different from a firm paid for one large job. The source of the money matters. Read the Utah County and Lehi bank statement guide for local financing context.
Example 2: Declining Deposits
Now reverse the pattern: $360,000 in the earlier year and $240,000 in the recent year, using the same illustrative 50% assumption.
| Period | Calculation | Illustrative monthly income |
|---|---|---|
| Recent 12 months | $240,000 ÷ 12 × 50% | $10,000 |
| Full 24 months | ($360,000 + $240,000) ÷ 24 × 50% | $12,500 |
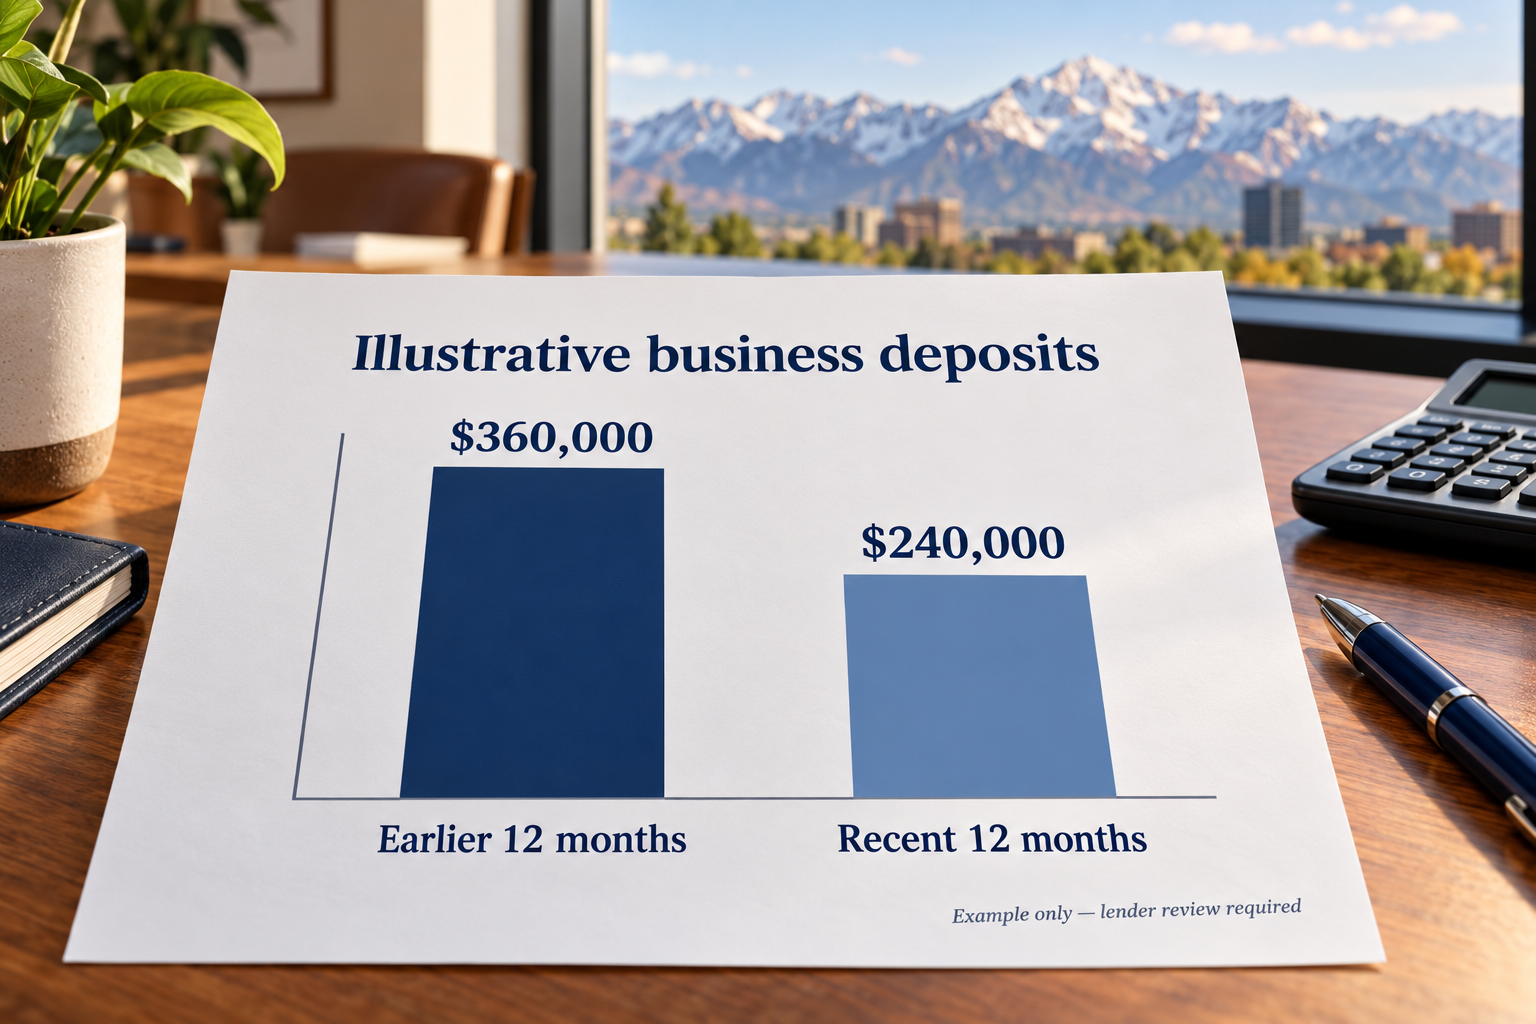
An older strong year may overstate current performance.
The 24-month figure is $2,500 higher per month. Yet it includes a stronger older year. If sales are still falling, the lender may use a lower figure or ask for more records. Explain the drop and ask which income figure the program can support.
A Salt Lake City owner who lost a major client may face a different review from one who can document a short pause in work. The details matter. See Bank Statement Loans Salt Lake City.
Example 3: Seasonal Utah Business
Consider a Wasatch Back service business with busy summer and winter periods. Eligible deposits total $270,000 in the first year and $330,000 in the second. The last year includes busy and slow months. The two-year view shows two full business cycles.
| Period | Calculation at illustrative 50% | Illustrative monthly income |
|---|---|---|
| Recent 12 months | $330,000 ÷ 12 × 50% | $13,750 |
| Full 24 months | $600,000 ÷ 24 × 50% | $12,500 |
A complete annual cycle matters for seasonal revenue.
The 12-month figure is $1,250 higher per month. The two-year record shows whether busy seasons tend to repeat. The latest year shows more recent results. Both periods cover complete years; a few strong months alone do not show a full business cycle.
A Heber Valley contractor, Park City hospitality business or St. George outdoor-services business may have seasonal deposits for different reasons. Show when your business earns income. A longer review does not always help you qualify. Explore the Heber City and Wasatch Back guide, Park City guide and St. George guide.
What If You Have Only One Year of Self-Employment?
A year of bank records does not prove you meet the time-in-business rule. The lender checks how long you have worked for yourself. Prior work may also matter. Ask for a review of your work history.
Personal vs. Business Bank Statements
Deposits paid into a personal account may be reviewed under different rules. Business account calculations often include a business expense factor. If you use both kinds of account, mark transfers so the same payment is counted once. Ask which method your lender permits.
If your tax returns show less income than your business deposits suggest, read Can You Buy a House Using Bank Statements Instead of Tax Returns?. Bank statement financing remains fully underwritten and is not a no-documentation mortgage.
Do 12-Month and 24-Month Programs Have Different Rates?
The two periods may open different program options. Neither one always has a lower rate. Credit, down payment, loan size, property use and other factors also affect pricing. Compare rate, APR, fees and cash to close for the same loan scenario. Visit Bank Statement Loan Rates Utah for current pricing considerations, or use the Utah Mortgage Rates page in the meantime.
The Consumer Financial Protection Bureau explains how to compare Loan Estimates. Tell each lender you are self-employed so the offers reflect your situation.
For a higher loan amount in Park City, Deer Valley, Alpine or Holladay, compare Jumbo Bank Statement Loans Utah. A jumbo investor's statement period, reserve and property rules may differ from those of a smaller loan.
How to Compare 12-Month vs 24-Month Bank Statement Loans Options
- Collect complete statements. If available, assemble 24 consecutive months for each account used, even if you hope to qualify with 12. Ask the lender what it actually needs.
- Separate eligible revenue from other deposits. Flag transfers, refunds, loans, unusual one-time deposits and duplicate entries.
- Calculate both periods consistently. Compare recent 12-month and full 24-month eligible averages using the same illustrative expense assumption first; then apply each real investor's permitted method.
- Explain the trend. Identify client growth, lost contracts, business changes, seasonality or unusual events that caused the difference.
- Compare the whole loan. Review qualifying income alongside credit, down payment or equity, reserves, property eligibility, interest rate, APR and fees.
Moving money between accounts does not create new income.
The income calculator can organize an initial estimate. A lender must still verify the deposits and approve the final income. For more underwriting questions, visit the Bank Statement Loan FAQ.
Common Mistakes to Avoid
- Counting transfers into a personal account after already counting the original business deposit.
- Treating gross deposits as take-home income without an investor-approved expense method.
- Comparing different 12- and 24-month periods without identifying the dates used.
- Assuming a high two-year average overrides a recent sustained decline.
- Using a few seasonal peak months as if they represented a full year.
- Assuming that 12 months of statements means one year of self-employment is sufficient.
- Selecting a program by its estimated income alone without comparing rate, APR, closing costs and property rules.
Frequently Asked Questions
Is a 12-month bank statement mortgage easier to qualify for?
No. A one-year review may show more or less income. Each lender sets its own rules. Credit, cash and property checks still apply.
Can I use 24 months if my last year was weaker?
An available lender may review 24 months, but it can also consider a recent decline. The lender may not accept the higher two-year average as income.
Which period is better for seasonal income?
One full year shows one business cycle. Two years show two cycles. Compare 12-month vs 24-month bank statement loans based on your deposit trend and the lender’s rules.
Are the months required to be consecutive?
Most programs ask for months in a row, with no gaps. Ask which dates to use. You may also need records for the current month.
Can I combine two business accounts?
Yes, if the lender allows both accounts and the deposits count as income. Mark transfers between accounts. Count each payment only once.
Will 24 months always get me a better interest rate?
No. The review period is only one part of loan pricing. Ask for written quotes for the same loan amount, property and down payment.
Review 12-month vs 24-month bank statement loans before you choose a program.
Ask Daniel Paris to Compare Both Periods
If you are self-employed in Utah, send your business type, years in business, account types and rough deposits for each year. Add the property location, loan purpose and down payment or equity. Daniel can compare the available paths with your actual records.
Estimate My Bank Statement Income · Apply or request a review · Call 801-604-4949
Daniel Paris | UtahLowRate.com | Utah Mortgage Broker | NMLS #243976. Program availability and terms vary by lender and are subject to full underwriting. Illustrative figures do not constitute a loan offer or guarantee of approval.
Request a Bank Statement Income Review · Call Daniel Paris: 801-604-4949

