
Can I Buy a House Using Bank Statements Instead of Tax Returns?
Last Updated: September 2026
Yes. You may be able to buy a house using bank statements instead of tax returns if you are self-employed and qualify for a bank statement mortgage. Instead of relying primarily on taxable income shown on your federal tax returns, an eligible lender may calculate qualifying income using deposits from your personal or business bank statements.
This type of mortgage can be useful for business owners, independent contractors, entrepreneurs and other self-employed Utah homebuyers whose tax returns may not fully reflect their business cash flow. You can also compare other self-employed mortgage options in Utah if bank statement financing is not the best fit.
A bank statement mortgage is not a no-income-verification loan. Your income, credit, debts, assets, reserves, down payment or equity, property and other factors still must meet the applicable lender’s underwriting requirements.
For a complete overview, start with the Bank Statement Loans Utah guide.
Quick Answer: Can You Buy a House Using Bank Statements Instead of Tax Returns?
Yes. Certain mortgage programs allow eligible self-employed borrowers to buy a house using bank statements instead of tax returns as the primary method for calculating qualifying income.
Depending on the program, a lender may review 12 or 24 months of personal or business bank statements. The lender identifies eligible recurring deposits, removes transfers and other non-income deposits, and may apply a business-expense calculation when business statements are used.
Your final eligibility depends on the specific loan program and your complete financial profile. Review the bank statement loan requirements for Utah borrowers for a closer look at documentation, credit, reserves and other underwriting factors.
Key Facts About Bank Statement Mortgages
- Designed primarily for self-employed borrowers and business owners
- 12- and 24-month bank statement programs may be available
- Personal or business statements may be eligible
- Tax returns may not be the primary method used to calculate qualifying income
- Business deposits may require an expense calculation
- Purchase, refinance and cash-out options may be available
- Jumbo bank statement mortgages may be available
- Credit, LTV, reserves and documentation requirements vary by lender
- Available programs and guidelines can change
The federal Ability-to-Repay rule generally requires covered mortgage lenders to make a reasonable, good-faith determination that a borrower can repay the loan. See the Consumer Financial Protection Bureau’s Ability-to-Repay explanation.
Why Buy a House Using Bank Statements Instead of Tax Returns?
Self-employed borrowers often have financial profiles that look very different from those of W-2 employees.
A business may generate substantial revenue while also having legitimate expenses for advertising, equipment, insurance, employees, vehicles, office space, depreciation and other operating costs.
Those expenses can reduce taxable income.
As a result, the income appearing on a business owner’s tax returns may be much lower than the cash flow moving through the business.
That difference can become important when applying for a mortgage.
Traditional conventional underwriting often uses tax documentation and cash-flow analysis when self-employment income is needed to qualify. Fannie Mae maintains specific tax-return and transcript documentation requirements.
A bank statement mortgage uses a different approach. Borrowers who are unsure which documentation method fits their situation should also review the broader Self-Employed Mortgage Utah guide.
Instead of focusing primarily on:
“How much taxable income appears on my tax returns?”
the lender may evaluate:
“How much eligible recurring income can be documented through my bank deposits?”
This can make bank statement financing worth exploring for Utah business owners, independent contractors, consultants, real estate professionals, medical professionals, tradespeople, restaurant owners and other qualifying self-employed borrowers.
How Does a Bank Statement Mortgage Work?
A bank statement mortgage uses eligible deposits over a specific period to help determine qualifying income.
Depending on the loan program, you may provide:
- 12 months of personal bank statements
- 24 months of personal bank statements
- 12 months of business bank statements
- 24 months of business bank statements
- Additional supporting documents required by the lender
The lender reviews the statements and identifies deposits that may represent eligible recurring income.
Transfers between accounts, loan proceeds and deposits that do not represent income may need to be removed from the calculation.
Business statements require another important step.
Gross business deposits do not automatically equal qualifying personal income.
The lender may apply an approved expense methodology to determine how much of the eligible business revenue can be treated as qualifying borrower income.
See the Bank Statement Loan Income Calculator for a step-by-step explanation of how eligible deposits may translate into estimated mortgage qualifying income.
Bank Statement Income Calculation Example
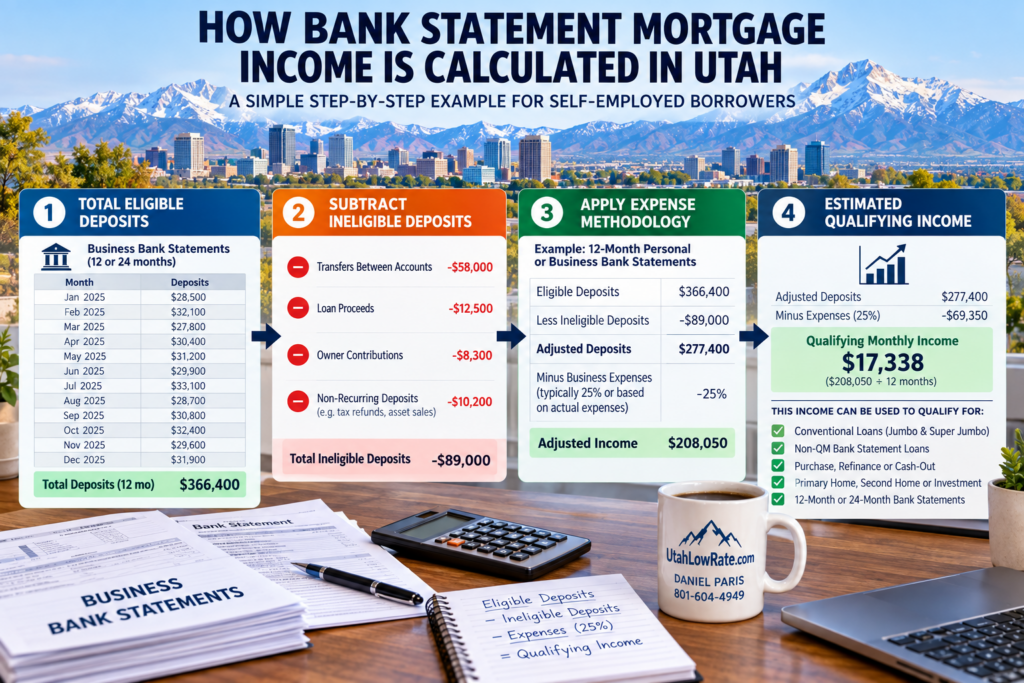
Suppose a Utah business averages $40,000 per month in eligible deposits.
If the applicable loan program and approved expense methodology result in 50% of those deposits being treated as qualifying income:
$40,000 × 50% = $20,000 estimated monthly qualifying income
This is only an educational example.
There is no universal 50% formula for every bank statement mortgage.
A lender may calculate income differently depending on the business, account type, ownership percentage, expense methodology and investor guidelines.
Before deciding how much home to purchase, use the bank statement income calculation guide and worksheet to understand the basic calculation process.
Do I Need 12 or 24 Months of Bank Statements?
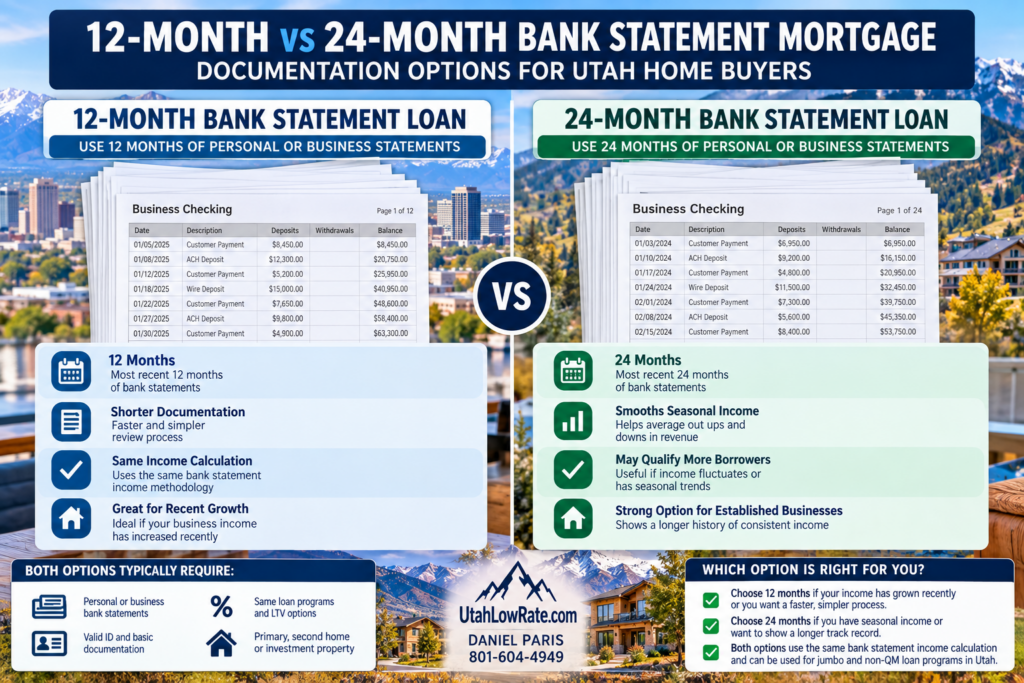
Many bank statement mortgage programs review either 12 or 24 months of statements.
Neither option is automatically better.
A 12-month program uses a shorter review period. This may be helpful when recent business income is stronger than income from the previous year.
A 24-month review provides a longer history. It may help demonstrate consistent deposits and provide a better picture of seasonal income.
For example, suppose a Utah business grew significantly during the past year. Its 12-month average could be very different from its 24-month average.
The opposite can also occur.
The appropriate documentation period depends on your actual deposit history and the programs available to you.
See the complete Bank Statement Loan Requirements Utah guide for more information about statement periods, documentation, self-employment and underwriting.
Can I Use Personal Bank Statements to Buy a House?
Potentially, yes.
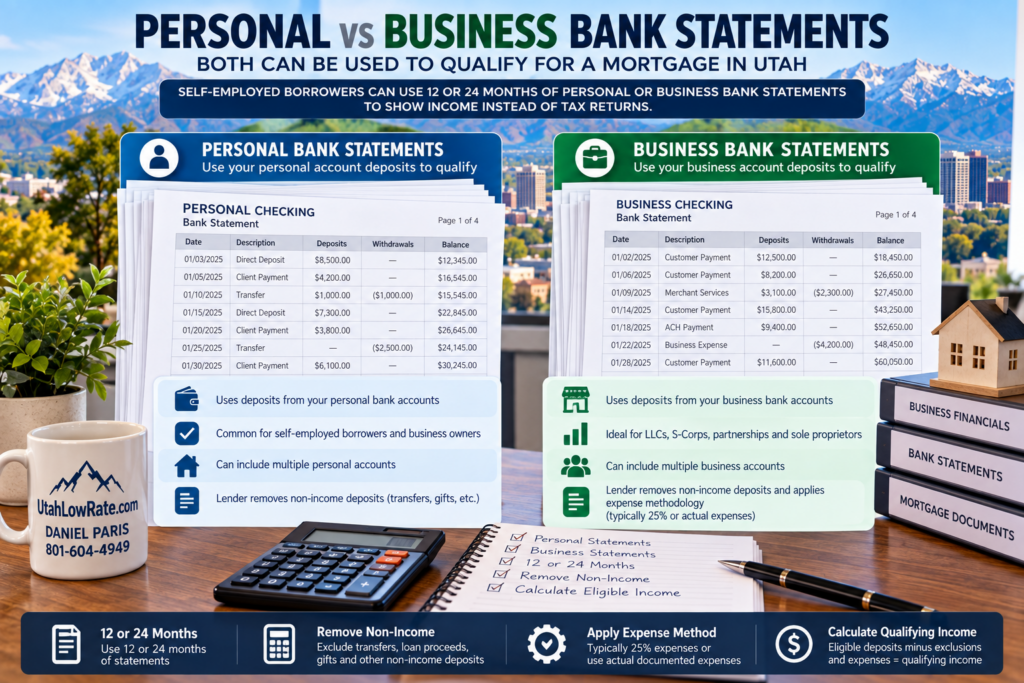
Some programs allow eligible borrowers to qualify using personal bank statements.
This approach may work when business income or distributions regularly flow into your personal account.
The lender still determines which deposits can be counted as income.
Transfers between accounts, unusually large deposits and money from non-income sources may need to be documented or excluded.
Do not assume that personal statements will always produce a higher qualifying income than business statements.
The best option depends on your accounts, deposit history and available mortgage programs. The Bank Statement Loan FAQ answers additional questions about personal statements, deposits, transfers and income documentation.
Can I Use Business Bank Statements to Buy a House?
Yes. Certain bank statement mortgage programs allow eligible borrowers to use business bank statements.
This may be particularly useful when most of your business revenue flows through a company account.
However:
Business revenue does not automatically equal personal qualifying income.
A company can have strong revenue and significant operating expenses at the same time.
The lender therefore needs a method for estimating how much of the eligible business revenue may be treated as qualifying borrower income.
This is an important area where bank statement programs can differ.
Two programs could review the same deposits and produce different qualifying-income calculations because their permitted expense methodologies are different. Review the Bank Statement Loan Income Calculator for an example of how eligible deposits, exclusions and expense calculations can affect estimated qualifying income.
Can I Buy a House Using Bank Statements Instead of Tax Returns If My Taxable Income Is Low?
Potentially.
This is one of the primary reasons self-employed borrowers consider bank statement mortgages.
Suppose your business generates healthy recurring revenue, but legitimate business deductions substantially reduce the taxable income shown on your returns.
A traditional mortgage and a bank statement mortgage may calculate your qualifying income differently.
That does not mean tax deductions are simply ignored or automatically added back.
It means the bank statement program may use a different approved method for documenting and calculating income.
Self-employed borrowers should compare bank statement financing with other Utah self-employed mortgage options rather than assuming one documentation method will always produce the best result.
The lender still evaluates your complete financial profile, including:
- Qualifying income
- Credit history
- Existing debts
- Assets
- Reserves
- Down payment or equity
- Property type
- Occupancy
- Loan-to-value ratio
- Requested loan amount
Large deposits alone do not guarantee mortgage approval.
Who May Qualify for a Bank Statement Loan?
Bank statement mortgages are generally designed for borrowers whose income does not fit neatly into traditional W-2 documentation.
Potential candidates can include:
- Business owners
- Independent contractors
- Consultants
- Entrepreneurs
- Real estate professionals
- Commission-based professionals
- Medical professionals
- Tradespeople
- Other qualifying self-employed borrowers
The key question is not simply how much money enters your account.
The lender needs to determine how much of those deposits can be treated as qualifying income under the applicable mortgage program.
For answers about credit, down payments, deposits, reserves, property types and documentation, visit the Bank Statement Loan FAQ.
Can I Buy a House Using Bank Statements With a Jumbo Mortgage?
Potentially, yes.
Certain jumbo bank statement programs provide alternative income documentation for qualifying self-employed borrowers purchasing or refinancing higher-value homes.
This can be particularly relevant in Utah luxury markets such as:
Park City, Deer Valley, Salt Lake City, Holladay, Draper, Alpine, Highland, Heber City and Midway.
A jumbo bank statement transaction involves more than finding a lender that accepts bank statements.
The complete transaction may include:
Loan amount + property value + LTV + credit + liquidity + reserves + qualifying income + occupancy
A self-employed borrower purchasing a luxury residence in Park City may therefore have different requirements from a borrower purchasing a primary residence in Salt Lake County.
For higher-balance alternative-documentation financing, visit Jumbo Bank Statement Loans Utah. You can also compare broader Utah jumbo mortgage options when traditional income documentation may work.
Bank Statement Loan vs. Conventional Mortgage
The biggest difference is how qualifying income may be documented and calculated.
Conventional Mortgage
A conventional mortgage may be a good option when your qualifying self-employment income under conventional guidelines supports the requested loan.
Tax returns and other documentation may be required depending on the transaction and underwriting findings.
Bank Statement Mortgage
A bank statement mortgage provides an alternative way to document income for an eligible borrower.
Instead of relying primarily on tax-return income, qualifying deposits may be analyzed under the lender’s bank statement program.
That flexibility does not automatically make a bank statement loan better or cheaper than a conventional mortgage.
Interest rates, fees, down payment requirements, reserves, credit requirements, LTV limits and underwriting standards may differ.
Borrowers should also compare current Utah mortgage rate information because bank statement mortgage pricing can differ from conventional mortgage pricing.
What Documents Do I Need for a Bank Statement Mortgage?
Requirements vary by lender and program, but borrowers may need to provide:
- 12 or 24 months of applicable bank statements
- Government-issued identification
- Evidence of self-employment
- Business documentation
- Asset statements
- Reserve documentation
- Housing history
- Purchase contract for a home purchase
- Documentation or explanations for certain deposits
Additional documentation may be required depending on the borrower, business, property and loan program.
Before applying, review the full Bank Statement Loan Requirements Utah guide.
How Much House Can I Buy Using Bank Statement Income?
Your purchasing power depends partly on the amount of qualifying monthly income the mortgage program calculates from your bank statements.
But income is only one part of the equation.
Mortgage qualification may also depend on:
- Credit profile
- Down payment
- Existing monthly debts
- Cash reserves
- Property taxes
- Homeowners insurance
- HOA dues
- Interest rate
- Loan structure
- Property type
- Occupancy
- Loan amount
Consider two business owners who each deposit $50,000 per month.
One operates a business with high overhead. The other operates a business with relatively low expenses.
Their gross deposits are identical, but their qualifying income may not be.
The more useful question is therefore not:
“How much money does my business deposit?”
It is:
“How much of my eligible deposits can a bank statement mortgage program use as qualifying income?”
Use the Bank Statement Loan Income Calculator to learn how the basic deposit analysis works.
Bank Statement Loans for Self-Employed Utah Homebuyers
Bank statement financing may be available to qualifying borrowers throughout Utah.
Areas commonly served include:
Salt Lake City, Murray, Holladay, Cottonwood Heights, Sandy, Draper, South Jordan, Riverton, Herriman, Lehi, Provo, Orem, Alpine, Highland, Park City, Deer Valley, Heber City, Midway, St. George, Washington and surrounding Utah communities.
Financing needs can vary by market.
A Salt Lake City business owner purchasing a primary residence may have a different loan amount and financial profile from a self-employed luxury-home buyer in Park City or Deer Valley.
Self-employed borrowers in Salt Lake County can review Bank Statement Loans Salt Lake City.
Borrowers in Lehi, Provo, Orem, Alpine, Highland and surrounding communities can review Bank Statement Loans Utah County & Lehi.
Borrowers purchasing in Heber City, Midway, Jordanelle and the Wasatch Back can review Bank Statement Loans Heber City Utah.
For statewide program information, return to the main Bank Statement Loans Utah resource.
How to Start if You Want to Buy a House Using Bank Statements Instead of Tax Returns
The first step is usually to determine how an available bank statement program may calculate your income.
A preliminary review generally follows this process:
Eligible deposits → remove excluded deposits → calculate average eligible deposits → apply appropriate expense methodology → estimate qualifying monthly income
Then the rest of the mortgage profile can be evaluated.
That includes your credit, debts, assets, reserves, property, occupancy, down payment or equity, LTV and requested loan amount.
Do not assume your gross business deposits equal mortgage qualifying income.
And do not assume one lender’s income calculation represents every bank statement mortgage program.
If you are ready to move from research to qualification, you can start a Utah mortgage application or call 801-604-4949 to discuss your bank statement scenario first.
Talk With a Utah Bank Statement Mortgage Broker
If you are self-employed and your tax returns do not show enough qualifying income for the home you want to purchase, a bank statement income review can help determine whether an alternative-documentation mortgage is worth exploring.
Daniel Paris
Utah Mortgage Broker — NMLS #243976
UtahLowRate.com
Phone: 801-604-4949
Serving borrowers throughout Utah, including Salt Lake City, Salt Lake County, Park City, Deer Valley, Draper, Utah County, Lehi, Heber City, St. George and Washington County.
Mortgage specialties: Bank statement mortgages, self-employed home loans, jumbo bank statement mortgages and alternative-documentation financing.
Start your mortgage application or call 801-604-4949 to request a bank statement mortgage review.
Frequently Asked Questions About Buying a House With Bank Statements
Can I buy a house using bank statements instead of tax returns?
Yes. Certain alternative-documentation mortgage programs may allow eligible self-employed borrowers to establish qualifying income using personal or business bank statements instead of relying primarily on tax-return income. Complete underwriting requirements still apply. See the Bank Statement Loans Utah guide for a complete overview.
How many months of bank statements do I need to buy a house?
Many programs review either 12 or 24 months of bank statements. The required period depends on the mortgage program, investor and borrower profile. Review the Bank Statement Loan Requirements Utah page for documentation details.
Can I use business bank statements to qualify for a mortgage?
Yes. Certain programs permit eligible business bank statements. The lender analyzes eligible deposits and may apply an approved expense methodology to estimate qualifying borrower income. The Bank Statement Loan Income Calculator explains this process in more detail.
What if my tax returns show very little income?
A bank statement mortgage may be worth exploring when legitimate business deductions reduce taxable income but your business has consistent, documentable cash flow. Eligibility depends on the applicable program and your complete financial profile.
Are bank statement mortgages no-income-verification loans?
No. A bank statement mortgage is not a no-income-verification loan. Income is still documented and analyzed. Bank statements simply provide an alternative method of establishing qualifying income under eligible programs.
Can I get a jumbo mortgage using bank statements in Utah?
Potentially. Certain jumbo bank statement mortgage programs in Utah may be available to qualifying self-employed borrowers. Requirements for loan amount, credit, LTV, reserves, liquidity, property and income vary by lender and investor.
Are bank statement mortgage rates higher than conventional rates?
They can be different because bank statement mortgages generally use alternative documentation and may fall outside standard agency underwriting. Actual pricing depends on credit, LTV, loan amount, property type, occupancy and the available program. See Utah mortgage rates and rate factors for additional rate information.
Do I have to be self-employed to use a bank statement mortgage?
Most bank statement mortgage programs are designed primarily for self-employed borrowers. Exact eligibility and minimum self-employment history vary by lender and investor. The Self-Employed Mortgage Utah guide explains additional mortgage options for business owners.
Related Bank Statement Mortgage Resources
Continue your research with these UtahLowRate.com resources:
- Bank Statement Loans Utah — Statewide bank statement mortgage hub.
- Bank Statement Loan Requirements Utah — Documentation and qualification requirements.
- Bank Statement Loan Income Calculator — Estimate how eligible deposits may translate into qualifying income.
- Bank Statement Loan FAQ — Answers to common bank statement mortgage questions.
- Jumbo Bank Statement Loans Utah — Higher-balance alternative-documentation financing.
- Bank Statement Loans Salt Lake City — Salt Lake City and Salt Lake County.
- Bank Statement Loans Utah County & Lehi — Lehi, Provo, Orem and Utah County.
- Bank Statement Loans Heber City Utah — Heber City, Midway and the Wasatch Back.
- Self-Employed Mortgage Utah — Compare other income-documentation and mortgage options.
- Utah Mortgage Rates — Current rate context and mortgage pricing factors.
Important Mortgage Disclosure
Bank statement mortgage guidelines, rates, fees, loan amounts, credit requirements, LTV limits, reserve requirements and income-calculation methods vary by lender and investor and can change.
Examples and calculations on this page are for educational purposes only. They are not a commitment to lend, loan approval, pre-approval, rate quote or guarantee of qualifying income, loan amount, terms or program availability.
Actual mortgage eligibility and qualifying income are determined after review of the borrower’s complete financial profile, documentation, property and applicable loan guidelines.

