
Content updated: .
Compare the full loan offer before choosing a rate.
Request a Bank Statement Income Review
Compare the Whole Mortgage Quote
Quick answer: Bank statement loan rates in Utah depend on the borrower’s credit, down payment or equity, loan amount, property use, documentation, reserves, loan term and the lender’s pricing. The interest rate alone does not show the full cost. Compare the APR, discount points, lender fees, cash needed at closing, rate-lock terms and any permitted prepayment provision on otherwise similar offers.
A self-employed buyer in Salt Lake City and a business owner purchasing a second home in Park City can receive different quotes even on the same day. Their loan amounts, occupancy, credit, equity and bank-deposit histories may differ. Daniel Paris at UtahLowRate.com helps qualifying borrowers compare available wholesale programs rather than assuming that one posted rate applies to every transaction.
Rates are not quoted on this page. Mortgage pricing changes, and the available terms depend on a complete scenario and lender review. Request a personalized quote before making a financing decision.
Bank Statement Mortgage Rate Quick Facts
| Question | Practical answer |
|---|---|
| Who uses these loans? | Primarily qualifying self-employed borrowers whose eligible personal or business deposits can support an alternative income analysis. |
| Are rates identical to conventional rates? | No universal spread applies. Compare actual offers for the same borrower and property. |
| Does a lower rate mean a cheaper loan? | Not necessarily. Points, fees, APR and time in the loan matter. |
| Do 12 versus 24 months affect pricing? | The documentation path can affect program eligibility and available pricing; it is not a universal rate adjustment. |
| Can I lock a quoted rate? | Ask when a lock is available, its duration, cost, expiration and any extension policy. |
| Are prepayment penalties standard? | No. Availability and terms vary; ask whether one is permitted and shown in the proposed documents. |
Explore the statewide bank statement mortgage guide and bank statement loan requirements if you are still deciding whether this documentation approach fits.
What Affects Bank Statement Loan Rates in Utah?
Credit score and credit history
Credit can affect which lenders will consider an application and how they price the available loan. A stronger score may improve an offer, but no single minimum or price adjustment applies to every investor. Recent mortgage history and other credit events may also matter. Ask for a scenario review before assuming that a published credit threshold guarantees a particular rate.
Down payment, loan-to-value ratio and equity
Loan-to-value ratio (LTV) compares the loan amount with the property's value or eligible transaction value. A larger down payment or more refinance equity can change program eligibility and pricing. Compare the added cash required against the potential monthly savings; keeping more cash in reserves may also matter to a self-employed borrower.
Loan amount and property use
A modest primary-home purchase, a jumbo loan and a second-home purchase are different transactions. Investor pricing may change with loan size, property type and occupancy. For a higher-balance purchase, visit Jumbo Bank Statement Loans Utah and Jumbo Mortgage Utah. Investment-property borrowers should also compare the Utah DSCR mortgage option if property cash flow is more relevant than personal business deposits.
Bank statement income and documentation
Programs commonly evaluate 12 or 24 months of eligible personal or business deposits. Transfers between accounts, loan proceeds and other non-income deposits must be reviewed rather than counted twice. Business expenses and the selected investor's method affect the resulting qualifying income. A cleaner, supportable file may open more program options, though it does not guarantee a lower rate. Try the bank statement loan income calculator for an educational estimate and read the 50-question FAQ for document issues.
Loan term, fixed or adjustable structure, and interest-only payments
A 30-year fixed loan, an adjustable-rate mortgage and an interest-only structure can have different rates, payments and risks. Compare the future adjustment terms and payment schedule, not only the first payment. Availability depends on the program and transaction. Request a written comparison for the structure you actually intend to keep.
Points, lender credits and rate lock
Discount points are an upfront cost paid to reduce the rate; the reduction is specific to the offer. A lender credit may reduce upfront costs in exchange for a higher rate. Ask whether pricing is locked and compare quotes issued close together with matching assumptions and lock periods. See the CFPB explanation of points and lender credits.
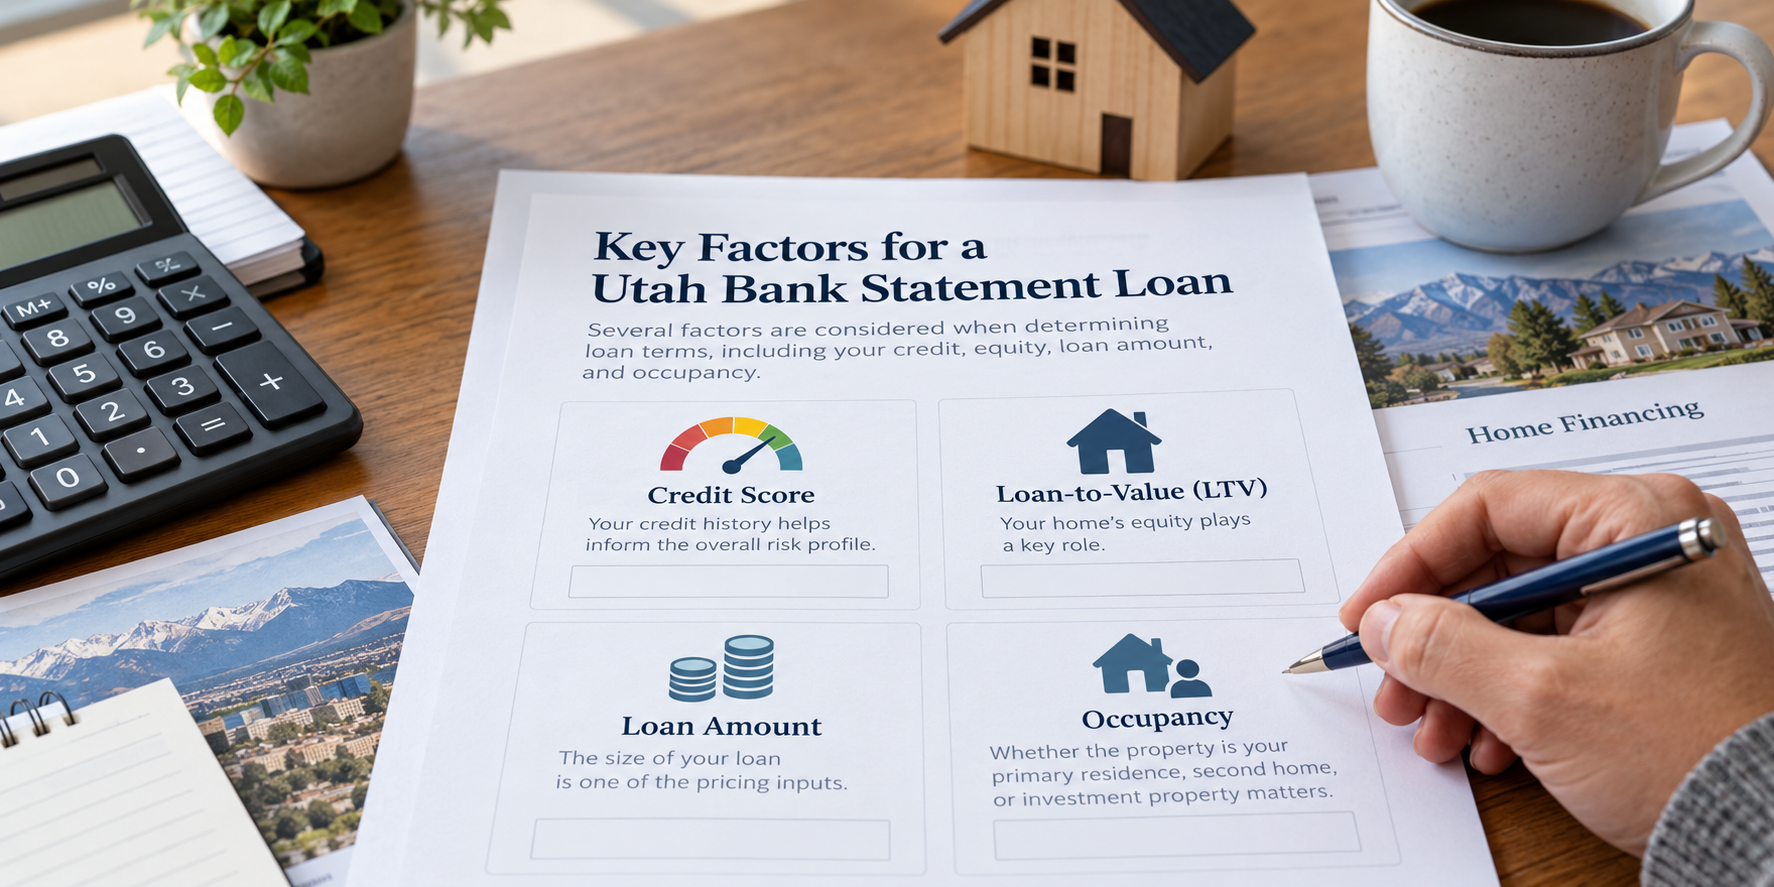
Credit and equity are among several pricing inputs.
Interest Rate vs. APR: Which Number Should I Compare?
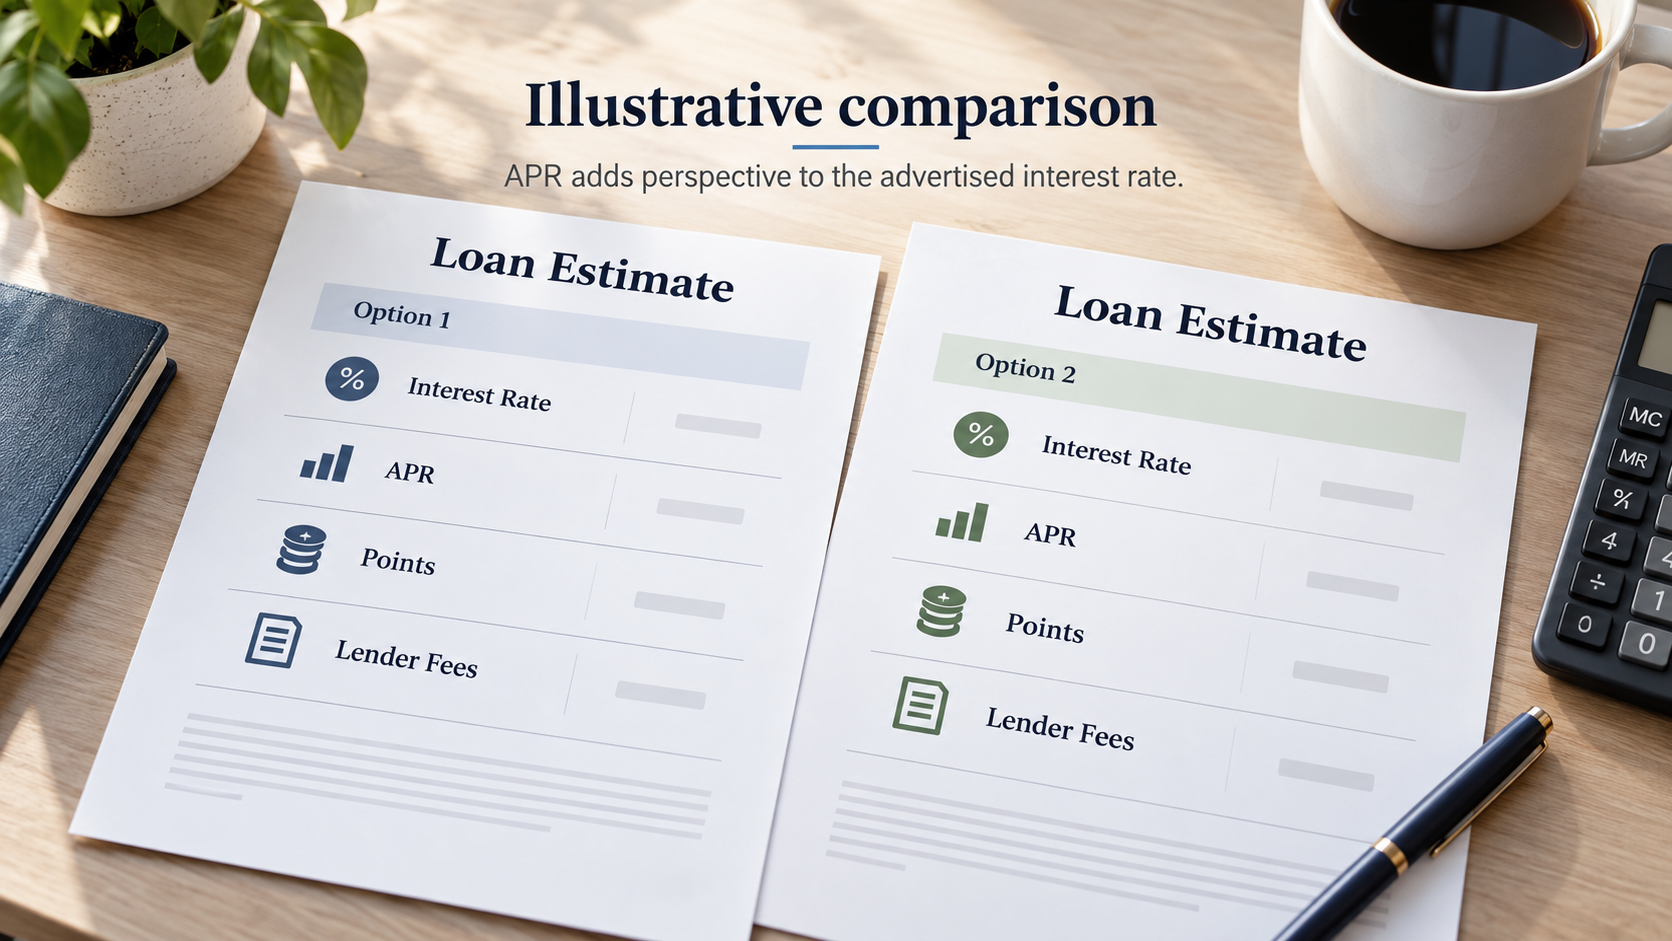
APR adds perspective to the advertised interest rate
The interest rate helps determine the principal-and-interest payment. Annual percentage rate (APR) is a broader measure that reflects the rate plus certain financing charges, including applicable points and other charges. APR does not replace a review of closing cash, monthly payment and how long you plan to retain the loan. The CFPB explains the rate and APR distinction.
On a Loan Estimate, look for the rate on page 1 and APR in the comparison section on page 3. Compare loans with the same amount, term, occupancy, property, lock period and requested structure. When one offer includes points and another does not, ask for a matched comparison before calling either one cheaper.
| Compare | Offer A | Offer B |
|---|---|---|
| Interest rate and APR | Enter written terms | Enter written terms |
| Discount points and lender fees | Enter dollar amounts | Enter dollar amounts |
| Monthly principal and interest | Enter payment | Enter payment |
| Estimated cash to close | Enter amount | Enter amount |
| Rate lock expiration | Enter date | Enter date |
| Prepayment terms, if any | Enter exact provision | Enter exact provision |
This worksheet is a comparison template, not an illustration of available loan terms. The CFPB Loan Estimate guide explains where to find these figures.
Should You Pay Points on a Utah Bank Statement Mortgage?
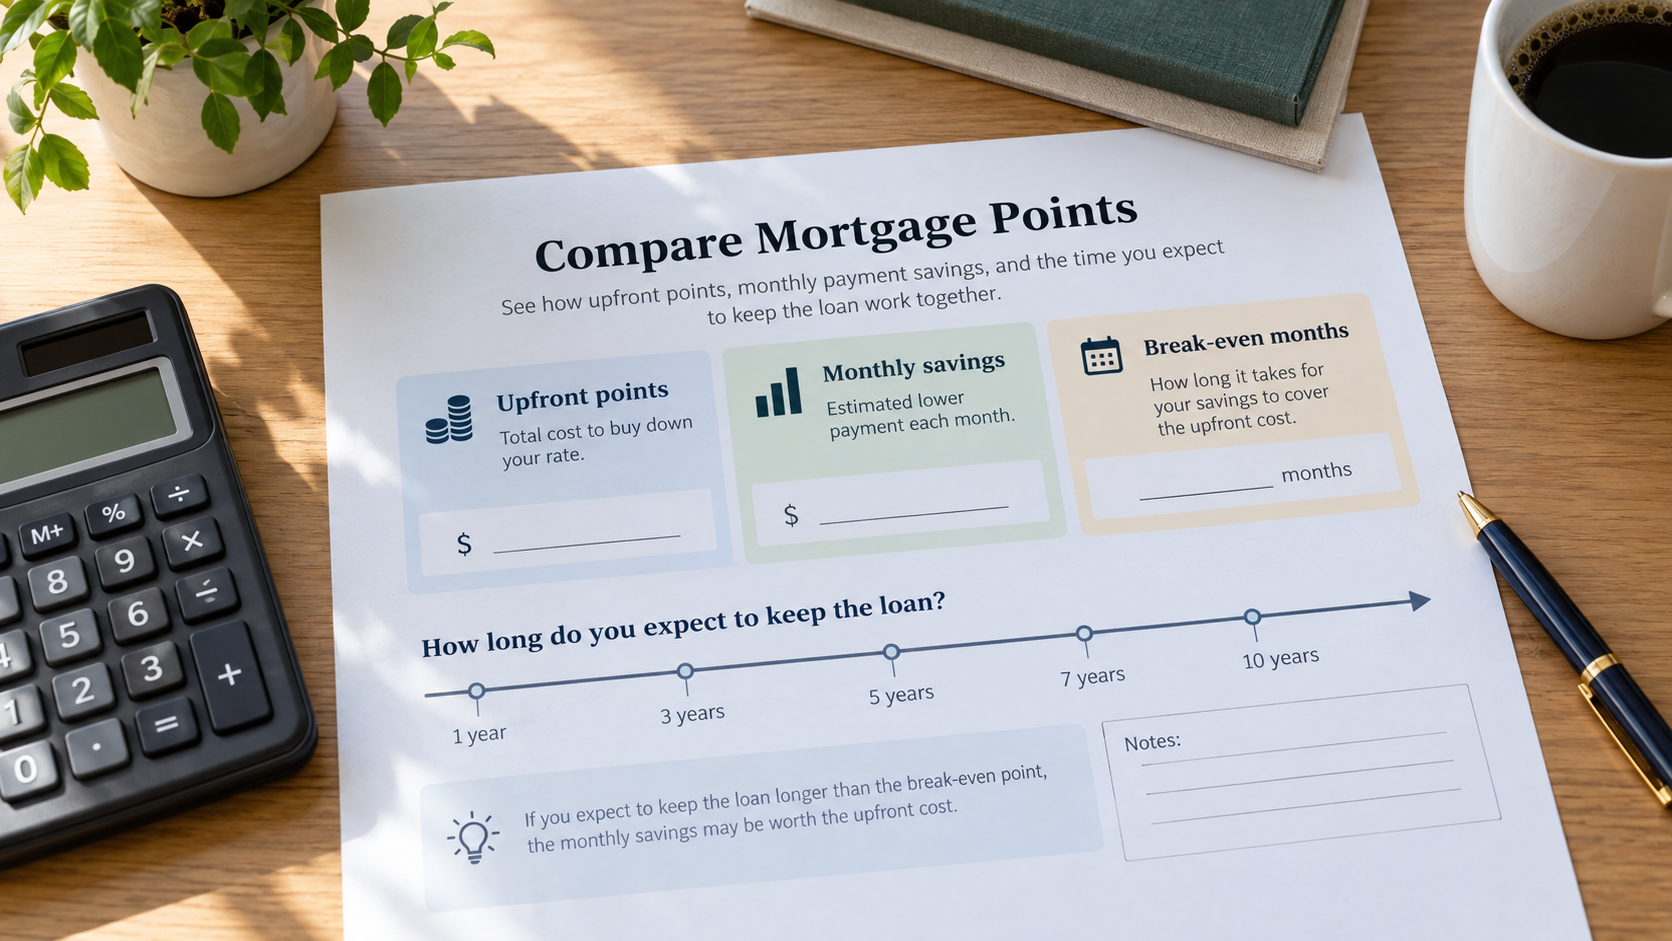
Ask for two written versions of the same loan: one with points and one with fewer or no points. Calculate the additional upfront cost ÷ monthly principal-and-interest savings to estimate the number of months needed to recover the extra upfront cost. This simple break-even calculation excludes tax effects, possible refinancing costs and changes in an adjustable payment.
For example, if a hypothetical offer costs $4,000 more upfront and saves $100 per month, the simple break-even period is 40 months. These figures demonstrate the calculation only. They are not a rate, APR, lender quote, available price or promise of savings. A borrower expecting to refinance or sell sooner may evaluate the tradeoff differently.
Can a Prepayment Provision Change the Best Quote?
Review payoff terms before accepting an offer.
It can change the total cost of leaving a loan early. Ask whether the proposed loan has a prepayment penalty, when it applies, how it is calculated and what a comparable option without it costs. Do not assume a term offered for one investment-property program applies to a primary-home bank statement loan. The written loan documents and applicable rules control. The CFPB recommends comparing a similar loan without a prepayment penalty.
If you may sell, refinance or make a large payoff soon, raise that plan before choosing the loan. Check the prepayment disclosure on the Loan Estimate when applicable.
Are Bank Statement Mortgage Rates Higher Than Conventional Rates?
A bank statement mortgage and a conventional loan use different income documentation and investor criteria, so there is no reliable fixed number of percentage points separating their rates. Get actual quotes for both if you may qualify. Compare APR, points, monthly payment, required cash, reserves and the likelihood that each income calculation can support approval.
Start with Self-Employed Mortgage Utah for other documentation paths, including 1099, profit-and-loss and asset-based possibilities. A conventional loan may be worth evaluating first when tax-return income supports it; bank statement financing may warrant consideration when eligible deposits tell a different, supportable story.
How to Get a Useful Utah Bank Statement Rate Quote
- Identify the transaction: purchase, rate-and-term refinance or cash-out refinance; estimated property value and desired loan amount.
- Describe the property: primary residence, second home or investment property; location and property type.
- Review the income path: business or personal statements, 12 or 24 months, ownership, other income and any unusual deposits or account transfers.
- Estimate the full profile: credit, down payment or equity, available reserves and desired payment structure.
- Compare matched written options: rate, APR, points, lender fees, lock terms, payment, closing cash and prepayment provisions.
For the full checklist, use Bank Statement Loan Requirements. If you are buying, read Can You Buy a House Using Bank Statements Instead of Tax Returns?.
Local Bank Statement Mortgage Options Across Utah
Higher loan amounts call for a complete, property-specific comparison.
The same underwriting questions apply statewide, but loan size, property type and occupancy can differ across markets. Read the local guide for Salt Lake City and Salt Lake County, Park City and Deer Valley, Heber City and the Wasatch Back, Utah County and Lehi, or St. George and Southern Utah. A local page does not imply that a particular rate is available there.
Bank Statement Loan Rates Utah: Common Questions
What is the bank statement mortgage rate in Utah today?
There is no single rate for every borrower. Pricing depends on the complete borrower, property and loan scenario and can change. Request a dated quote with APR, points, fees, assumptions and lock status.
Can 12 months of statements get a different rate than 24 months?
Possibly. The documentation period may change which programs are available and how an investor assesses the file. Compare real offers under both methods when eligible.
Does putting 20% down guarantee a better bank statement rate?
No. More equity may change pricing or eligibility, but credit, occupancy, loan amount, reserves, documentation and investor rules still matter.
Is a no-points quote automatically better?
No. Compare the upfront savings against the payment difference and expected time before sale or refinance.
Are bank statement loan rates fixed?
Fixed and adjustable structures may be available under different programs. Verify the offered product, initial payment, adjustment terms and total costs in writing.
Can I lock a rate before my bank statements are reviewed?
Lock timing varies by lender and transaction. Ask when the specific lender permits a lock, which conditions remain, and whether a lock extension costs extra.
Compare Your Bank Statement Mortgage Options
Request a quote based on your actual property and finances.
Send Daniel Paris the proposed property location, approximate purchase price or value, target loan amount, occupancy, estimated credit profile and whether deposits appear in personal or business accounts. Ask for a side-by-side comparison of eligible programs and the full cost of each offer.
Daniel Paris | UtahLowRate.com | NMLS #243976 | Apply or request a review | 801-604-4949
Loan programs and pricing are subject to lender availability, full underwriting and change. Educational examples on this page are not credit offers or approval guarantees.
Request a Bank Statement Income Review · Call Daniel Paris: 801-604-4949

