
$3 Million Mortgage Loans Utah
3 million mortgage loans Utah buyers compare can help fund a luxury home. You may use a jumbo loan to buy a home or replace an existing loan. Daniel Paris helps you compare lenders, income rules and cash needed to close.
Content updated: September 30, 2026
3 Million Mortgage Loans Utah: Jumbo Financing Guide
3 Million Mortgage Loans Utah may fund a main home, second home or rental home. Each lender sets its own rules. UtahLowRate.com helps you compare choices for your home, income and cash.
Check My Jumbo Options or call 801-604-4949.
Get a Utah Mortgage Quote | Explore Jumbo Mortgage Loans Utah | Compare Super Jumbo Loans
Quick Answer: How Do 3 Million Mortgage Loans Utah Work?
3 Million Mortgage Loans Utah are often classed as jumbo or super jumbo mortgages because a $3 million loan is far above conforming loan limits.
Qualified buyers may use these loans to purchase or refinance high-value Utah real estate. The lender checks your credit, income and assets. It also reviews the home’s value and how you will use it. Your loan share of the value, called LTV, matters too.
There is no single set of jumbo lending rules. One lender may have very different rules from another.
That is why comparing lenders can matter on a $3 million mortgage.
3 Million Mortgage Loans Utah: Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | Typical Factor |
|---|---|
| Loan amount | $3,000,000 |
| Loan type | Jumbo or Super Jumbo |
| Purchase | Available with qualifying programs |
| Rate-and-term refinance | Available |
| Cash-out refinance | Select programs |
| Primary residence | Available |
| Second home | Available |
| Investment home | Select programs |
| Fixed rate | Program dependent |
| ARM | Program dependent |
| Interest-only | Select programs |
| Self-employed | Multiple approval methods may be available |
| Bank statements | Select Non-QM programs |
| Asset-based approval | Select programs |
| DSCR | May be available for qualifying rental homes |
Program terms change. The final loan structure depends on the buyer, home, lender, and current loan review rules.
What Is a $3 Million Mortgage?
A $3 million mortgage is a home loan with an original balance of about $3,000,000.
That amount is well above conforming mortgage limits. As a result, buyers often need a jumbo or super jumbo loan.
Jumbo loans do not all follow the same loan review rules.
Lenders may have different standards for:
- Credit scores
- Down payments
- Loan-to-value ratios
- Debt-to-income ratios
- Cash reserves
- Income records
- Self-employed buyers
- Home types
- Second homes
- Investment homes
- Cash-out refinance
- Interest-only payments
This gives you more choices.
A buyer who does not fit one jumbo lender’s guidelines may fit another lender’s program.
For current conforming loan-limit details, buyers can also review the Federal Housing Finance Agency loan-limit resources.
Why 3 Million Mortgage Loans Utah Are Jumbo Loans
3 Million Mortgage Loans Utah are far above the conforming loan limits used by Fannie Mae and Freddie Mac.
That means a $3 million mortgage often falls into the jumbo or super jumbo category.
The loan terms can differ.
Jumbo Mortgage
A jumbo mortgage exceeds the applicable conforming loan limit.
Super Jumbo Mortgage
“Super jumbo” is an industry term often used for larger jumbo mortgages.
There is no single federal dollar amount that officially changes a jumbo mortgage into a super jumbo mortgage.
At the $3 million level, buyers should compare both jumbo and super jumbo lending options.
Learn more about Super Jumbo Mortgage Loans.
Who Uses 3 Million Mortgage Loans Utah?
A $3 million mortgage can fit many types of qualified buyers.
They may include:
- Business owners
- Company leaders
- Doctors
- Business owners
- Real estate professionals
- High-net-worth buyers
- Self-employed buyers
- Luxury-home buyers
- Investors
- Second-home buyers
- Buyers with large investment portfolios
High income alone does not guarantee approval.
A jumbo lender may look at the buyer’s entire income, cash and debts.
That includes income, credit, debts, assets, reserves, ready cash, and the home.
Where Are $3 Million Mortgages Used in Utah?
Large mortgages can be useful throughout Utah. But they are especially relevant in areas with higher-priced homes.
Park City and Deer Valley
Park City is one of Utah’s major luxury real estate markets.
A $3 million mortgage may help finance a qualifying home in areas such as:
- Deer Valley
- Empire Pass
- Old Town
- Canyons Village
- Promontory
- Prospector
- Kimball Junction
- Greater Park City
Financing may be available for a primary residence, second home, or qualifying rental home.
Salt Lake City and Salt Lake County
High-value homes are also found throughout Salt Lake County.
Relevant markets include:
- Salt Lake City
- Holladay
- Cottonwood Heights
- Millcreek
- Sandy
- Draper
- South Jordan
- Bluffdale
Luxury buyers in these areas may need jumbo financing even when their loan amount is well below $3 million.
Alpine, Highland and Utah County
Alpine and Highland have many custom and luxury homes.
Large mortgages may also be relevant in:
- Lehi
- American Fork
- Pleasant Grove
- Orem
- Provo
Heber City and the Wasatch Back
The Wasatch Back has become another key luxury-home market.
Areas include:
- Heber City
- Midway
- Jordanelle
- Hideout
- Kamas
St. George and Southern Utah
Southern Utah also has a growing luxury-home market.
Buyers may seek jumbo financing in:
- St. George
- Ivins
- Santa Clara
- Washington
- Hurricane
- Desert Color
Down Payment for 3 Million Mortgage Loans Utah
The down payment for 3 Million Mortgage Loans Utah depends on the lender and loan program.
There is no universal down-payment percentage.
Lenders may consider:
- Credit score
- Home value
- Loan amount
- Home use
- Home type
- Income records
- Cash reserves
- Ready cash
- Purchase price
- Loan-to-value ratio
Here are two simple examples.
$3 Million Loan at 80% LTV
If a lender allows 80% LTV:
Purchase price: $3,750,000
Loan amount: $3,000,000
Down payment: $750,000
LTV: 80%
This is only an example. It is not a loan offer or a statement that 80% LTV is available for a specific buyer.
$3 Million Loan at 70% LTV
At 70% LTV:
Home value: about $4,285,714
Loan amount: $3,000,000
Equity: about $1,285,714
Again, actual rules depend on the lender and buyer.
See the Jumbo Loan Down Payment Utah guide for more details.
Credit Score for 3 Million Mortgage Loans Utah
There is no single credit-score requirement for every 3 Million Mortgage Loans Utah program.
Strong credit can help. But credit is only one part of the decision.
Jumbo lenders may also review:
- Mortgage payment history
- Share of credit used
- Monthly debt payments
- Recent credit checks
- Major credit events
- Loan-to-value ratio
- Income
- Assets
- Cash reserves
- Home type
- Home use
Ask for a full loan review. A credit score alone does not tell you which loans fit.
Read more in the Jumbo Loan Credit Score Utah guide.
How Much Income Is Needed for a $3 Million Mortgage?
There is no universal income number.
The income needed for a $3 million mortgage depends on several factors.
They include:
- Interest rate
- Monthly mortgage payment
- Home taxes
- Homeowners insurance
- HOA dues
- Existing debts
- Other mortgages
- Loan term
- Income type
- Lender guidelines
A standard jumbo lender may document income using:
- Paystubs
- W-2s
- Tax returns
- K-1s
- Business tax returns
- Rental income
- Investment income
- Retirement income
But not every buyer needs to qualify through standard tax returns.
Self-Employed 3 Million Mortgage Loans Utah
Self-employed buyers can have strong cash flow but complicated tax returns.
Business deductions can reduce taxable income. That may make conventional income calculations difficult.
Qualified buyers may have other options.
Bank Statement Jumbo Loans
Some programs allow allowed bank statements to help check qualifying income.
Depending on the program, lenders may review personal or business bank statements.
Learn more about Jumbo Bank Statement Loans Utah.
Profit and Loss Programs
Some lenders use a profit and loss report to review income. The report must meet the lender’s rules.
Guidelines vary by lender.
Asset Depletion
Some buyers have large assets but less income each month.
Some lenders use an asset-based formula to estimate income. Only assets that meet their rules count.
Full Records
Self-employed buyers can also qualify through standard tax returns when that method works.
The goal is not simply to find the easiest records.
The goal is to find the mortgage structure that best fits the buyer.
Cash Reserves for a $3 Million Mortgage
Jumbo lenders often pay close attention to cash reserves.
Reserves are assets that remain after the mortgage closes.
A lender may want to see enough reserves to cover a some number of months of housing payments.
Allowed assets may include some:
- Checking accounts
- Savings accounts
- Money-market accounts
- Brokerage accounts
- Stocks
- Bonds
- Retirement accounts
Not every asset is counted at full value.
The lender may apply a discount to some investment or retirement assets.
Reserve rules can also increase with loan size or the number of homes owned.
Purchase Options for 3 Million Mortgage Loans Utah
3 Million Mortgage Loans Utah can be used to purchase qualifying luxury homes.
For a large purchase, getting pre-approved early can help.
A jumbo pre-approval may review:
- Credit
- Income
- Assets
- Down payment
- Reserves
- Existing mortgages
- Home type
- Home use
- Requested loan amount
This review can uncover problems before the buyer enters a purchase contract.
Read the Utah Mortgage Pre-Approval guide.
Refinance Options for 3 Million Mortgage Loans Utah
Homeowners may also use 3 Million Mortgage Loans Utah for a refinance.
Common reasons include:
- Lowering an interest rate
- Changing the loan term
- Replacing an ARM
- Switching to an ARM
- Changing an interest-only structure
- Consolidating allowed debt
- Restructuring a large mortgage
A refinance should be compared using more than the interest rate.
Review the APR, closing costs, monthly payment, break-even period, and long-term cost.
See Jumbo Refinance Loans Utah for more details.
$3 Million Jumbo Cash-Out Refinance
Some jumbo lenders allow cash-out refinance.
The available amount can depend on:
- Home value
- Existing mortgage balance
- Requested loan amount
- LTV
- Credit
- Home use
- Home type
- Ownership history
- Reserves
- Overall buyer strength
Cash-out limits often become more restrictive as loan balances rise.
For more details, visit Jumbo Cash-Out Refinance Utah.
Fixed-Rate vs. ARM $3 Million Mortgages
A buyer may have access to fixed-rate or adjustable-rate financing.
Fixed-Rate Jumbo Mortgage
A fixed-rate loan keeps the same rate for the full loan term.
This makes principal and interest payments easier to predict.
Jumbo ARM
An adjustable-rate mortgage often has an initial fixed period.
The rate can later adjust under the terms of the loan.
An ARM can make sense for some buyers who do not expect to keep the mortgage for decades.
Check when the rate can change and how high it can go. Your payment may rise.
Interest-Only $3 Million Mortgage Loans
Select jumbo and super jumbo programs offer interest-only payments.
During this period, the required payment covers interest. It does not pay down the loan balance.
That may reduce the initial required payment.
But the principal still needs to be repaid.
Before selecting an interest-only loan, understand:
- Interest-only period
- Note rate
- Adjustment terms
- Remaining amortization period
- Future payment
- Principal balance
- Total interest cost
A lower initial payment does not automatically mean a lower-cost mortgage.
3 Million Mortgage Loans Utah for Second Homes
Qualified buyers may use 3 Million Mortgage Loans Utah for some second homes.
Utah locations where this may be relevant include:
- Park City
- Deer Valley
- Canyons Village
- Heber City
- Midway
- St. George
Second-home rules matter.
A home used mainly as a rental may need to be classified as an rental home instead.
See Jumbo Second Home Loans Utah for more details.
3 Million Mortgage Loans Utah for Rental Homes
Some 3 Million Mortgage Loans Utah programs can finance qualifying rental homes.
Possible options may include:
- Jumbo investment loans
- Non-QM mortgages
- DSCR loans
- Bank statement mortgages
- Asset-based programs
Rental home loans have different rules from main home loans.
The best program depends on the home, rental income, buyer, and loan structure.
Visit Jumbo Rental Home Loans Utah.
DSCR Loans for High-Value Utah Rental Homes
A DSCR loan can be useful when the home is held for investment.
DSCR stands for Debt Service Coverage Ratio.
A DSCR lender compares the rent with the home’s debt payment. The lender sets which rent and costs count. This method may fit a rental home.
This can be useful for real estate investors with multiple homes.
Explore the Utah DSCR Loan Cluster
Start with DSCR Mortgage Loans Utah.
Then review:
- DSCR Loan Rules Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Loans Salt Lake City
- DSCR Loans Park City
- DSCR Loans St. George
Rental-home buyers should compare DSCR financing with standard jumbo investment loans when both are available.
$3 Million Mortgage vs. Paying Cash
Some luxury buyers can pay cash but choose to use a mortgage.
Why?
They may want to:
- Keep more cash available
- Avoid selling investments
- Keep cash in the business
- Buy more real estate
- Keep a mix of investments
Financing also has costs.
Buyers should consider interest, fees, taxes, investment risk, and ready cash.
For tax or investment advice, consult the appropriate qualified professional.
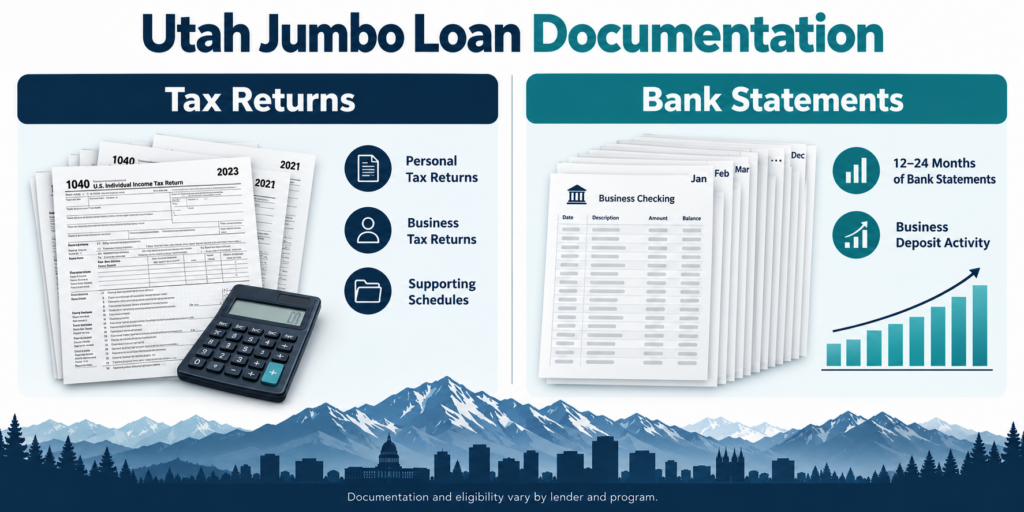
Documents for 3 Million Mortgage Loans Utah
Documents depend on the loan program.
A buyer may need:
- Photo ID
- Mortgage application
- Credit authorization
- Paystubs
- W-2s
- Personal tax returns
- Business tax returns
- K-1s
- Bank statements
- Brokerage statements
- Retirement statements
- Mortgage statements
- Real estate schedules
- Home sale contract
- Insurance details
Other income methods may need different records.
Ask which records the lender needs before you send them.
How to Qualify for 3 Million Mortgage Loans Utah
The process can be easier when it is broken into steps.
1. Check the Loan Amount
Start with the purchase price or current home value.
Then check how much you want to borrow.
2. Review Your Credit
Credit can affect the rate, LTV, and available programs.
3. Choose an Income Method
Check whether pay stubs or tax returns show enough income.
If they do not, ask about other income methods.
4. Review Your Assets
Calculate the funds available for:
- Down payment
- Closing costs
- Reserves
5. Compare Jumbo Programs
Do not assume every jumbo lender has the same rules.
They do not.
6. Get Pre-Approved
Get a loan review before you make an offer on a high-priced home.
7. Complete the Appraisal
The lender may ask for more checks on the home’s value.
8. Complete Loan Review
The lender reviews the buyer, home, title, assets, income, and other required documents.
Why Use a Mortgage Broker for a $3 Million Utah Mortgage?
Large mortgages can vary greatly from lender to lender.
One lender may have a lower maximum LTV.
Another may handle self-employed income better.
Another may offer interest-only financing.
Another may be more flexible with reserves or large loan balances.
A broker can compare several lenders and their rules.
Daniel Paris has worked in home lending for more than 27 years. He helps Utah buyers compare jumbo and super jumbo loans.
Compare Related Utah Jumbo Loan Programs
If you are researching 3 Million Mortgage Loans Utah, these guides can help:
- Jumbo Mortgage Utah
- Super Jumbo Mortgage Loans Utah
- Jumbo Loan Limits Utah
- Jumbo Loan Down Payment Utah
- Jumbo Loan Credit Score Utah
- Jumbo Purchase Loans Utah
- Jumbo Refinance Loans Utah
- Jumbo Cash-Out Refinance Utah
- Jumbo Second Home Loans Utah
- Jumbo Rental Home Loans Utah
- Jumbo Loans for Self-Employed Buyers Utah
- Jumbo Bank Statement Loans Utah
You can also compare general Utah Mortgage Rates.
Frequently Asked Questions About 3 Million Mortgage Loans Utah
Can I get a $3 million mortgage in Utah?
Yes, if you meet the lender’s rules. The lender checks credit, income and cash. It also reviews the home, loan size and funds left after closing.
Are 3 Million Mortgage Loans Utah classed as jumbo mortgages?
Yes. 3 Million Mortgage Loans Utah are far above conforming mortgage limits. They often require jumbo, super jumbo, or another non-conforming loan program.
How much down payment do I need on a $3 million mortgage?
It depends on the program. For example, a $3 million loan at 80% LTV would require a $3.75 million home value or purchase price. Actual maximum LTV varies by lender.
How much income is needed for a $3 million mortgage?
There is no fixed income amount. The lender reviews your home payment and other debts. Taxes and insurance count too. Your income and assets must meet the loan rules.
Can a self-employed buyer get a $3 million mortgage?
Yes, if you qualify. You may use tax returns to show income. Some lenders also offer bank statement or asset-based loans.
Can I finance a $3 million mortgage in Park City?
Potentially. Jumbo and super jumbo financing may be available for qualifying homes in Park City, Deer Valley, Canyons Village, and other Summit County communities.
Can I get a $3 million mortgage on a second home?
Potentially. Some jumbo lenders allow high-balance second-home financing. Home use, LTV, reserves, credit, and home guidelines apply.
Can a $3 million loan finance an rental home?
Yes, with select programs. Options may include jumbo investment loans, Non-QM loans, and qualifying DSCR programs.
Are interest-only $3 million mortgages available?
Some jumbo and super jumbo programs offer interest-only options. Terms and approval rules vary by lender.
Are $3 million mortgage rates higher?
Not always. Rates depend on the market and your loan details. Credit, cash, home use and loan size all matter. Compare quotes for the same loan.
Get a Quote for 3 Million Mortgage Loans Utah
Finding the right 3 Million Mortgage Loans Utah program starts with the complete income, cash and debts.
The best option may be a standard jumbo mortgage. It could also be a super jumbo, bank statement, asset-based, or rental-home program.
UtahLowRate.com helps qualified buyers compare options for luxury homes throughout Utah.
That includes Park City, Deer Valley, Salt Lake City, Holladay, Cottonwood Heights, Draper, Alpine, Highland, Heber City, Midway, and St. George.
Daniel Paris
Utah Mortgage Broker
NMLS #243976
UtahLowRate.com
801-604-4949
Loan rules, rates and terms can change. This guide is for learning and is not a loan offer. The lender must approve you and the home. Credit, income, cash and home value checks still apply.
Related guides: Utah jumbo mortgage guide · Jumbo loan rules · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

