
Content updated: September 29, 2026
$5 Million Mortgage Loans Utah are designed for borrowers financing luxury homes, second homes and qualifying investment properties that require substantially more financing than conventional mortgage programs provide.
At this loan size, choosing the right lender can matter as much as the interest rate. Underwriting may involve substantial assets, complex income, business ownership, multiple properties, trusts, investment accounts or alternative income documentation.
Check My Jumbo Options or call 801-604-4949.
UtahLowRate.com helps qualified borrowers compare jumbo and super jumbo mortgage options for high-value properties throughout Utah.
Daniel Paris
Utah Mortgage Broker | UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Compare Super Jumbo Mortgage Options
Quick Answer: Can You Get a $5 Million Mortgage in Utah?
Yes. $5 Million Mortgage Loans Utah may be available for qualified borrowers purchasing or refinancing high-value properties.
A $5 million mortgage is well above conventional conforming loan limits and normally requires jumbo or super jumbo financing. Depending on the lender, financing may be available for primary residences, second homes and qualifying investment properties.
Approval can depend on credit, property value, loan-to-value ratio, income or cash flow, liquidity, reserves and the borrower's complete financial profile.
$5 Million Mortgage Quick Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | General Guideline |
|---|---|
| Loan amount | $5,000,000 |
| Loan category | Jumbo / Super Jumbo |
| Primary residence | Available through qualifying programs |
| Second home | Available through qualifying programs |
| Investment property | Select programs |
| Purchase | Available |
| Rate-and-term refinance | Available |
| Cash-out refinance | Select programs |
| Fixed-rate options | May be available |
| ARM options | May be available |
| Interest-only | Select programs |
| Traditional income | Available |
| Self-employed | Available through qualifying programs |
| Bank statements | Select programs |
| Asset-based qualification | Select programs |
| DSCR | Investment properties only |
| Reserves | Typically important |
| Final approval | Subject to complete underwriting |
Guidelines vary substantially among jumbo and super jumbo lenders. These are general examples rather than guarantees of approval.
Why a $5 Million Mortgage Is Different From a Conventional Loan
A $5 million mortgage is not simply a conventional mortgage with a larger balance.
The underwriting can be much more detailed.
A lender may examine:
- Credit history
- Loan-to-value ratio
- Property type
- Occupancy
- Income stability
- Business ownership
- Liquid assets
- Investment accounts
- Post-closing reserves
- Other financed properties
- Global cash flow
- Appraisal characteristics
- Marketability of the property
- Source of down payment and closing funds
High-balance transactions can also require more customized underwriting.
That makes lender selection especially important.
Learn more in our Utah Jumbo Mortgage Guide.
$5 Million Mortgage Loans Utah for Luxury Homes
Utah has several markets where luxury-property prices can support the need for multimillion-dollar financing.
These include:
Park City and Summit County: Park City, Deer Valley, Empire Pass, Old Town, Canyons Village, Promontory and surrounding luxury communities.
Wasatch County: Heber City, Midway, Jordanelle and surrounding areas.
Salt Lake County: Salt Lake City, Holladay, Cottonwood Heights, Sandy and Draper.
Utah County: Alpine, Highland, Lehi and surrounding communities.
Southern Utah: St. George, Ivins, Santa Clara, Washington and qualifying luxury communities throughout Washington County.
The right mortgage structure can differ considerably between a $5 million primary residence in Salt Lake County and a luxury second home in Deer Valley.
How Much Is the Down Payment on a $5 Million Mortgage?
The required down payment depends on the loan amount, not simply the purchase price.
For example, a borrower purchasing a $6.25 million property with a $5 million mortgage would have an 80% loan-to-value ratio.
A $7.15 million property with a $5 million mortgage would be approximately 70% LTV.
A $10 million property with a $5 million mortgage would be 50% LTV.
Lower LTV can sometimes expand lender options or improve pricing because the borrower has more equity in the property.
However, maximum LTV varies according to lender, loan amount, occupancy, credit, property type and documentation.
Learn About Jumbo Loan Down Payments
Credit Requirements for a $5 Million Mortgage
There is no universal credit score requirement for every $5 million mortgage.
Credit standards can become more restrictive as loan amounts increase.
Lenders may review more than the numerical score. They can also examine:
- Mortgage payment history
- Revolving credit utilization
- Installment debt
- Recent inquiries
- Derogatory credit
- Foreclosures or bankruptcies
- Number of financed properties
- Overall debt profile
A strong credit profile may increase the number of available lending options.
Read the Utah Jumbo Loan Credit Score Guide
How Much Income Do You Need for a $5 Million Mortgage?
There is no single income requirement.
The answer depends on the proposed mortgage payment, interest rate, taxes, insurance, HOA expenses, other liabilities and the lender's qualifying rules.
Traditional underwriting may evaluate income from sources such as:
- Salary
- Bonuses
- Commissions
- Business income
- Partnership income
- K-1 income
- Rental income
- Investment income
- Trust distributions
- Retirement income
- Other qualifying sources
For wealthy borrowers, income shown on a tax return does not always tell the entire financial story.
That is why alternative jumbo programs can be important.
$5 Million Mortgage Loans for Self-Employed Utah Borrowers
Business owners can have substantial assets and cash flow while reporting lower taxable income because of legitimate business deductions.
Some jumbo and super jumbo lenders provide alternative documentation programs for qualified self-employed borrowers.
Options may include:
Bank Statement Mortgages
Eligible personal or business bank deposits may be analyzed to determine qualifying income.
Read about Jumbo Bank Statement Loans Utah or the broader Bank Statement Loans Utah guide.
Profit and Loss Programs
Select programs may evaluate qualifying income using a business profit-and-loss statement and supporting documentation.
Asset-Based Qualification
Borrowers with substantial eligible assets may have programs that convert those assets into qualifying income under lender-specific formulas.
Other Non-QM Programs
Alternative documentation may also be available depending on the borrower's financial circumstances and property.
Asset-Rich Borrowers and $5 Million Mortgages
Some high-net-worth borrowers have significant wealth but deliberately keep their taxable income relatively low.
Their financial position may include:
- Brokerage accounts
- Stocks and bonds
- Retirement accounts
- Business interests
- Real estate holdings
- Trust assets
- Cash reserves
Select jumbo lenders may offer qualification strategies designed for asset-rich borrowers.
The exact treatment of assets varies by lender. Eligibility can depend on asset type, ownership, liquidity, age, seasoning and whether funds will also be used for closing.
Can Investment Assets Be Pledged Instead of Liquidated?
Certain private-bank and high-net-worth mortgage structures may permit eligible financial assets to support the transaction without requiring the borrower to liquidate the entire portfolio.
This can be attractive when selling appreciated securities could create tax consequences or interfere with an investment strategy.
Pledged-asset financing introduces additional investment and lending risks, however. Borrowers should understand collateral requirements, maintenance requirements and what can happen if pledged assets decline in value.
$5 Million Mortgage for a Utah Second Home
Second-home financing can be especially relevant in Utah's resort markets.
Park City, Deer Valley, Promontory, Canyons Village, Heber City, Midway and Jordanelle can attract borrowers seeking high-value second residences.
Underwriting may consider:
- Property location
- Intended occupancy
- Existing primary residence
- Borrower's financial capacity
- Property characteristics
- HOA structure
- Reserves
- LTV
- Credit
- Other real estate owned
See our Jumbo Second Home Loans Utah guide for more information.
$5 Million Investment Property Loans Utah
Financing may also be available for qualifying high-value investment properties.
Traditional jumbo investment-property underwriting may use the borrower's personal income and rental income.
Another potential option is DSCR financing.
$5 Million DSCR Loans
A DSCR mortgage generally evaluates whether a rental property's qualifying income can support its applicable housing debt rather than relying primarily on the investor's traditional personal employment income.
DSCR programs are generally designed for business-purpose investment properties, not owner-occupied homes.
Start with our DSCR Mortgage Loans Utah guide.
$5 Million Purchase Loans Utah
Super jumbo financing may be used to acquire qualifying luxury properties.
A strong pre-purchase review should examine:
- Purchase price
- Desired loan amount
- Down payment
- Credit
- Income documentation
- Available liquidity
- Required reserves
- Property type
- Occupancy
- Target closing date
Comparing programs before making an offer can be especially important with multimillion-dollar properties.
Learn More About Jumbo Purchase Loans Utah
$5 Million Mortgage Refinance Utah
Existing luxury homeowners may refinance for several reasons.
Possible goals include:
- Reducing the interest rate
- Changing loan terms
- Moving from an ARM to fixed financing
- Moving from fixed financing to an ARM
- Restructuring existing debt
- Removing a borrower
- Consolidating eligible liens
- Accessing home equity
The benefit of refinancing should be evaluated against closing costs, interest expense and how long the borrower expects to retain the mortgage.
Explore Jumbo Refinance Loans Utah
$5 Million Cash-Out Refinance Utah
Qualified borrowers with substantial home equity may be able to access some of that equity through a jumbo cash-out refinance.
Cash-out proceeds might be used for purposes such as:
- Investment opportunities
- Business liquidity
- Property improvements
- Real estate purchases
- Debt restructuring
- Other eligible purposes
Maximum cash-out and LTV requirements can become more restrictive at higher loan balances.
Read About Jumbo Cash-Out Refinance Utah
Fixed Rate vs ARM for a $5 Million Mortgage
Both structures can be worth evaluating.
Fixed-Rate Mortgage
A fixed-rate mortgage keeps the note rate unchanged for the fixed loan term.
This can appeal to borrowers prioritizing long-term payment stability.
Adjustable-Rate Mortgage
Jumbo lenders may offer ARM structures such as 5-, 7- or 10-year initial fixed periods.
An ARM may appeal to borrowers who expect to sell, refinance or otherwise repay the loan before long-term rate adjustments become relevant.
The correct comparison should consider more than the starting rate.
Compare:
- Interest rate
- APR
- Points
- Lender fees
- Initial fixed period
- Adjustment index
- Margin
- Adjustment caps
- Prepayment provisions
- Expected holding period
Interest-Only $5 Million Mortgage Options
Select super jumbo lenders may offer interest-only payment structures.
During the interest-only period, the scheduled payment generally does not reduce principal.
That can lower the required monthly payment during that period, but the borrower does not build equity through principal reduction from those payments.
Interest-only mortgages therefore require careful evaluation of the long-term repayment strategy.
Reserves for a $5 Million Mortgage
Liquidity can be particularly important in super jumbo underwriting.
A lender may require borrowers to retain significant eligible assets after closing.
Reserve requirements can vary according to:
- Loan amount
- LTV
- Occupancy
- Property type
- Number of financed properties
- Credit profile
- Income documentation
- Overall financial strength
Do not assume that all assets receive identical treatment.
Retirement accounts, brokerage accounts, cash, business funds and other assets may receive different treatment under lender guidelines.
Appraisals for Multimillion-Dollar Utah Properties
Luxury homes can be more difficult to value because comparable sales may be limited.
A unique Deer Valley estate, large Park City ski property or custom home in another Utah luxury market may not have several nearly identical nearby sales.
Depending on the lender and transaction, additional appraisal requirements may apply.
The lender will evaluate whether the property provides acceptable collateral for the requested mortgage.
Documents You May Need
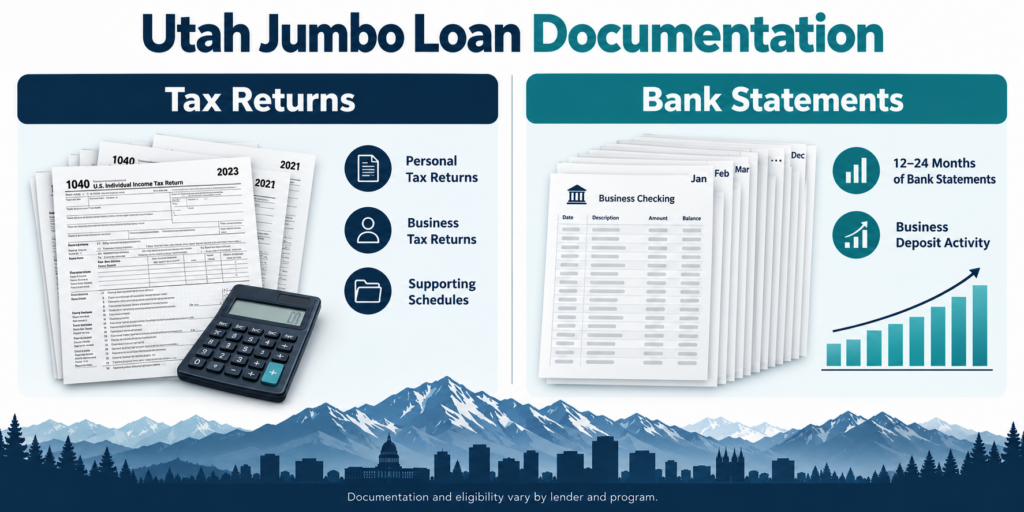
Documentation varies by program, but borrowers should be prepared to provide applicable items such as:
- Identification
- Purchase contract
- Bank statements
- Brokerage statements
- Retirement statements
- Income documentation
- Business documentation
- Existing mortgage statements
- Real-estate-owned schedule
- Insurance information
- Entity documents
- Trust documents
- Letters of explanation when required
Alternative-documentation financing does not mean no underwriting.
$5 Million Mortgage Loans in Park City and Deer Valley
Park City is one of Utah's most important markets for super jumbo financing.
Properties in Park City, Deer Valley, Empire Pass, Promontory, Canyons Village and Old Town can create financing needs that fall well beyond conventional mortgage limits.
Borrowers may include:
- Executives
- Business owners
- Entrepreneurs
- Real estate investors
- Physicians
- Attorneys
- Professional athletes
- High-net-worth families
- Second-home buyers
A borrower purchasing a multimillion-dollar resort property should have the financing structure reviewed early in the transaction.
$5 Million Mortgage Loans in Salt Lake City
Luxury financing needs also occur throughout the Salt Lake Valley.
UtahLowRate.com can help qualified borrowers evaluate jumbo and super jumbo financing in Salt Lake City, Holladay, Millcreek, Cottonwood Heights, Sandy, Draper, South Jordan and surrounding communities.
Properties and borrowers differ, so underwriting should be structured around the complete transaction rather than the loan amount alone.
How to Qualify for a $5 Million Mortgage in Utah
Step 1: Define the Transaction
Determine whether the loan is for a purchase, refinance or cash-out refinance.
Step 2: Review the Property
Identify the purchase price or estimated value, property type and occupancy.
Step 3: Determine the Desired Loan Amount
A borrower does not necessarily need to borrow the maximum amount available.
Step 4: Review Credit
Credit can affect eligibility, LTV and pricing.
Step 5: Determine the Best Documentation Method
Traditional income, bank statements, assets or another qualifying approach may be appropriate.
Step 6: Review Liquidity and Reserves
Large mortgage transactions often place significant emphasis on assets remaining after closing.
Step 7: Compare Wholesale Programs
Compare the complete financing structure rather than only the headline interest rate.
Why Compare Multiple Super Jumbo Lenders?
Jumbo lenders do not all use identical guidelines.
One lender might be stronger for a W-2 executive.
Another may work better for a business owner.
Another may specialize in asset-rich borrowers.
Another may offer better options for second homes, investment properties or unusually large mortgage balances.
A mortgage broker can compare available wholesale programs and determine which lenders are better aligned with the transaction.
Related Utah Jumbo Mortgage Guides
Explore these related resources:
- Utah Jumbo Mortgage Loans
- Super Jumbo Mortgage Loans Utah
- Jumbo Loan Limits Utah
- Jumbo Loan Down Payment Utah
- Jumbo Loan Credit Score Utah
- Jumbo Purchase Loans Utah
- Jumbo Refinance Loans Utah
- Jumbo Cash-Out Refinance Utah
- Jumbo Loans for Self-Employed Borrowers Utah
- Jumbo Second Home Loans Utah
- Jumbo Investment Property Loans Utah
- Jumbo Bank Statement Loans Utah
Utah DSCR Loan Resource Cluster
For multimillion-dollar investment-property financing, also explore the UtahLowRate.com DSCR resource center:
- DSCR Mortgage Loans Utah
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Loans Salt Lake City Utah
- DSCR Loans Park City Utah
- DSCR Loans St. George Utah
Frequently Asked Questions About $5 Million Mortgage Loans Utah
Can I get a $5 million mortgage in Utah?
Yes. Qualified borrowers may obtain $5 million jumbo or super jumbo mortgages for eligible Utah properties. Approval depends on the borrower, property, equity, credit, documentation, assets and selected lender.
What credit score do I need for a $5 million mortgage?
There is no single minimum that applies to every lender. Credit requirements vary, and lenders may impose stronger requirements as loan amounts or LTV increase.
How much down payment is required for a $5 million mortgage?
It depends on the property value and maximum LTV allowed by the lender. A $5 million loan at 80% LTV, for example, corresponds to a $6.25 million property value.
Can a self-employed borrower qualify for a $5 million mortgage?
Potentially. Traditional income documentation, bank statements, asset-based qualification and other jumbo programs may be available depending on the borrower's financial profile.
Can I finance a $5 million second home in Park City?
Qualified borrowers may have super jumbo second-home financing options for eligible Park City and Deer Valley properties. LTV, reserves, credit, property characteristics and the borrower's overall financial position can affect eligibility.
Can I get a $5 million DSCR loan in Utah?
Select investment-property programs may support multimillion-dollar DSCR financing, subject to lender loan limits, property cash flow, credit, LTV, reserves and other requirements. DSCR financing is generally intended for business-purpose investment properties rather than owner-occupied homes.
Are interest-only $5 million mortgages available?
Select jumbo and super jumbo programs may provide interest-only payment options. Availability and terms vary by lender.
Can I cash out more than $5 million from a Utah property?
Very large cash-out transactions may be available through select lenders, but maximum cash-out, LTV, property and borrower requirements vary significantly at high loan amounts.
Compare $5 Million Mortgage Loans in Utah
A $5 million mortgage deserves more than a one-size-fits-all loan quote.
The right structure may depend on whether you are financing a primary residence in Salt Lake County, a Deer Valley second home, a Park City luxury property or a high-value Utah investment property.
UtahLowRate.com can compare available jumbo and super jumbo mortgage programs based on your loan amount, property, equity, income documentation, credit, assets and financial objectives.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Ask about $5 Million Mortgage Loans Utah, Super Jumbo Loans, Jumbo Bank Statement Loans, Asset-Based Financing, Luxury Second-Home Loans and Jumbo Investment Property Financing.
Compare Super Jumbo Mortgage Options
Mortgage programs, rates, loan amounts, LTV limits, documentation requirements, credit requirements and reserve requirements vary by lender and are subject to change. All loans are subject to borrower qualification, acceptable property, appraisal, underwriting and program availability. This information is educational and is not a commitment to lend. Equal Housing Opportunity.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

