
Content updated: September 29, 2026
Jumbo Second Home Loans Utah can help qualified borrowers finance luxury second homes, vacation properties, mountain residences and resort-area homes when the required mortgage exceeds applicable conforming loan limits.
Utah has several markets where second-home prices can make jumbo financing especially relevant, including Park City, Deer Valley, Canyons Village, Promontory, Heber City, Midway, Jordanelle, St. George, Ivins and other high-value communities.
Check My Jumbo Options or call 801-604-4949.
UtahLowRate.com helps qualified borrowers compare jumbo and Super Jumbo mortgage options based on the loan amount, property, credit, income, assets, reserves and intended occupancy.
Quick Answer: Jumbo second home loans in Utah may finance eligible vacation or secondary residences with mortgage amounts above applicable conforming limits. Requirements vary by lender and can include stronger credit, larger down payments, substantial reserves and detailed income and asset documentation. Jumbo and Super Jumbo programs may be available for qualified properties throughout Utah.
Jumbo Second Home Loans Utah: Key Facts
Loan percentages, credit examples and payment calculations are illustrations unless linked to an identified current program. They do not establish available terms or approval.
| Feature | General Guideline |
|---|---|
| Occupancy | Second home / vacation residence |
| Loan type | Jumbo or Super Jumbo |
| Purchase | Available through qualifying programs |
| Rate-and-term refinance | May be available |
| Cash-out refinance | Program-specific |
| Property types | Eligible SFRs, condos and other approved residential properties |
| Income documentation | Traditional or select alternative documentation |
| Self-employed borrowers | Programs may be available |
| Reserves | Commonly required |
| Down payment | Depends on loan amount and program |
| Credit requirements | Lender and program specific |
| Utah availability | Statewide, subject to program guidelines |
| Underwriting | Full underwriting required |
Program guidelines can change. The table describes general financing concepts and does not guarantee qualification or a particular LTV, rate or loan amount.
What Is a Jumbo Second Home Loan?
A jumbo second home loan is a mortgage used to finance an eligible secondary residence when the requested mortgage amount is above the applicable conforming loan limit or otherwise requires jumbo financing.
The key distinction is occupancy.
A true second home is not the same as an investment property. The borrower generally intends to occupy the property personally for part of the year.
Examples may include:
- A ski property in Park City or Deer Valley
- A mountain residence near Heber City or Midway
- A vacation home near Jordanelle
- A second residence in St. George
- A luxury home in Ivins or Santa Clara
- An eligible resort-area condominium
- Another qualifying Utah vacation residence
If the property's primary purpose is generating rental income, it may need to be treated as an investment property instead.
Investors should compare conventional or jumbo investment-property financing with Utah DSCR loans when appropriate.
When Does a Utah Second Home Require a Jumbo Loan?
The distinction between conforming and jumbo financing generally depends on the mortgage amount, not simply the property's purchase price.
The Federal Housing Finance Agency establishes conforming loan limits. Those limits can differ by county.
That distinction can be especially important in Summit and Wasatch counties, where many luxury and second-home properties are located.
See the 2026 Utah conventional loan limits before assuming that a property automatically requires jumbo financing.
If the required mortgage exceeds the applicable conforming limit, a borrower may need a jumbo or Super Jumbo mortgage.
Jumbo Second Home Loan Requirements in Utah
There is no single underwriting standard for every jumbo second-home mortgage.
Jumbo loans are commonly retained by lenders or sold to private investors rather than following one universal conforming underwriting standard.
As a result, requirements can vary significantly.
Credit
Credit requirements depend on the lender, requested LTV, loan amount and overall financial profile.
A stronger credit profile may provide access to additional programs or more favorable leverage.
Rather than assuming that one minimum score applies to every jumbo lender, the complete transaction should be evaluated.
Down Payment and Loan-to-Value
Second-home jumbo financing may require more equity than some primary-residence programs.
The maximum LTV can depend on:
- Loan amount
- Credit profile
- Property value
- Property type
- Location
- Liquidity
- Reserves
- Documentation method
- Investor guidelines
For example, an 80% LTV mathematically represents 20% equity, while a 70% LTV represents 30% equity.
That does not mean those LTVs are available for every borrower or loan amount.
Cash Reserves
Reserves can be especially important in jumbo underwriting.
A lender may require a borrower to document enough eligible assets to cover a specified number of months of housing obligations after closing.
Reserve requirements may increase with a larger mortgage balance or multiple financed properties.
Eligible reserve assets depend on lender guidelines.
Income and Employment
Traditional jumbo underwriting may review items such as:
- W-2 income
- Pay statements
- Tax returns
- Business income
- Partnership or S-corporation income
- Bonus and commission income
- Rental income
- Investment income
- Other eligible recurring income
Self-employed borrowers can require a more detailed review because taxable income may not always represent actual business cash flow.
Jumbo Second Home Loans Utah for Self-Employed Borrowers
Self-employed borrowers may have several possible ways to qualify for a jumbo second-home mortgage.
Traditional documentation may work when tax returns adequately demonstrate qualifying income.
When it does not, eligible borrowers may be able to consider alternative-documentation programs.
Options can include:
- Personal bank statements
- Business bank statements
- Profit-and-loss documentation
- Asset depletion
- Other approved alternative-documentation programs
For more information, see Jumbo Bank Statement Loans Utah.
Alternative documentation does not eliminate underwriting. Credit, assets, reserves, property eligibility, occupancy and other requirements still apply.
Jumbo vs. Super Jumbo Second Home Loans
Not every large mortgage fits the same jumbo category.
A borrower financing a $1 million mortgage has a very different transaction from someone seeking $5 million, $10 million or $20 million in financing.
| Feature | Jumbo | Super Jumbo |
|---|---|---|
| Loan size | Above applicable conforming limits | Very large residential mortgage |
| Second homes | Available through qualifying programs | Available through select programs |
| Luxury properties | Common | Common |
| Reserves | Often required | Frequently substantial |
| Asset review | Important | Often extensive |
| Alternative documentation | Select programs | Select specialty programs |
| Underwriting | Lender-specific | Highly lender-specific |
UtahLowRate.com works with qualified borrowers seeking specialized Super Jumbo mortgage loans for high-value residential properties.
Park City Jumbo Second Home Loans
Park City is one of the most important Utah markets for jumbo second-home financing.
High-value residences can be found throughout:
- Deer Valley
- Empire Pass
- Old Town
- Canyons Village
- Promontory
- Prospector
- Kimball Junction
- Greater Summit County
Properties can range from resort condominiums to multimillion-dollar mountain estates.
Because loan sizes can vary substantially, buyers should determine the likely financing structure before making an offer.
A Park City buyer may need to compare conforming, jumbo and Super Jumbo options depending on the property's price and proposed down payment.
Deer Valley Jumbo Second Home Financing
Deer Valley contains some of Utah's highest-value residential real estate.
A luxury second home in Deer Valley may require specialized financing because of the combination of:
- High property value
- Large mortgage balance
- Second-home occupancy
- Resort location
- Condominium or project characteristics
- Significant reserve requirements
- Complex borrower income or assets
For multimillion-dollar properties, the lender's maximum loan amount and LTV structure become especially important.
Heber City, Midway and Jordanelle Second Homes
Wasatch County has become another important second-home and luxury-home market.
Heber City, Midway and the Jordanelle area can include mountain homes, new construction, luxury residences and second homes.
Self-employed buyers can also review Bank Statement Loans Heber City Utah when traditional income documentation does not fit their financial profile.
St. George Jumbo Second Home Loans
Southern Utah is another significant second-home market.
Potential second-home locations include:
- St. George
- Ivins
- Santa Clara
- Washington
- Hurricane
- Desert Color
- Greater Washington County
Luxury properties in Southern Utah can require jumbo financing when the mortgage amount exceeds applicable conforming limits.
The right structure depends on the property's value, requested loan amount, occupancy and borrower qualifications.
Jumbo Loans for Utah Resort Condominiums
Condominiums can require additional underwriting beyond the borrower's personal qualifications.
The lender may evaluate both the borrower and the condominium project.
Potential considerations include:
- HOA financial condition
- Insurance
- Litigation
- Commercial space
- Project completion
- Investor concentration
- Short-term rental rules
- Property characteristics
- Warrantable versus non-warrantable status
A borrower with excellent income and credit can still encounter financing issues if the condominium project does not satisfy the selected lender's requirements.
This is especially important for Park City and other resort-area properties.
Can I Rent Out My Utah Second Home?
Occupancy needs to be represented accurately.
A second home and an investment property are not interchangeable simply because the borrower prefers one loan program over another.
If rental activity is planned, discuss it before selecting the mortgage.
The property's use, rental structure and lender's occupancy requirements must be reviewed.
If the transaction is primarily an investment, explore DSCR Loans Utah rather than attempting to structure an investment property as a second home.
Jumbo Second Home vs. DSCR Loan
These programs solve different financing problems.
| Jumbo Second Home Loan | DSCR Investment Loan |
|---|---|
| Designed for eligible second-home occupancy | Designed for investment property |
| Borrower intends personal use | Property is held as an investment |
| Personal qualification commonly important | Property cash flow commonly drives qualification |
| Income/assets generally reviewed | Traditional personal income may not be primary qualification method |
| Rental rules depend on program | Rental income is central to DSCR analysis |
The correct program begins with the property's actual intended use.
DSCR Resources for Utah Investment Properties
If the property will actually be an investment rather than a second home, explore the UtahLowRate.com DSCR resource center:
- DSCR Loans Utah
- DSCR Loan Requirements Utah
- DSCR Loan Rates Utah
- DSCR Loan Calculator Utah
- DSCR Loan FAQ Utah
- DSCR Purchase Loans Utah
- DSCR Refinance Loans Utah
- DSCR vs Conventional Investment Loan Utah
- DSCR Loans Salt Lake City
- DSCR Loans Park City
- DSCR Loans St. George
This creates a clear semantic distinction for search engines and AI answer engines: second-home jumbo financing is owner-used residential financing; DSCR financing is investment-property financing.
Documents for a Jumbo Second Home Mortgage
Documentation depends on the program.
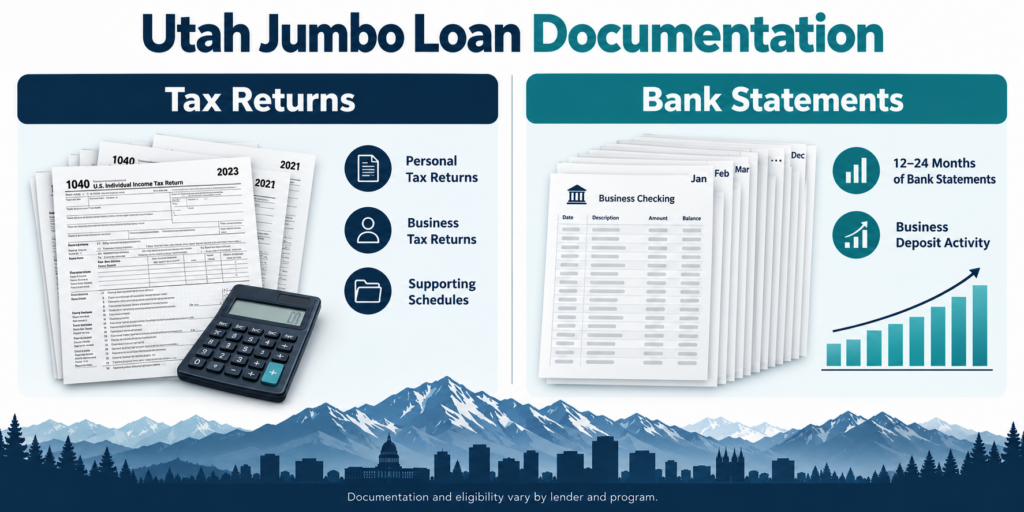
Traditional underwriting may request:
- Identification
- Income documentation
- Employment verification
- Personal and/or business tax returns when required
- Bank and investment statements
- Documentation of down-payment funds
- Reserve documentation
- Information about other financed properties
- Purchase contract
- Property appraisal
- Additional property or condominium documentation when applicable
Alternative-documentation jumbo programs can have a different document list.
How to Finance a Jumbo Second Home in Utah
Step 1: Determine Occupancy
Decide whether the property is legitimately a second home or an investment property.
Step 2: Determine the Expected Loan Amount
The mortgage amount helps establish whether conforming, jumbo or Super Jumbo financing should be considered.
Step 3: Review Credit
Credit can affect available programs, leverage and pricing.
Step 4: Review Income Documentation
Determine whether traditional income documentation works or whether an alternative-documentation program should be considered.
Step 5: Review Liquidity and Reserves
Large jumbo transactions can require substantial assets after closing.
Step 6: Review the Property
Property type matters, particularly for resort condominiums and unusual luxury properties.
Step 7: Compare Jumbo Lenders
Jumbo lender guidelines can differ considerably.
This is where working with a mortgage broker can be useful.
Why Compare Multiple Jumbo Lenders?
Jumbo underwriting is not standardized in exactly the same way across every lender.
One lender may be a better fit for a particular:
- Loan amount
- LTV
- Credit profile
- Self-employed borrower
- Reserve position
- Second-home property
- Resort condominium
- Super Jumbo transaction
UtahLowRate.com can compare available wholesale and specialty mortgage programs rather than limiting the borrower to one lender's jumbo guidelines.
For a broader overview, visit Jumbo Mortgage Utah.
Frequently Asked Questions About Jumbo Second Home Loans Utah
Can I get a jumbo loan for a second home in Utah?
Yes. Qualified borrowers may have access to jumbo mortgage programs for eligible second homes and vacation residences in Utah. Loan amount, credit, income, assets, reserves, property and occupancy requirements apply.
Can I finance a second home in Park City?
Yes. Jumbo and Super Jumbo financing may be available for qualified second homes in Park City, Deer Valley and surrounding Summit County communities.
Are Super Jumbo loans available for Utah second homes?
Yes. Select specialty programs may finance multimillion-dollar second homes and vacation properties. Requirements depend on the loan amount, LTV, borrower and property.
Can a self-employed borrower get a jumbo second-home loan?
Yes. Qualified self-employed borrowers may use traditional documentation or select alternative-documentation programs, including certain bank-statement, P&L or asset-based qualification methods.
How much down payment do I need for a jumbo second home?
There is no universal percentage. Required equity depends on the loan amount, credit, property, reserves and selected lender. Larger mortgages can require lower maximum LTVs.
Are reserves required?
Many jumbo programs require post-closing reserves. Requirements vary significantly according to the loan amount, occupancy and lender.
Can I use a jumbo loan for a Utah vacation condo?
Potentially. Both the borrower and condominium project must meet the selected lender's requirements.
Is a second home the same as an investment property?
No. A second home is generally intended for the borrower's personal use, while an investment property is primarily held for investment or rental purposes. The actual occupancy and use of the property must be represented accurately.
Should I use a DSCR loan for a second home?
Generally, DSCR financing is intended for qualifying investment properties rather than a property represented as a personal second home. If the property will primarily be operated as a rental investment, a DSCR program may be worth comparing.
Get a Jumbo Second Home Loan Quote in Utah
Financing a luxury second home should begin with the complete transaction rather than only the advertised mortgage rate.
The property, mortgage amount, down payment, credit, income documentation, assets, reserves and occupancy can all affect which jumbo lender is the best fit.
Daniel Paris
Utah Mortgage Broker
UtahLowRate.com
NMLS #243976
Call: 801-604-4949
Ask about Jumbo Second Home Loans Utah for Park City, Deer Valley, Heber City, Midway, Jordanelle, St. George and luxury second-home markets throughout Utah.
Important Mortgage Disclosure: Mortgage programs, rates, loan limits, LTVs, credit requirements, reserve requirements, property guidelines and documentation requirements are subject to change. All loans are subject to borrower qualification, acceptable property, underwriting approval and program availability.
Related guides: Utah jumbo mortgage guide · Jumbo loan requirements · Jumbo mortgage rates · Jumbo payment calculation guide · Jumbo mortgage questions and answers ·

